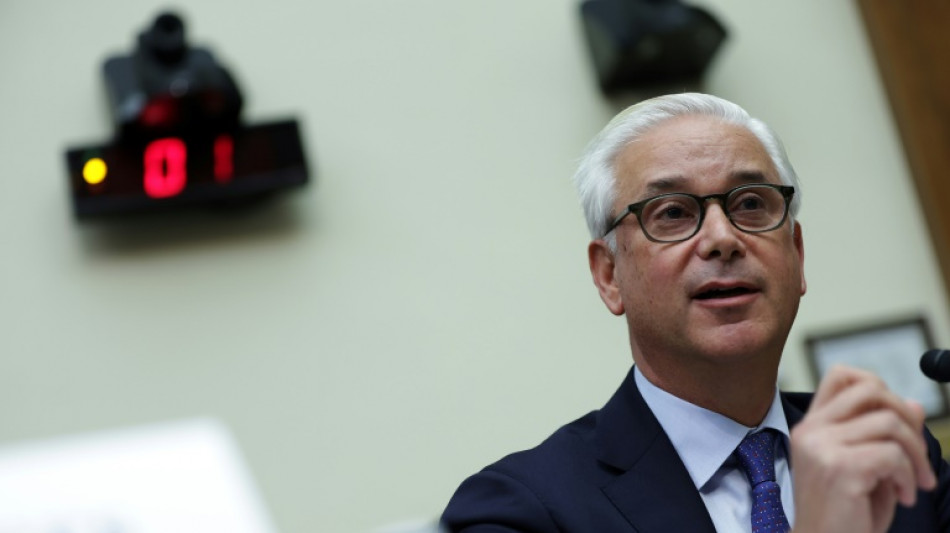
US agency orders Wells Fargo to pay $3.7 bn for shoddy banking practices / Photo: ALEX WONG - GETTY IMAGES NORTH AMERICA/AFP/File
 Teatro Mayor Unveils 152-Performance 2027 Season Highlighting Beethoven and García Márquez
 Rutgers Defeats NJIT 101-64 Behind Francis and Mark Scores
 Guardian Metal Resources PLC Announces Proposed Spin-Out of Non-Tungsten Projects
 Fulcrum Metals PLC Announces New Critical Mineral Recoveries Expand Potential
 Thukukile Zuma Resigns from ANC Johannesburg Leadership Amid Disciplinary Dispute
 CM Mohan Yadav Meets Bohra Spiritual Leader to Discuss Simhastha 2028 and Development
 Eli Crane Defeats Jonathan Nez in Tight Arizona Congressional Race
US officials announced Tuesday a $3.7 billion settlement with Wells Fargo over an array of "illegal activity" that burdened customers with wrongful home foreclosures and other problems.
Wells Fargo will pay $2 billion to compensate customers and $1.7 billion in civil fines under a Consumer Financial Protection Bureau settlement that the agency said pertained to some 16 million consumer accounts.
Wells Fargo called the agreement an "important milestone" in the bank's progress after a series of scandals. Shares edged higher early Tuesday in hopes that the bank could be near the end of a years-long regulatory crackdown.
A CFPB press release listed a series of problems throughout Wells Fargo's consumer businesses, including bungled administration of auto loans that resulted in wrongful repossession of vehicles and the improper denial of mortgage modifications that led to wrongheaded foreclosures.
The bank, headquartered in San Francisco, also charged improper overdraft fees and froze consumer bank accounts based on its faulty determinations that a customer may have made a fraudulent deposit.
The CFPB penalty is the latest in a series of government fines following Wells Fargo's infamous "fake accounts" scandal, in which the bank improperly opened millions of customer accounts without the knowledge of clients.
The fake accounts scandal gained national notoriety in 2016 and played a central role in the departures of two former Wells Fargo CEOs.
"Wells Fargo's rinse-repeat cycle of violating the law has harmed millions of American families," said CFPB Director Rohit Chopra.
"The CFPB is ordering Wells Fargo to refund billions of dollars to consumers across the country. This is an important initial step for accountability and long-term reform of this repeat offender."
Wells Fargo Chief Executive Charlie Scharf characterized the CFPB agreement as "an important milestone in our work to transform the operating practices at Wells Fargo and to put these issues behind us."
Scharf was appointed CEO in 2019. Since then he has beefed up compliance programs and sought to clear the bank from the constraints of a Federal Reserve consent order enacted in 2018.
A Wells Fargo spokeswoman said much of the $2.0 billion in consumer compensation has already been made.
Shares of Wells Fargo rose 0.6 percent to $42.05 in morning trading.
Ch.Kahalev--AMWN