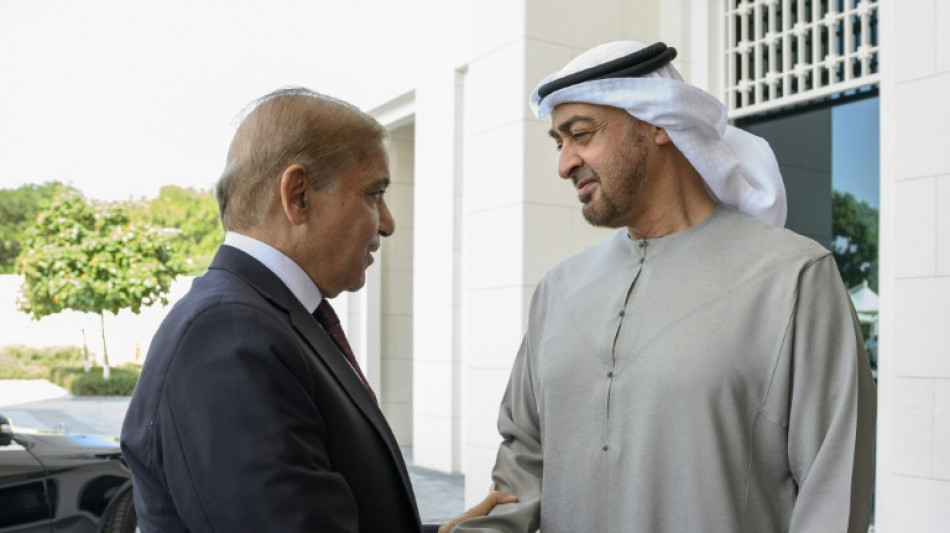
UAE agrees to roll over Pakistan debt, add $1 billion more / Photo: Hamad AL-KAABI - UAE PRESIDENTIAL COURT/AFP
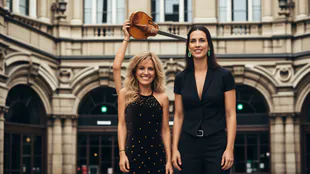 Teatro Mayor Unveils 152-Performance 2027 Season Highlighting Beethoven and García Márquez
 Rutgers Defeats NJIT 101-64 Behind Francis and Mark Scores
 Guardian Metal Resources PLC Announces Proposed Spin-Out of Non-Tungsten Projects
 Fulcrum Metals PLC Announces New Critical Mineral Recoveries Expand Potential
 Thukukile Zuma Resigns from ANC Johannesburg Leadership Amid Disciplinary Dispute
 CM Mohan Yadav Meets Bohra Spiritual Leader to Discuss Simhastha 2028 and Development
 Eli Crane Defeats Jonathan Nez in Tight Arizona Congressional Race
The United Arab Emirates has agreed to roll over $2 billion owed by Pakistan and provide the country with an extra loan of $1 billion, Islamabad said Thursday.
The agreement comes as Pakistan grapples with a major foreign exchange crisis, holding enough reserves to pay for just three weeks of imports.
Pakistan Prime Minister Shehbaz Sharif arrived in the UAE earlier Thursday for talks with top Gulf officials to seek help for the battered economy.
"The UAE president agreed to roll over the existing loan of US$2 billion and provide a US$1 billion additional loan," a statement from Sharif's office said.
"Both sides agreed to deepen the investment cooperation, stimulate partnerships and enable investment integration opportunities between the two countries."
The statement did not provide the terms of the loan agreement.
Pakistan's national debt stands at $274 billion -- or nearly 90 percent of gross domestic product.
The nation's forex reserves have dwindled to less than $6 billion, with obligations of more than $8 billion due in the first quarter alone.
A $7 billion loan agreement with the IMF -- about half of which has already been disbursed -- has stalled because Pakistan has not fully implemented tough economic measures including slashing subsidies and raising taxes.
The economy has also been hammered by devastating monsoon floods that left almost a third of the country under water last year, and the government says it needs more than $16 billion over the next three years to rebuild.
Islamabad won some relief earlier this week when nations pledged over $9 billion to help with recovery efforts.
B.Finley--AMWN