SVB's demise a sign of worry, but limited contagion risk: analysts / Photo: JUSTIN SULLIVAN - GETTY IMAGES NORTH AMERICA/AFP
 Search Underway for 'Dooars Rani' Tigress After Second Escape from Buxa Tiger Reserve
 The Dilemma of Recording Live Music: Preserving Memories vs. Being Present
 AmeriLife Welcomes Finance Veteran Richard Dziadzio as Chief Financial Officer; Names Jim Quinn President & Chief Transformation Officer
 Fulcrum Metals PLC Announces New Critical Mineral Recoveries Expand Potential
 Guardian Metal Resources PLC Announces Proposed Spin-Out of Non-Tungsten Projects
 THIEAUDIO Introduces Clairvoyance MKII: The Evolution of a Signature Sound
 BlackBerry to Participate in Upcoming Investor Conferences
Irving Resources Reports on Drilling in Yamagano Mining Right at the Yamagano Joint Venture, Kyushu, Japan
 XCF Global Hosts USDA at New Rise Renewables Reno as Facility Surpasses 4.4 Million Gallons Since Restart
 Patriot Software Adds Performance Reviews to Patriot HR
 Healixa's FrostPulse(TM) Technology Solves a Major Roadblock to Data Center Growth: Cooling Without the Water Burden
NuRAN Wireless Board Approves Growth Strategy to Scale Recurring Revenue from 5,000+ Contracted Towers
PPX Mining Reports Callanquitas Operating Results for the First Nine Months of 2026
 Valion Bio Reinforces Commitment to American Troops; Discusses Entolimod with Attendees at RW Baird's National Security Conference
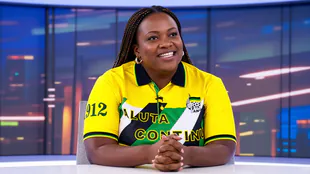 Thukukile Zuma Resigns from ANC Johannesburg Leadership Amid Disciplinary Dispute
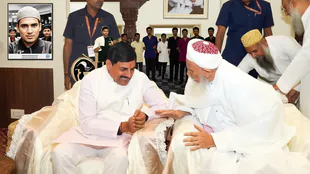 CM Mohan Yadav Meets Bohra Spiritual Leader to Discuss Simhastha 2028 and Development
 Eli Crane Defeats Jonathan Nez in Tight Arizona Congressional Race
The surprisingly rapid implosion of Silicon Valley Bank has markets jittery over a potential sign of widespread turmoil, but analysts see only a limited risk of financial contagion.
SVB's woes are the result of "idiosyncratic stresses and not one that we see as systemic that would affect the banking industry," said CFRA Research's Ken Leon, saying stricter US regulations enacted after the 2008 financial crisis have helped contain trouble.
A note from analysts at Morgan Stanley put it simply, saying, "We want to be very clear here ... we do not believe there is a liquidity crunch facing the banking industry, and most banks in our coverage have ample access to liquidity."
Treasury Secretary Janet Yellen described the US banking sector as "resilient," while Cecilia Rouse, chair of the White House Council of Economic Advisers, also cited US reforms in arguing disaster would be averted.
"Our banking system is in a fundamentally different place than it was a decade ago," Rouse said Friday at a White House briefing.
Following the 2008 demise of Lehman Brothers and the ensuing financial meltdown, US regulators required major banks to hold additional capital in case of trouble. US and European authorities also organize regular "stress tests" designed to uncover vulnerabilities at the largest banks.
For Morningstar analyst Eric Compton, the suddenness of SVB's demise highlights "that it can be very difficult to predict how funding pressure can change in any given quarter and when these risks can materialize," he said in a note this week.
Officially closed and put into receivership by US authorities on Friday, SVB was at risk due to a heavy concentration in its client profile, according to Morgan Stanley.
SVB "primarily banks technology, life science, and healthcare companies and is an integral part of the venture capital ecosystem," Morgan Stanley said.
But the tech sector has been hard hit by the dramatic pivot in US monetary policy, with much higher borrowing rates leading to heavy deposit withdrawals.
- Run on deposits -
Confronted with the need to raise money quickly, SVB sold about $21 billion in securities, resulting in a loss of $1.8 billion.
Because many of SVB's clients held more than the $250,000 that are reimbursed from US-insured institutions, customers began withdrawing funds en masse, precipitating the bank's failure.
Following SVB's disclosure on Wednesday, investors punished the banking sector in total on Thursday. But by Friday, shares in some larger banks posted gains.
But that left many regional lenders still under pressure, including First Republic Bank, which slumped 15 percent and Signature Bank, a cryptocurrency-exposed lender, which plunged 23 percent.
SVB's failure has also focused attention on the risks to financial institutions from the Federal Reserve's aggressive policies to counter inflation.
On the one hand, higher interest rates help the banks by allowing them to charge more interest for loans.
At the same time, the shift dents demand for loans, said CFRA's Leon.
Another problem is in the hit to bank bond assets, which decline in value when interest rates increase.
At the end of 2022, banks had some $620 billion in "unrealized losses" connected to these securities, according to the FDIC.
But the turmoil does not have existential implications for the biggest banks, whose overall assets are "in excess" of the potential call of these bonds and are diversified, Leon said.
O.Johnson--AMWN