5 Facts You Should Know About Insurable Interest in Life Insurance
 North Dakota Enacts Bipartisan Insulin Price Cap Amid National Push
 Basil Tuma Scores First Senior Goal as Malta Draws with Ten-Man Eswatini
 Rock & Roll Hall of Fame Inductees Announced; Attendance List Shrinks
 InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 13
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
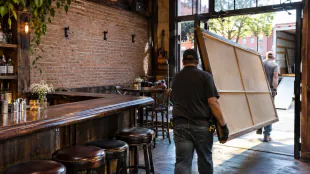 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
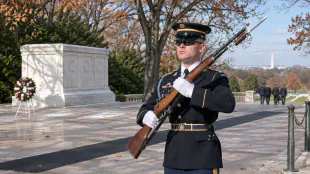 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
 Dhananjaya de Silva guides Sri Lanka to 221-4 against Pakistan
 Delhi gold loses Rs 800 while silver falls Rs 5,000
People generally purchase insurance on themselves to help protect their loved ones or other beneficiaries with a death benefit.However, you can also take out a policy on others if you'd experience financial loss and hardship upon their passing.This is called having an insurable interest in life insurance and represents how financially dependent you are on the insured. Policies can be denied if you lack insurable interest in the insured.This article explains several facts you should know about insurable interest life insurance before investing in a life insurance policy.
1. Insurable interest protects against fraud and moral hazards
The primary reason insurable interest exists is to ensure life insurance is purchased for legitimate reasons and to prevent fraud and moral hazards.For example, one may attempt to purchase life insurance on someone they do not know and have no relationship with. This creates a moral hazard since the policyholder benefits financially from the insured's passing rather than simply being restored financially.Insurable interest prevents this by verifying that the insurer will suffer financial hardship if the insured passes away.
2. Some relationships qualify more easily than others
Certain family relationships easily, and sometimes automatically, qualify for insurable interest. Others may demand more proof.State laws differ, but in general, more direct family relationships automatically qualify for insurable interest:
Spouses
Parent/child relationships
Grandparent/grandchild relationships
Sibling relationships
On the other hand, more distant relationships outside of the direct family may require additional proof of insurable interest:
Cousins
Aunts and uncles/nieces and nephews
Parents-in-law
Stepparent/stepchildren relationships
Nonfamilial guardians
3. There are many ways to prove insurable interest
Many documents help prove insurable interest. The amount and types you need can depend on your relationship with the insured.Here are some ways to prove insurable interest:
Relationship documentation: This may include marriage certificates, birth certificates, and other legal documents showing family or guardianship ties can prove insurable interest. You may need other forms of documentation if the relationship is not direct family.
Financial documentation: This could be proof of potential financial impact or loss, such as tax returns, bank statements, and other documentation that illustrates income and expenses.
Business records: Financial statements, business incorporation documents, legal agreements, or business continuity plans can prove insurable interest for partners or key employees.
Insurance application: The insurance application asks for your relationship with the insured so that the insurer can double-check your application against the facts.
4. The insurer speaks to the potential insured before approval
The insurer doesn't just rely on your documentation to determine that you have an insurable interest. The insured themselves must be involved, providing consent during the application process to be insured on a policy.
This requirement further guards against fraud and moral hazards that may arise from individuals purchasing life insurance on people with whom they have no relationship. It also allows the insured to know the policy's rates, terms, and other information pertinent to them and their policy's owner.
5. Insurable interest is not limited to family members
Family members are not the only ones who may have an insurable interest in you.For example, if you're a business partner, your passing or that of a business partner could create various business and financial difficulties. Business partners may, therefore, have an insurable interest in each other.
If one partner passes away, the other partners receive a death benefit to buy out the deceased's share of the business and replace lost business income due to handling other issues. If either partner gets a permanent life insurance policy, like indexed universal life insurance, they also gain a source of wealth to fund business efforts further.
Similarly, the passing away of key employees, such as senior management, could hamper the company. They would have to invest significant time and money to find a replacement and could lose money.Therefore, a business may have an insurable interest in those employees and be able to get life insurance to protect themselves if you pass away.
The bottom line
Insurable interest requires you to have the potential for financial hardship and loss if the insured passes away. This protects the insured and insurer from fraud and moral hazards, such as gaining from the policyholder's passing.
Fortunately, family members can prove insurable interest fairly easily. Plus, business owners have insurable interest in key employees and other partners, helping them guard their companies if someone passes away.
In most cases, if you're seeking life insurance to protect yourself from financial loss should the insured pass away, there's a good chance you have insured interest. Just make sure you're prepared to prove it and involve the insured in the process.
Content within this article is provided for general informational purposes and is not provided as tax, legal, health, or financial advice for any person or for any specific situation. Employers, employees, and other individuals should contact their own advisers about their situations. For complete details, including availability and costs of Aflac insurance, please contact your local Aflac agent.
Aflac Coverage
Life (A68000 Series) - In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania, Texas, & Virginia, Policies: ICC1368100, ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68100-A68400. In New York, NY68100-NY68400. Term and Whole Life (B60000 Series) - In Arkansas, Idaho, Oklahoma, Pennsylvania, Texas, & Virginia, Policies: ICC18B60C10, ICC18B60100, ICC18B60200, ICC18B60300, & ICC18B60400. Group Whole Life (Q60000 Series) - In Arkansas, Delaware & Oregon, Policy Q60100M. In Idaho Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In Texas, Policy Q60100MTX. Group Term Life (Q60000 Series) - In Delaware, Policies Q60200M. In Arkansas, Idaho, Oklahoma, Oregon & Texas, Policies ICC18Q60200M, ICC18Q60300C, ICC18Q60400C.
Coverage may not be available in all states, including but not limited to DE, ID, NJ, NM, NY or VA. Benefits/premium rates may vary based on state and plan levels. Optional riders may be available at an additional cost. Policies and riders may also contain a waiting period. Refer to the exact policy and rider forms for benefit details, definitions, limitations and exclusions.
Aflac coverage is underwritten by American Family Life Assurance Company of Columbus. In New York, coverage is underwritten by American Family Life Assurance Company of New York.
Aflac WWHQ | Tier One Insurance Company | 1932 Wynnton Road | Columbus, GA 31999.
Aflac New York | 22 Corporate Woods Boulevard, Suite 2 | Albany, NY 12211
Z2401073 EXP 12/25
CONTACT:
Senior PR & Corporate Communications
Contact: Angie Blackmar, 706-392-2097 or [email protected]
SOURCE: Aflac
D.Kaufman--AMWN