Solera National Bancorp Announces Fourth Quarter 2024 Financial Results
 USMNT Coaching Search: Guardiola, Cherundolo, and Others Named as Pochettino Replacements
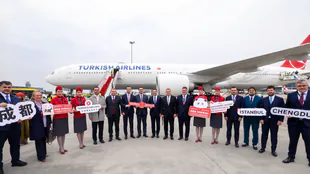 Turkish Airlines Launches Fourth Mainland China Route to Chengdu
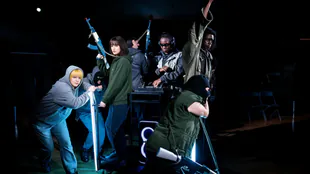 RSC’s ‘Julius Caesar’ Reimagined in Women’s Prison Setting for School Tour
 Thomson Reuters Integrates CUBE Regulatory Intelligence into CoCounsel Legal
 Does IRS Debt Expire? Clear Start Tax Explains the 10-Year Collection Statute and What Quietly Resets It
 Arrive AI Reports Third Quarter 2026 Results Highlighted by Revenue Growth and Expanded Partnerships
 Mako Mining Reports Q3 2026 Financial Results, Including Adjusted EBITDA(1) of US$30.3 million and EPS of US$0.19/share
 InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 13
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
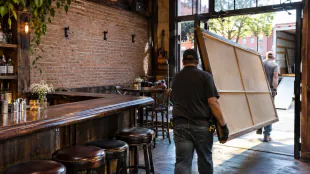 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
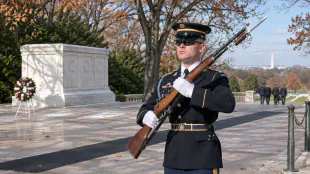 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
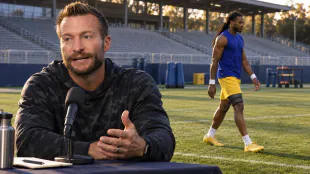 Davante Adams injury deepens Los Angeles Rams receiver shortage
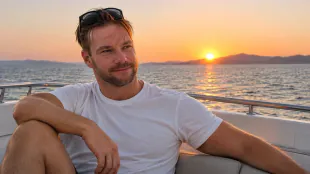 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
Q4 2024 pre-tax and pre-provision income of $6.8 million. 2 nd best ever!
Net income of $5.3 million ($1.24 per share). 2 nd best ever!
LAKEWOOD, CO / ACCESS Newswire / January 24, 2025 / Solera National Bancorp, Inc. (OTC PINK:SLRK) ("Company"), the holding company for Solera National Bank ("Bank"), a business-focused bank located in the Denver metropolitan area, today reported financial results for the three months ended December 31, 2024. For the fourth quarter of 2024, net income was $5.3 million ($1.24 per share). Q4 2024 net interest income of $10.3 million increased $1.6 million or 19% from Q4 2023.
4Q24 Financial Highlights
The Company had a pre-tax and pre-provision income of $6.8 million. 20% or $1.1 million increase from Q4 24.
Net income of $5.3 million ($1.24 per share).
$18 million decrease in special mention assets.
Return on assets was 1.82%.
Return on equity was 23.86%.
Efficiency ratio was 41.47%.
Steve Snailum, COO, commented: "Solera delivers a tremendous end to a remarkable year! The bank is operating at a high level by expertly balancing efficiency and security. The team has been working hard to continue to leverage technology and expertise to deliver robust, secure, and expedient services to our customers. It is a great time to be a Solera employee and customer!"
Jay Hansen, Chief Financial Officer, commented: "Our goal is to get to a 10% Tier 1 capital ratio. We ended 2024 at 9.55% (point in time vs quarterly average), but could have sold $20M in securities to gain another 20 BPS on our ratio. Those securities will mature in March of 2025 and would have taken a loss of over $100K. We chose NOT to sell those securities because we don't sell securities for losses unless a business opportunity presents itself. We will get those 20 BPS in March 2025."
About Solera National Bancorp, Inc.
Solera National Bancorp, Inc. was incorporated in 2006 to organize and serve as the holding company for Solera National Bank, which opened for business in September 2007. Solera National Bank is a community bank serving the needs of emerging businesses and real estate investors. At the core of Solera National Bank is welcoming, attentive, and respectful customer service, a focus on supporting a growing and diverse economy, and a passion to serve our community through service, education, and volunteerism. For more information, please visit http://www.SoleraBank.com.
This press release contains statements that may constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. The statements contained in this release, which are not historical facts and that relate to future plans or projected results of Solera National Bancorp, Inc. and its wholly-owned subsidiary, Solera National Bank, are forward-looking statements. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from those projected, anticipated, or implied. We undertake no obligation to update or revise any forward-looking statement. Readers of this release are cautioned not to put undue reliance on forward-looking statements.
Contacts: Jay Hansen, CFO (303) 209-8600
FINANCIAL TABLES FOLLOW
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED BALANCE SHEET
(unaudited)
($000s) | 12/31/2024 | 9/30/2024 | 6/30/2024 | 3/31/2024 | 12/31/2023 | |||||
ASSETS | ||||||||||
Cash and due from banks | $ | 2,329 | $ | 2,193 | $ | 2,241 | $ | 2,095 | $ | 2,734 |
Federal funds sold | 800 | 400 | - | - | - | |||||
Interest-bearing deposits with banks | 148 | 595 | 844 | 1,079 | 2,582 | |||||
Investment securities, available-for-sale | 322,375 | 317,180 | 183,311 | 185,120 | 183,579 | |||||
Investment securities, held-to-maturity | - | - | 200,457 | 200,575 | 200,825 | |||||
FHLB and Federal Reserve Bank stocks, at cost | 7,457 | 3,204 | 10,959 | 7,952 | 12,225 | |||||
Paycheck Protection Program (PPP) loans, gross | 20 | 35 | 50 | 65 | 79 | |||||
Traditional loans, gross | 792,733 | 797,516 | 792,739 | 820,936 | 787,280 | |||||
Allowance for loan and lease losses | (10,913 | ) | (10,912 | ) | (10,810 | ) | (10,808 | ) | (9,607 | ) |
Net traditional loans | 781,820 | 786,604 | 781,929 | 810,128 | 777,672 | |||||
Premises and equipment, net | 33,476 | 32,289 | 30,625 | 29,448 | 28,173 | |||||
Accrued interest receivable | 7,750 | 6,940 | 7,808 | 7,807 | 7,272 | |||||
Bank-owned life insurance | 5,127 | 5,095 | 5,063 | 5,033 | 5,002 | |||||
Other assets | 10,544 | 8,734 | 8,325 | 8,607 | 6,547 | |||||
TOTAL ASSETS | $ | 1,171,846 | $ | 1,163,269 | $ | 1,231,612 | $ | 1,257,909 | $ | 1,226,690 |
LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||||
Noninterest-bearing demand deposits | $ | 485,332 | $ | 497,661 | $ | 503,819 | $ | 508,615 | $ | 511,616 |
Interest-bearing demand deposits | 54,804 | 64,606 | 62,905 | 53,514 | 48,122 | |||||
Savings and money market deposits | 100,987 | 103,118 | 102,892 | 255,655 | 169,328 | |||||
Time deposits | 294,337 | 353,405 | 272,744 | 240,047 | 241,149 | |||||
Total deposits | 935,460 | 1,018,790 | 942,360 | 1,057,831 | 970,215 | |||||
Accrued interest payable | 2,587 | 2,618 | 2,104 | 1,347 | 2,677 | |||||
Short-term borrowings | 106,267 | 13,300 | 164,613 | 79,104 | 138,077 | |||||
Long-term FHLB borrowings | 34,000 | 34,000 | 34,000 | 34,000 | 34,000 | |||||
Accounts payable and other liabilities | 4,576 | 5,395 | 3,961 | 4,659 | 2,181 | |||||
TOTAL LIABILITIES | 1,082,891 | 1,074,104 | 1,147,038 | 1,176,941 | 1,147,150 | |||||
Common stock | 43 | 43 | 43 | 43 | 43 | |||||
Additional paid-in capital | 38,748 | 38,748 | 38,778 | 38,763 | 38,748 | |||||
Retained earnings | 72,455 | 67,163 | 61,667 | 57,440 | 54,420 | |||||
Accumulated other comprehensive (loss) gain | (22,291 | ) | (16,789 | ) | (15,914 | ) | (15,278 | ) | (13,671 | ) |
TOTAL STOCKHOLDERS' EQUITY | 88,955 | 89,165 | 84,574 | 80,968 | 79,540 | |||||
TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $ | 1,171,846 | $ | 1,163,269 | $ | 1,231,612 | $ | 1,257,909 | $ | 1,226,690 |
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS (unaudited)
Three Months Ended | ||||||||||
($000s, except per share data) | 12/31/2024 | 9/30/2024 | 6/30/2024 | 3/31/2024 | 12/31/2023 | |||||
Interest and dividend income | ||||||||||
Interest and fees on traditional loans | $ | 13,615 | $ | 13,854 | $ | 13,270 | $ | 13,277 | $ | 12,425 |
Interest and fees on PPP loans | - | - | - | - | - | |||||
Investment securities | 3,297 | 3,544 | 3,721 | 3,693 | 3,704 | |||||
Dividends on bank stocks | 131 | 160 | 249 | 224 | 159 | |||||
Other | 13 | 19 | 22 | 30 | 88 | |||||
Total interest income | $ | 17,056 | $ | 17,577 | $ | 17,262 | $ | 17,224 | $ | 16,376 |
Interest expense | ||||||||||
Deposits | 5,564 | 6,312 | 5,285 | 5,833 | 6,066 | |||||
FHLB & Fed borrowings | 1,223 | 1,332 | 2,831 | 2,200 | 1,662 | |||||
Total interest expense | 6,787 | 7,644 | 8,116 | 8,033 | 7,728 | |||||
Net interest income | 10,269 | 9,933 | 9,146 | 9,191 | 8,648 | |||||
Provision for loan and lease losses | 6 | 105 | 4 | 1,203 | 203 | |||||
Net interest income after provision for loan and lease losses | 10,263 | 9,828 | 9,142 | 7,988 | 8,445 | |||||
Noninterest income | ||||||||||
Customer service and other fees | 470 | 389 | 468 | 443 | 528 | |||||
Other income | 954 | 1,138 | 738 | 616 | 617 | |||||
Gain on sale of securities | - | 858 | - | 60 | 68 | |||||
Total noninterest income | 1,424 | 2,385 | 1,206 | 1,119 | 1,213 | |||||
Noninterest expense | ||||||||||
Employee compensation and benefits | 2,611 | 2,472 | 2,514 | 2,418 | 2,046 | |||||
Occupancy | 492 | 393 | 387 | 401 | 342 | |||||
Professional fees | 309 | 122 | 75 | 495 | 383 | |||||
Other general and administrative | 1,437 | 1,423 | 1,582 | 1,656 | 1,378 | |||||
Total noninterest expense | 4,849 | 4,410 | 4,558 | 4,970 | 4,149 | |||||
Net Income Before Taxes | $ | 6,838 | $ | 7,803 | $ | 5,790 | $ | 4,137 | $ | 5,509 |
Income Tax Expense | 1,526 | 2,294 | 1,564 | 1,118 | 1,965 | |||||
Net Income | $ | 5,312 | $ | 5,509 | $ | 4,226 | $ | 3,019 | $ | 3,544 |
Income Per Share | $ | 1.24 | $ | 1.28 | $ | 0.98 | $ | 0.70 | $ | 0.82 |
Tangible Book Value Per Share | $ | 20.69 | $ | 20.74 | $ | 19.67 | $ | 18.83 | $ | 18.50 |
WA Shares outstanding | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | |||||
Pre-Tax Pre-Provision Income | $ | 6,844 | $ | 7,908 | $ | 5,794 | $ | 5,340 | $ | 5,712 |
Net Interest Margin | 3.81 | % | 3.67 | % | 3.39 | % | 3.40 | % | 3.32 | % |
Cost of Funds | 2.51 | % | 2.72 | % | 2.80 | % | 2.77 | % | 2.72 | % |
Efficiency Ratio | 41.47 | % | 38.48 | % | 44.03 | % | 48.49 | % | 42.37 | % |
Return on Average Assets | 1.82 | % | 1.84 | % | 1.36 | % | 0.97 | % | 1.18 | % |
Return on Average Equity | 23.86 | % | 25.37 | % | 20.42 | % | 15.05 | % | 19.58 | % |
Leverage Ratio | 9.5 | % | 9.1 | % | 8.2 | % | 7.7 | % | 7.6 | % |
Asset Quality: | ||||||||||
Non-performing loans to gross loans | 0.52 | % | 0.65 | % | 0.48 | % | 0.53 | % | 0.66 | % |
Non-performing assets to total assets | 0.35 | % | 0.45 | % | 0.31 | % | 0.34 | % | 0.43 | % |
Allowance for loan losses to gross traditional loans | 1.38 | % | 1.37 | % | 1.36 | % | 1.32 | % | 1.21 | % |
* Not meaningful due to the insignificant amount of non-performing loans. | ||||||||||
Criticized loans/assets: | ||||||||||
Special mention | $ | 10,730 | $ | 29,145 | $ | 25,244 | $ | 35,997 | $ | 9,688 |
Substandard: Accruing | 14,911 | 22,410 | 23,030 | 19,108 | 1,685 | |||||
Substandard: Nonaccrual | 4,142 | 5,180 | 3,784 | 4,332 | 5,223 | |||||
Doubtful | - | - | - | - | - | |||||
Total criticized loans | $ | 29,782 | $ | 56,735 | $ | 52,058 | $ | 59,437 | $ | 16,596 |
Other real estate owned | - | - | - | - | - | |||||
Investment securities | - | - | - | - | - | |||||
Total criticized assets | $ | 29,782 | $ | 56,735 | $ | 52,058 | $ | 59,437 | $ | 16,596 |
Criticized assets to total assets | 2.54 | % | 4.88 | % | 4.23 | % | 4.73 | % | 1.35 | % |
SOURCE: Solera National Bancorp, Inc.
View the original press release on ACCESS Newswire
L.Mason--AMWN