4 Ways to Financially Protect Dependents
 USMNT Coaching Search: Guardiola, Cherundolo, and Others Named as Pochettino Replacements
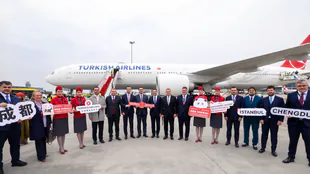 Turkish Airlines Launches Fourth Mainland China Route to Chengdu
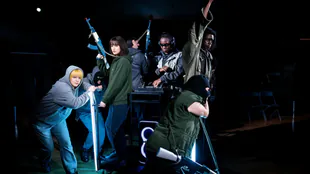 RSC’s ‘Julius Caesar’ Reimagined in Women’s Prison Setting for School Tour
 Thomson Reuters Integrates CUBE Regulatory Intelligence into CoCounsel Legal
 Does IRS Debt Expire? Clear Start Tax Explains the 10-Year Collection Statute and What Quietly Resets It
 Arrive AI Reports Third Quarter 2026 Results Highlighted by Revenue Growth and Expanded Partnerships
 Mako Mining Reports Q3 2026 Financial Results, Including Adjusted EBITDA(1) of US$30.3 million and EPS of US$0.19/share
 InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 13
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
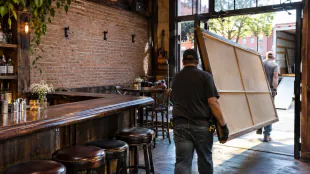 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
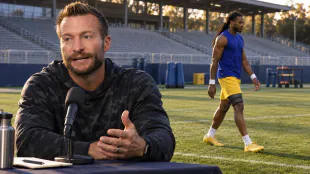 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
NEW YORK CITY, NY / ACCESS Newswire / April 15, 2025 / There are usually many financial goals to achieve, including preparing finances to help protect dependents. However, no one can know the future, and people should ensure their loved ones are protected financially in case the unexpected occurs.
Fortunately, there are several ways that can help create stability and security for dependents. Adopting some of these can help create peace of mind.
This article covers four ways to help provide financial security for dependents.
1. Get a Life Insurance Policy
Life insurance can offer a safety net to loved ones. If the policyholder passes away, their loved ones may receive a death benefit to help provide financial stability, cover daily expenses, and save for future financial goals.
The main comparison one typically must make when shopping for life insurance is term life vs whole life insurance. Term life insurance usually has reasonable premiums but typically lasts 10 to 30 years before expiring. Whole life insurance can cost more but lasts for life and can come with a cash value component that grows with each payment and earns tax-deferred interest. Policyholders can eventually tap into this via loans and withdrawals when it grows enough.
It's important to consider term and whole life insurance rates by age, as premiums can increase with age. Generally, the earlier one buys life insurance, the more competitive their premiums could be.
2. Establish an Emergency Fund
An emergency fund is a savings account that helps cover unexpected expenses or other events, such as a job loss or major car repairs. It can help pay related costs and cover living expenses without debt.
The general recommendation is to save three to six months of living expenses. Those with multiple dependents should aim for the higher end of that range, or even a little more. This is because having more dependents can increase the chance of an emergency occurring.
Saving money in a high-yield savings account may be a good idea. This helps the emergency savings grow and keep up with inflation when not in use.
3. Purchase the Right Health Insurance
Health insurance can be crucial for helping to protect dependents. It helps reduce the costs of preventative care and treatments and may help pay for prescription medications.
However, one should balance coverage needs and other preferences with premiums since these policies may be more expensive.
To do this, consider the number of dependents and each of their needs. For example, a healthy married couple with one healthy child may purchase a lower-cost Health Maintenance Organization plan that restricts them to a provider network and requires referrals to see specialists.
On the other hand, parents with a large family and dependents with chronic health issues may invest in a Paid Provider Organization plan that offers more coverage and provider flexibility.
Employers usually provides health insurance as a workplace benefit. This can be a more cost-effective way to get substantial health coverage, but employees should check that their employer-sponsored health insurance addresses all their needs.
4. Prepare an Estate Plan
An estate plan specifies one's wishes for asset distribution, medical care, and other end-of-life considerations. An estate plan can also help ensure one's assets avoid probate court and minimize potential conflicts among beneficiaries.
Here are some documents included in a typical estate plan:
Last Will and Testament: This usually specifies asset distribution wishes when one passes away. It names an executor, the person who distributes those assets, and guardians for minor children if needed.
Durable Power of Attorney: This typically names someone to help manage one's personal finances if incapacitated, such as filing tax returns or accessing bank accounts.
Healthcare Power of Attorney: This can designate someone to make medical decisions for if the estate holder becomes incapacitated.
Letter of Intent: This generally contains non-legally binding instructions and information on various matters, such as funeral wishes or estate planning decisions.
Circumstances and goals can change, so regularly reviewing an estate plan regularly is crucial to help ensure wishes are met.
Creating Financial Security for Dependents
Taking action to protect dependents financially can help guard against anything that happens in the future.
Start by establishing an emergency fund. Then, health and life insurance need to be reviewed to help protect loved ones further against the unexpected in the future. Finally, an estate plan should be created to help ensure assets are distributed and end-of-life care is handled properly.
These simple steps can help people secure their dependents' financial futures.
Content within this article is provided for general informational purposes and is not provided as tax, legal, health, or financial advice for any person or for any specific situation. Employers, employees, and other individuals should contact their own advisers about their situations. For complete details, including availability and costs of Aflac insurance, please contact your local Aflac agent.
Aflac coverage is underwritten by American Family Life Assurance Company of Columbus. In New York, Aflac coverage is underwritten by American Family Life Assurance Company of New York.
Aflac life plans - A68000 series: Term Life Policies: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York, Policies NY68200, NY68300 and NY68400. Whole Life Policies: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100. In Delaware, Policy A68100. In New York, Policy NYR68100.B60000 series: In Arkansas, Idaho, Oklahoma & Virginia, Policies: ICC18B60C10, ICC18B60100, ICC18B60200, ICC18B60300, & ICC18B60400. Not available in Delaware. Q60000 series/Whole: In Arkansas & Delaware, Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. Not available in Virginia. Q60000 series/Term: In Delaware, Policies Q60200CM. In Arkansas, Idaho, Oklahoma, Policies ICC18Q60200C, ICC18Q60300C, ICC18Q60400C. Not available in Virginia.
Coverage may not be available in all states, including but not limited to DE, ID, NJ, NM, NY, VA or VT. Benefits/premium rates may vary based on state and plan levels. Optional riders may be available at an additional cost. Policies and riders may also contain a waiting period. Refer to the exact policy and rider forms for benefit details, definitions, limitations, and exclusions.
Aflac WWHQ | 1932 Wynnton Road | Columbus, GA 31999
Aflac New York | 22 Corporate Woods Boulevard, Suite 2 | Albany, NY 12211
Z2500160 EXP 4/26
CONTACT:
Senior PR & Corporate Communications
Contact: Angie Blackmar, 706-392-2097 or [email protected]
SOURCE: Aflac
View the original press release on ACCESS Newswire
A.Rodriguezv--AMWN