Aflac: Should One Adjust One’s Life Insurance Coverage After Having a Baby?
 RSC’s ‘Julius Caesar’ Reimagined in Women’s Prison Setting for School Tour
 Thomson Reuters Integrates CUBE Regulatory Intelligence into CoCounsel Legal
 Ole Miss inquiry expands after video and monkey-noise allegations
 General Hospital actor Randall England dies at 75
 London museum removes Russell Brand hair exhibit after rape conviction
 Yella Beezy sentenced to life for arranging rapper Mo3’s murder
 Authorities to identify Montauk Mary and five other Long Island cold-case victims
 Barbie sequel negotiations stall over reported $25 million pay packages
 Bath & Body Works launches buy-one-get-one-free candle offer
 Itlu Arjuna receives U/A certificate ahead of theatrical release
 Niraj Kumar earns Los Angeles Olympic quota with 50m rifle bronze
 India extends micro-credit guarantee plan for five years
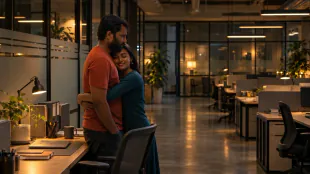 Pradeep Antony, Smeha Manimegalai portray secret spouses in Mr & Mrs Office
 Woman barred from every Greggs outlet after series of offences
 Ketchup packets link suspect to break-in at Eddie Rocket’s restaurant
 OPEC Says Oil Output Is Near Prewar Levels Despite Shipping Disruptions
 China's Singles' Day Exposes Persistent Consumer Caution
 Energy Costs Push OECD Inflation Up to 4.5%
 US Adds 165,000 Jobs as Unemployment Falls to 4.1%
 Euro-Area Inflation Reaches 4% as Energy Prices Jump
 Irish police prepare for further hoax bomb threats after hundreds of schools targeted
 RBA Inflation Target Origins: Why Australia Chose a Range Over Zero
 Sister recounts fatal machete attack as Irish murder trial continues
 HoloCoder technology promises brighter smartphone images and 3D depth data
NEW YORK CITY, NY / ACCESS Newswire / June 30, 2025 / Having a new child comes with new financial challenges. Parents must figure out working arrangements while accounting for changes in living expenses and financial goals.Inevitably, questions about life insurance arise. Parents wonder if they need to get new coverage or adjust their current policy to offer enough protection.This article explains why parents should consider adjusting their life insurance coverage after having a baby and how to do so, whether or not they currently have coverage.
Three reasons to adjust life insurance coverage after having a baby
Here are a few reasons people should change their life insurance coverage after having a new child:
1. Living expenses can increase
A living expense increase is one of the most immediate changes parents will experience. Although exact costs can vary widely based on location, the child's needs, and other factors, raising a child can be expensive. Here are some examples of expenses parents may have to cover:
Childcare, such as daycare or a babysitter
Baby food
Transportation
Healthcare
Clothing
Baby-related items, such as diapers and toys
Parents may also move into a larger home to have space for their growing families, potentially increasing expenses like:
Rent or mortgage
Utilities
Property taxes
The increase in living expenses may necessitate a larger death benefit. Increasing the death benefit allows them to provide a bigger safety net for these additional expenses. On the other hand, parents may need to find a way to lower premiums if they can't cut other costs.
2. Financial goals may shift
Having a child creates new financial goals and impacts existing ones. One of the most obvious is the child's future education.A life insurance payout can provide the surviving parent and child the funds they need to pay for college.
3. Income could change
Work arrangements and family income can change after having a child.For example, one may stay home with the child. This can reduce income if it exceeds any available parental leave, although it may also reduce childcare needs.On the other hand, the working parent may have made plans to work toward a raise or promotion, move to a job with better pay or benefits, or get a job that lets them work remotely and spend more time at home. This could offset some of the income decrease.
Either way, a change in income may cause the parents to alter their death benefit. They may shrink the death benefit since they live on less or increase it since the other parent is not accumulating savings if they stay home.
How to adjust life insurance coverage after having a baby
Having a child generally increases life insurance needs. With that in mind, here are some ways to alter one's coverage after having a baby:
1. Adjust current coverage if possible
Parents who already have life insurance can adjust their coverage in several ways, depending on the policy type:
Adjust premiums or death benefit: Some policies, like universal life insurance, let policyholders change premiums for an accompanying death benefit change. Parents who need more coverage can request it for increased premiums and potentially a new medical exam. Parents who need to reduce premiums can decrease their death benefits.
Purchase paid-up insurance: Paid-up insurance is extra coverage one pays for upfront, offering a larger death benefit with no premium increase. It also accelerates cash value growth, helping parents reach financial goals faster. This is generally only available on whole life insurance that pays dividends.
Convert to a different policy type: If a policyholder has a convertible term life policy, this lets them turn their term life insurance into whole life insurance with no medical exam for increased premiums. The policyholder gains access to lifelong coverage and cash value.
Modify investment options: Variable life insurance policyholders may alter their cash value investments to match their new risk tolerance and financial goals. For example, they may pursue more aggressive investments to potentially have more growth.
Policyholders should contact their insurer to see what options are available.
2. Look for a new policy if necessary
Whether parents don't have life insurance or now need a new policy to meet their needs, they may be wondering about term life vs. whole life insurance, along with other policy types. Here are some options to consider:
Term life insurance: This policy offers competitive premiums, but coverage is limited to 10, 20, or 30 years and there is no cash value. This policy can work best for parents who prefer to have coverage until their child reaches adulthood.
Whole life insurance: This policy is more expensive but offers lifelong coverage and cash value that grows tax-deferred with each payment. Parents can borrow or withdraw from it to help with financial goals.
Universal life insurance: This policy offers the same benefits as whole life insurance, but also allows policyholders to adjust premiums and death benefits. Policyholders can also pay premiums with cash value.
The bottom line
In general, having a child leads to additional financial responsibilities. Parents must manage new living costs, adjust or add financial goals, and potentially budget for a different income.Parents asking, "what does life insurance cover?", can rest assured that having a policy can financially safeguard their family. They just may need to adjust coverage, whether that's adding to existing coverage or applying for a new policy. Parents should speak with a financial advisor so that they can evaluate their full financial picture and plan for their life insurance needs.
Content within this article is provided for general informational purposes and is not provided as tax, legal, health, or financial advice for any person or for any specific situation. Employers, employees, and other individuals should contact their own advisers about their situations. For complete details, including availability and costs of Aflac insurance, please contact your local Aflac agent.
Aflac Coverage
Life (A68000 Series) - In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania, Texas, & Virginia, Policies: ICC1368100, ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68100-A68400. In New York, NY68100-NY68400. Term and Whole Life (B60000 Series) - In Arkansas, Idaho, Oklahoma, Pennsylvania, Texas, & Virginia, Policies: ICC18B60C10, ICC18B60100, ICC18B60200, ICC18B60300, & ICC18B60400. Group Whole Life (Q60000 Series) - In Arkansas, Delaware & Oregon, Policy Q60100M. In Idaho Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In Texas, Policy Q60100MTX. Group Term Life (Q60000 Series) - In Delaware, Policies Q60200M. In Arkansas, Idaho, Oklahoma, Oregon & Texas, Policies ICC18Q60200M, ICC18Q60300C, ICC18Q60400C.
Aflac coverage is underwritten by American Family Life Assurance Company of Columbus. In New York, coverage is underwritten by American Family Life Assurance Company of New York.
Coverage may not be available in all states, including but not limited to DE, ID, NJ, NM, NY or VA. Benefits/premium rates may vary based on state and plan levels. Optional riders may be available at an additional cost. Policies and riders may also contain a waiting period. Refer to the exact policy and rider forms for benefit details, definitions, limitations and exclusions.
Aflac WWHQ | 1932 Wynnton Road | Columbus, GA 31999.
Aflac New York | 22 Corporate Woods Boulevard, Suite 2 | Albany, NY 12211
Z2500171 EXP 3/26
CONTACT:
Senior PR & Corporate Communications
Contact: Angie Blackmar, 706-392-2097 or [email protected]
SOURCE: Aflac
View the original press release on ACCESS Newswire
X.Karnes--AMWN