Solera National Bancorp Announces Second Quarter 2025 Financial Results
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
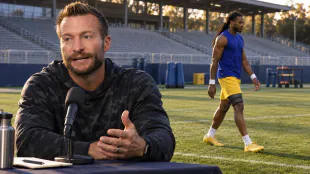 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
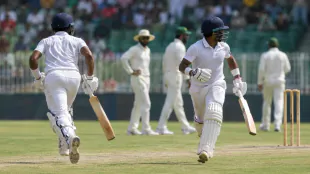 Dhananjaya de Silva guides Sri Lanka to 221-4 against Pakistan
 Delhi gold loses Rs 800 while silver falls Rs 5,000
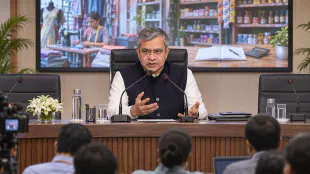
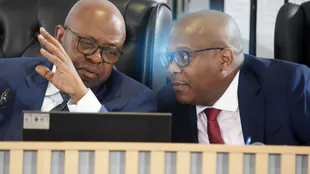 Madlanga Commission Deadline Extended to 2027 Amid Calls for Structural Justice Reform
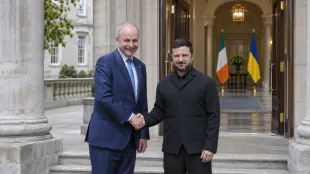 Zelenskyy arrives in Dublin for meetings on Ukraine and peace efforts
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
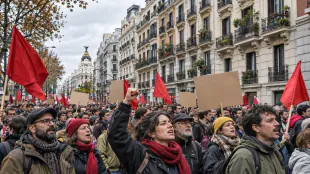
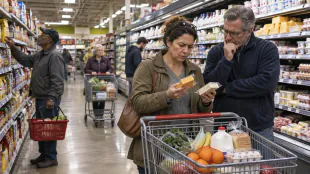 US Inflation Broadens as Fed Officials Consider Faster Rate Hikes
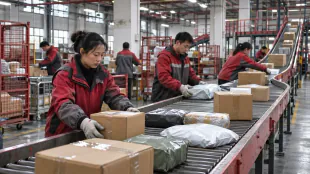
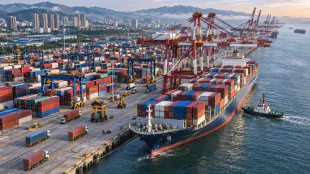 China's Trade Surplus Passes $1 Trillion as Technology Exports Surge
 Bank of England Raises Interest Rate to 4% as Energy Risks Intensify
 China's Factory Inflation Accelerates While Consumer Demand Stays Weak
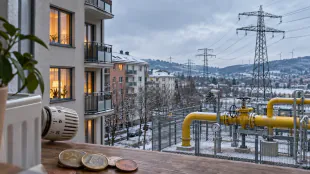
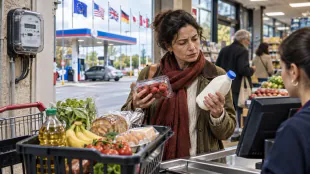 Energy Costs Push OECD Inflation Up to 4.5%
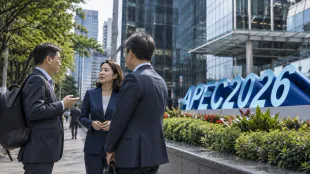 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
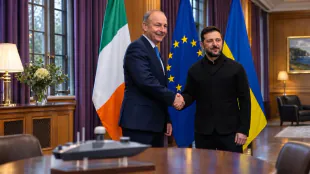 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
Net income of $5.9 million ($1.38 per share), a NEW RECORD!
Q2 2025 pre-tax and pre-provision income of $8.6 million. Another new record!
American Banker has recognized Solera National as part of the 2025 Top-Performing Banks with under $2B of assets, #3.
LAKEWOOD, CO / ACCESS Newswire / July 25, 2025 / Solera National Bancorp, Inc. (OTC:SLRK) ("Company"), the holding company for Solera National Bank ("Bank"), a business-focused bank located in the Denver metropolitan area, today reported financial results for the three months ended June 30, 2025. See highlights below.
2Q25 Financial Highlights
Net income of $5.9 million ($1.38 per share), a $1.7 million or 40% increase from Q2 2024.
Net interest income increased $726 thousand or 11% from Q2 2024.
Solera had a pre-tax and pre-provision income of $8.6 million. 48% or $2.8 million increase from Q2 2024.
Non-interest income of $3.7 million or $2.5 million, or a 205% increase from Q2 2024.
Return on assets was 2.02%, a 66 bps improvement from Q2 2024.
Return on equity was 25.92%, a 549 bps improvement from Q2 2024.
Mike Quagliano, Executive Chairman of the Board, commented: "We exist for the benefit of the shareholders, and our relentless focus on customer excellence has led to 11 years of stellar earnings, with this latest quarter being the best yet."
Steve Snailum, COO, commented: "The agility of Solera is propelling us forward in the banking landscape. The commitment of the company and the board to advancing Solera's tech stack and streamlining the operations empowers us to swiftly overcome obstacles, streamline processes, and foster client relationships in a very unique way. We are committed to quicker advancement than the competition and maintaining stronger customer bonds. This record-breaking quarter truly showcases the dedication, skill, and effort that is on display daily at Solera National Bank."
Avram Shabanyan, EVP, commented: "Strong partnerships and a disciplined focus on client success fuel Solera Bank's continued growth in the self-directed space. Our continued commitment to customer-first solutions empowers individuals to utilize their retirement funds in alternative investment opportunities confidently."
Jay Hansen, Chief Financial Officer, commented: "Our performance this quarter reflects the strength of our diversified portfolio and disciplined risk management. Our ratios continue to improve, and our team members are in a great position for long-term success."
About Solera National Bancorp, Inc.
Solera National Bancorp, Inc. was incorporated in 2006 to organize and serve as the holding company for Solera National Bank, which opened for business in September 2007. Solera National Bank is a community bank serving the needs of emerging businesses and real estate investors. At the core of Solera National Bank is welcoming, attentive, and respectful customer service, a focus on supporting a growing and diverse economy, and a passion to serve our community through service, education, and volunteerism. For more information, please visit http://www.SoleraBank.com.
This press release contains statements that may constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. The statements contained in this release, which are not historical facts and that relate to future plans or projected results of Solera National Bancorp, Inc. and its wholly-owned subsidiary, Solera National Bank, are forward-looking statements. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from those projected, anticipated, or implied. We undertake no obligation to update or revise any forward-looking statement. Readers of this release are cautioned not to put undue reliance on forward-looking statements.
Source: Solera National Bank
Contacts: Jay Hansen, CFO (303) 209-8600
FINANCIAL TABLES FOLLOW
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED BALANCE SHEET
(unaudited)
($000s) | 6/30/25 | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | |||||
ASSETS | ||||||||||
Cash and due from banks | $ | 1,969 | $ | 2,401 | $ | 1,576 | $ | 2,193 | $ | 2,241 |
Federal funds sold | - | - | 800 | 400 | - | |||||
Interest-bearing deposits with banks | 2,963 | 1,033 | 148 | 595 | 844 | |||||
Investment securities, available-for-sale | 422,112 | 290,397 | 322,375 | 317,180 | 183,311 | |||||
Investment securities, held-to-maturity | - | - | - | - | 200,457 | |||||
FHLB and Federal Reserve Bank stocks, at cost | 5,004 | 5,525 | 7,457 | 3,204 | 10,959 | |||||
Paycheck Protection Program (PPP) loans, gross | - | 5 | 20 | 35 | 50 | |||||
Traditional loans, gross | 754,518 | 766,687 | 792,753 | 797,516 | 792,739 | |||||
Allowance for loan and lease losses | (11,219 | ) | (10,914 | ) | (10,913 | ) | (10,912 | ) | (10,810 | ) |
Net traditional loans | 743,299 | 755,773 | 781,840 | 786,604 | 781,929 | |||||
Premises and equipment, net | 35,128 | 33,236 | 33,476 | 32,289 | 30,625 | |||||
Accrued interest receivable | 10,244 | 7,153 | 7,750 | 6,940 | 7,808 | |||||
Bank-owned life insurance | 5,190 | 5,159 | 5,127 | 5,095 | 5,063 | |||||
Other assets | 13,433 | 11,103 | 8,820 | 8,734 | 8,325 | |||||
TOTAL ASSETS | $ | 1,239,342 | $ | 1,111,785 | $ | 1,169,389 | $ | 1,163,269 | $ | 1,231,612 |
LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||||
Noninterest-bearing demand deposits | $ | 463,861 | $ | 466,455 | $ | 484,604 | $ | 497,661 | $ | 503,819 |
Interest-bearing demand deposits | 65,761 | 60,507 | 54,734 | 64,606 | 62,905 | |||||
Savings and money market deposits | 138,964 | 104,560 | 100,987 | 103,118 | 102,892 | |||||
Time deposits | 436,547 | 287,378 | 294,338 | 353,405 | 272,744 | |||||
Total deposits | 1,105,133 | 918,900 | 934,663 | 1,018,790 | 942,360 | |||||
Accrued interest payable | 2,528 | 1,808 | 2,587 | 2,618 | 2,104 | |||||
Short-term borrowings | (1 | ) | 60,191 | 104,607 | 13,300 | 164,613 | ||||
Long-term FHLB borrowings | 34,000 | 34,000 | 34,000 | 34,000 | 34,000 | |||||
Accounts payable and other liabilities | 5,337 | 6,087 | 4,576 | 5,395 | 3,961 | |||||
TOTAL LIABILITIES | 1,146,997 | 1,020,987 | 1,080,434 | 1,074,104 | 1,147,038 | |||||
Common stock | 43 | 43 | 43 | 43 | 43 | |||||
Additional paid-in capital | 38,778 | 38,763 | 38,748 | 38,748 | 38,778 | |||||
Retained earnings | 83,008 | 77,076 | 72,455 | 67,163 | 61,667 | |||||
Accumulated other comprehensive (loss) gain | (29,484 | ) | (25,084 | ) | (22,291 | ) | (16,789 | ) | (15,914 | ) |
TOTAL STOCKHOLDERS' EQUITY | 92,345 | 90,798 | 88,955 | 89,165 | 84,574 | |||||
TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $ | 1,239,342 | $ | 1,111,785 | $ | 1,169,389 | $ | 1,163,269 | $ | 1,231,612 |
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS (unaudited)
Three Months Ended | |||||||||||||||||||
($000s, except per share data) | 6/30/25 | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | ||||||||||||||
Interest and dividend income | |||||||||||||||||||
Interest and fees on traditional loans | $ | 12,791 | $ | 13,101 | $ | 13,615 | $ | 13,854 | $ | 13,270 | |||||||||
Investment securities | 4,831 | 3,490 | 3,297 | 3,544 | 3,721 | ||||||||||||||
Dividends on bank stocks | 180 | 175 | 131 | 160 | 249 | ||||||||||||||
Other | 21 | 49 | 13 | 19 | 22 | ||||||||||||||
Total interest income | $ | 17,823 | $ | 16,815 | $ | 17,056 | $ | 17,577 | $ | 17,262 | |||||||||
Interest expense | |||||||||||||||||||
Deposits | 6,235 | 4,959 | 5,564 | 6,312 | 5,285 | ||||||||||||||
FHLB & Fed borrowings | 1,410 | 1,550 | 1,223 | 1,332 | 2,831 | ||||||||||||||
Total interest expense | 7,645 | 6,509 | 6,787 | 7,644 | 8,116 | ||||||||||||||
Net interest income | 10,178 | 10,306 | 10,269 | 9,933 | 9,146 | ||||||||||||||
Provision for loan and lease losses | 310 | 7 | 6 | 105 | 4 | ||||||||||||||
Net interest income after provision for loan and lease losses | 9,868 | 10,299 | 10,263 | 9,828 | 9,142 | ||||||||||||||
Noninterest income | |||||||||||||||||||
Customer service and other fees | 291 | 300 | 470 | 389 | 468 | ||||||||||||||
Other income | 677 | 807 | 954 | 1,138 | 738 | ||||||||||||||
Gain on sale of securities | 2,709 | - | - | 858 | - | ||||||||||||||
Total noninterest income | 3,677 | 1,107 | 1,424 | 2,385 | 1,206 | ||||||||||||||
Noninterest expense | |||||||||||||||||||
Employee compensation and benefits | 2,827 | 2,656 | 2,611 | 2,472 | 2,514 | ||||||||||||||
Occupancy | 553 | 448 | 492 | 393 | 387 | ||||||||||||||
Professional fees | 330 | 259 | 309 | 122 | 75 | ||||||||||||||
Other general and administrative | 1,593 | 1,694 | 1,437 | 1,423 | 1,582 | ||||||||||||||
Total noninterest expense | 5,303 | 5,057 | 4,849 | 4,410 | 4,558 | ||||||||||||||
Net Income Before Taxes | $ | 8,242 | $ | 6,349 | $ | 6,838 | $ | 7,803 | $ | 5,790 | |||||||||
Income Tax Expense | 2,309 | 1,711 | 1,526 | 2,294 | 1,564 | ||||||||||||||
Net Income | $ | 5,933 | $ | 4,638 | $ | 5,312 | $ | 5,509 | $ | 4,226 | |||||||||
Income Per Share | $ | 1.38 | $ | 1.08 | $ | 1.24 | $ | 1.28 | $ | 0.98 | |||||||||
Tangible Book Value Per Share | $ | 21.48 | $ | 21.12 | $ | 20.69 | $ | 20.74 | $ | 19.67 | |||||||||
WA Shares outstanding | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | ||||||||||||||
Pre-Tax Pre-Provision Income | $ | 8,552 | $ | 6,356 | $ | 6,844 | $ | 7,908 | $ | 5,794 | |||||||||
Net Interest Margin | 3.56 | % | 3.93 | % | 3.81 | % | 3.67 | % | 3.39 | % | |||||||||
Cost of Funds | 2.66 | % | 2.49 | % | 2.51 | % | 2.72 | % | 2.80 | % | |||||||||
Efficiency Ratio | 47.58 | % | 44.31 | % | 41.47 | % | 38.48 | % | 44.03 | % | |||||||||
Return on Average Assets | 2.02 | % | 1.63 | % | 1.82 | % | 1.84 | % | 1.36 | % | |||||||||
Return on Average Equity | 25.92 | % | 20.64 | % | 23.86 | % | 25.37 | % | 20.42 | % | |||||||||
Leverage Ratio | 9.8 | % | 10.4 | % | 9.5 | % | 9.1 | % | 8.2 | % | |||||||||
Asset Quality: | |||||||||||||||||||
Non-performing loans to gross loans | 0.60 | % | 0.42 | % | 0.52 | % | 0.65 | % | 0.48 | % | |||||||||
Non-performing assets to total assets | 0.37 | % | 0.29 | % | 0.35 | % | 0.45 | % | 0.31 | % | |||||||||
Allowance for loan losses to gross traditional loans | 1.49 | % | 1.42 | % | 1.38 | % | 1.37 | % | 1.36 | % | |||||||||
* Not meaningful due to the insignificant amount of non-performing loans. | |||||||||||||||||||
Criticized loans/assets: | |||||||||||||||||||
Special mention | $ | 2,842 | $ | 11,103 | $ | 10,730 | $ | 29,145 | $ | 25,244 | |||||||||
Substandard: Accruing | 39,971 | 19,641 | 14,911 | 22,410 | 23,030 | ||||||||||||||
Substandard: Nonaccrual | 4,526 | 3,251 | 4,142 | 5,180 | 3,784 | ||||||||||||||
Doubtful | - | - | - | - | - | ||||||||||||||
Total criticized loans | $ | 47,339 | $ | 33,995 | $ | 29,782 | $ | 56,735 | $ | 52,058 | |||||||||
Other real estate owned | - | - | - | - | - | ||||||||||||||
Investment securities | - | - | - | - | - | ||||||||||||||
Total criticized assets | $ | 47,339 | $ | 33,995 | $ | 29,782 | $ | 56,735 | $ | 52,058 | |||||||||
Criticized assets to total assets | 3.82 | % | 3.06 | % | 2.55 | % | 4.88 | % | 4.23 | % | |||||||||
SOURCE: Solera National Bancorp, Inc.
View the original press release on ACCESS Newswire
F.Bennett--AMWN