How the Terms of SMX's $111 Million Capital Facility Shape the Valuation Discussion
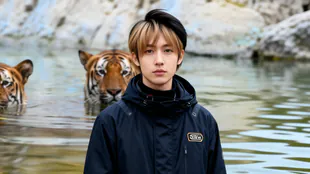 Search Underway for 'Dooars Rani' Tigress After Second Escape from Buxa Tiger Reserve
 The Dilemma of Recording Live Music: Preserving Memories vs. Being Present
 AmeriLife Welcomes Finance Veteran Richard Dziadzio as Chief Financial Officer; Names Jim Quinn President & Chief Transformation Officer
 Fulcrum Metals PLC Announces New Critical Mineral Recoveries Expand Potential
 Guardian Metal Resources PLC Announces Proposed Spin-Out of Non-Tungsten Projects
 THIEAUDIO Introduces Clairvoyance MKII: The Evolution of a Signature Sound
 BlackBerry to Participate in Upcoming Investor Conferences
Irving Resources Reports on Drilling in Yamagano Mining Right at the Yamagano Joint Venture, Kyushu, Japan
 XCF Global Hosts USDA at New Rise Renewables Reno as Facility Surpasses 4.4 Million Gallons Since Restart
 Patriot Software Adds Performance Reviews to Patriot HR
 Healixa's FrostPulse(TM) Technology Solves a Major Roadblock to Data Center Growth: Cooling Without the Water Burden
NuRAN Wireless Board Approves Growth Strategy to Scale Recurring Revenue from 5,000+ Contracted Towers
PPX Mining Reports Callanquitas Operating Results for the First Nine Months of 2026
 Valion Bio Reinforces Commitment to American Troops; Discusses Entolimod with Attendees at RW Baird's National Security Conference
 Thukukile Zuma Resigns from ANC Johannesburg Leadership Amid Disciplinary Dispute
 CM Mohan Yadav Meets Bohra Spiritual Leader to Discuss Simhastha 2028 and Development
 Eli Crane Defeats Jonathan Nez in Tight Arizona Congressional Race
NEW YORK, NY / ACCESS Newswire / December 26, 2025 / Public-market capital raises are often interpreted through a narrow lens, especially in the small-cap universe. They are frequently treated as retroactive signals, with the assumption that issuing capital below the prevailing share price creates a gravitational pull back toward that level.
That framework can be relevant for companies that rely on serial financing to sustain operations. It is far less applicable to businesses with constrained share counts that are transitioning toward fully capitalized operating platforms.
That distinction is particularly relevant for SMX (NASDAQ:SMX). With the shares trading near $140 after rising more than 2,200% from levels seen just one quarter earlier, the conversation has shifted from momentum to structure, and from price action to how the company is positioned to support its next phase of execution.
What the Market Is Discounting
Viewed in isolation, SMX could be interpreted as fully valued for a company still in the early stages of revenue development. That interpretation, however, places too much weight on surface-level pricing and too little on what the market is beginning to account for beneath it. With approximately 1.05 million shares outstanding, a share price near $140 implies a market cap of roughly $147 million.
While that valuation is notable relative to SMX's recent trading history, it does not fully reflect the structural shift now taking place. The more impactful variable is not where the stock has traded, but how exposure to financing risk is changing. As that risk profile evolves, the framework used to assess valuation tends to evolve with it.
In December, SMX disclosed an institutional capital framework totaling more than $111 million, comprising discounted convertible promissory notes and a discretionary equity line of up to $100 million. This structure represents available capacity rather than a contingent or theoretical raise, without the features commonly associated with toxic financing. With it in place, the company is no longer reliant on piecemeal or opportunistic financing to advance its operating objectives. Access to scale capital has already been secured.
That distinction is significant. Capital structure often shapes how durability is perceived in public markets. Companies operating without clear funding visibility are frequently valued with caution, independent of the strength of their underlying technology or strategy. By contrast, companies with established access to execution capital tend to be evaluated across longer operating horizons, allowing market attention to shift toward platform development and long-term positioning.
Why Raise Price and Share Price Are Not the Same Signal
That dynamic is particularly relevant for SMX. Despite its recent share-price performance, the company is still often assessed as though access to capital remains uncertain, a framework more commonly applied to early-stage or undercapitalized platforms. That mismatch between perception and structure continues to shape how valuation is discussed.
The more instructive question is not whether capital could be raised at or near current trading levels, but how the market would recalibrate its assessment once a sizable raise is completed, even if executed at a discount to the prevailing price. When evaluated in context, such a scenario does not inherently translate into share-price pressure.
Institutional commitment levels reflect negotiated economics tied to scale, time horizon, and risk allocation. Those terms are specific to the transaction. Public-market pricing, by contrast, is driven by how risk is perceived after the balance sheet has been strengthened. Once that risk profile shifts, valuation frameworks tend to adjust accordingly.
Post-Raise Structure and Share Scarcity
For SMX, accessing capital at scale would meaningfully recalibrate how risk is assessed. Even under conservative pricing scenarios, a $100 million raise would be expected to result in total shares outstanding in a range of approximately 2.0 to 2.3 million. Relative to public-market norms, that remains a constrained share base.
Under that structure, dilution is finite and measurable, while uncertainty around future capital needs is substantially reduced. The market response to that shift tends to be less about transaction mechanics and more about what the company can now execute with confidence.
Before capital of this size is secured, valuation often reflects concerns that are tangential to the technology itself, such as operating runway, timing pressure, and the likelihood of returning to the market. Once a properly structured raise is completed, those factors lose prominence. Operating horizons extend from near-term to multi-year. Management gains greater discretion over sequencing and prioritization. Strategic initiatives can be advanced proactively rather than reactively.
In public markets, this transition frequently provides foundational support for valuation, as focus shifts from balance-sheet durability to long-term platform development.
Why Financing Quality Matters
How capital is structured often proves just as consequential as how much is raised. Financing arrangements built for long-term alignment, particularly those that do not include warrants or price-reset mechanisms, behave very differently in the market than structures that introduce ongoing supply pressure. In the latter case, share performance can become more influenced by capital mechanics than by business progress.
That is not the approach reflected in SMX's framework.
When capital is introduced through a clean, institutional structure and subsequently absorbed, the capitalization profile tends to normalize. Incentives tied to continuous selling pressure are removed, and the market's focus begins to shift. Valuation discussions move away from questions of funding durability and toward assessments of scale, positioning, and long-term platform relevance.
As financing considerations recede, the operating context becomes increasingly important. SMX's growing set of partnerships across precious metals, plastics, hardware, and broader commodities, including work alongside Singapore's A*STAR and Dubai's DMCC, positions the company within globally relevant supply-chain and materials ecosystems.
Viewed through that lens, recent share-price levels are less indicative of limitation and more reflective of transition. With post-raise share counts, if accessed and considering the tens if not hundreds of million added, still expected to remain in the low two-million range, valuation comparisons begin to align more closely with other infrastructure-oriented platforms that are fully funded and globally applicable.
Crucially, those valuation frameworks do not depend on near-term revenue inflection. They are grounded in a different set of inputs: reduced financing risk, extended operating runway, and the preservation of share scarcity.
How Re-Ratings Typically Occur
In comparable cases across industrial and infrastructure sectors, valuation expansion has tended to follow the removal of existential risk rather than near-term revenue inflection. Capital security came first. Market re-rating followed.
The same framework applies here. The price at which capital commits reflects where institutional investors are willing to deploy size under negotiated terms. Public-market pricing reflects something different: where perceived risk clears once that capital is secured. When risk declines and share scarcity remains intact, markets naturally reassess valuation ranges.
If SMX elects to access its facility in 2026, it would do so within a clean institutional structure, without warrant overhangs and without the features commonly associated with toxic financing. That distinction matters. It means capital can be added without introducing persistent selling pressure or structural supply distortions.
In practical terms, raising up to $100 million while maintaining a post-transaction share count of roughly 2 million preserves scarcity and materially strengthens the balance sheet. With financing risk reduced and no structural overhang to absorb, supply dynamics tighten. From there, valuation tends to become increasingly influenced by demand and execution rather than capital uncertainty.
That is how capital formation can shift a company's reference point forward rather than backward.
About SMX
As global businesses face new and complex challenges relating to carbon neutrality and meeting new governmental and regional regulations and standards, SMX is able to offer players along the value chain access to its marking, tracking, measuring and digital platform technology to transition more successfully to a low-carbon economy.
Forward-Looking Statements
This information contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933, and Section 21E of the Securities Exchange Act of 1934. These statements are based on current expectations, estimates, forecasts, and assumptions regarding future events involving SMX (NASDAQ: SMX), its technologies, its partnership activities, and its development of molecular marking systems for recycled PET and other materials. Forward-looking statements are not historical facts. They involve risks, uncertainties, and factors that may cause actual results to differ materially from those expressed or implied.
Forward looking statements in this editorial include, but are not limited to, expectations regarding the integration of SMX's molecular markers into U.S. recycling markets; the potential for FDA-compliant markers to enable recycled PET to enter food-grade and other regulated applications; the scalability of SMX solutions across diverse global supply chains; anticipated adoption of identity-based verification systems by manufacturers, recyclers, regulators, or brand owners; the potential economic impact of turning recycled plastics into tradeable or monetizable assets; the expected performance of SMX's Plastic Cycle Token or other digital verification instruments; and the belief that molecular-level authentication may influence pricing, compliance, sustainability reporting, or financial strategies used within the plastics sector.
These forward-looking statements are also subject to assumptions regarding regulatory developments, market demand for authenticated recycled content, the pace of corporate adoption of traceability technology, global economic conditions, supply chain constraints, evolving environmental policies, and general industry behavior relating to sustainability commitments and recycling mandates. Risks include, but are not limited to, changes in FDA or international regulatory standards; technological challenges in large-scale deployment of molecular markers; competitive innovations from other companies; operational disruptions in recycling or plastics manufacturing; fluctuations in pricing for virgin or recycled plastics; and the broader economic conditions that influence capital investment and industrial activity.
Detailed risk factors are described in SMX's filings with the Securities and Exchange Commission, including the Annual Report on Form 10-K and subsequent Quarterly Reports on Form 10-Q. Readers are cautioned not to place undue reliance on forward-looking statements. These statements speak only as of the date of publication. SMX undertakes no obligation to update or revise forward-looking statements to reflect subsequent events, changes in circumstances, or new information, except as required by applicable law.
EMAIL: [email protected]
SOURCE: SMX (Security Matters) Public Limited
View the original press release on ACCESS Newswire
Ch.Kahalev--AMWN