Cashmere Valley Bank Reports Record Earnings of $29.2 Million and Increases Semi-Annual Dividend
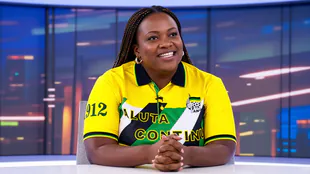 Thukukile Zuma Resigns from ANC Johannesburg Leadership Amid Disciplinary Dispute
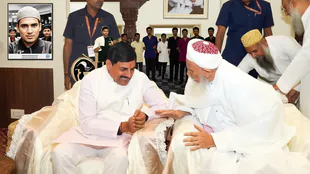 CM Mohan Yadav Meets Bohra Spiritual Leader to Discuss Simhastha 2028 and Development
 Eli Crane Defeats Jonathan Nez in Tight Arizona Congressional Race
 Sherilyn Smith Encourages Women to Embrace Scars as Symbols of Resilience
 Belgium Signs Contract for 20 Rheinmetall Skyranger Air Defence Systems
 NextBoat Inc. to Announce Third Quarter 2026 Financial and Operating Results on Monday, November 16, 2026
 Retired Army Officer Earns Two Degrees While Navigating Family Health Challenges
 An Investigational Drug to Tackle Measles Outbreaks
 First Breach Plans to Integrate Onboard AI Computing into CQS and LRS Drone Platforms
 ACCESS Newswire Reports Third Quarter 2026 Results
 ClearSign Receives Order for "M1" Series Burner from Tulsa Heaters Midstream (THM)
 Innovative Menopause Medicine from JASTLabs Advances Patent Protection Internationally
 Jerash Holdings Reports Fiscal 2027 Second Quarter Financial Results
 Peraso to Showcase DUNE 60 GHz Wireless Platform at Africa Tech Festival 2026
 ByNext Joins the Bilt Neighborhood: Reaching More Customers by Integrating Its Technology with Bilt Neighborhood OS
 Cardiff Lexington To Report Third Quarter 2026 Financial Results and Host Conference Call on Monday, November 16, 2026
 Securitas Healthcare Introduces a New Era of RTLS Built for the Future of Healthcare Operations
 Allstar Health Brands Confirms MLS NEXT Expansion Bid to Anchor a Permanent Training Structure and a Professional Pathway
 Critical Elements' 10,000-Meter Summer Drill Program at Rose West Continues to Deliver Positive Results
InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 10
 Spectrocell Strengthens Product Discovery and Customer Engagement with Bioz Badges
Apex Extends Trinity Zone in West Step-out Drilling With 2.52% REO Over 223.3 m and 2.49% REO Over 123.3 m at Rift
 Zomedica Announces "Third Friday at Four" Webinar on November 20, 2026: The People Behind Zomedica - Seven Guiding Principles in Action, and Q3 Financial Results
 Geek+ Unveils 24/7 Warehouse Autonomy Plan to Advance Self-Optimizing, Around-the-Clock Operation
China Explores a New Pathway for Medical AI: Bridging R&D Innovation and Clinical Adoption
CASHMERE, WA / ACCESS Newswire / January 20, 2026 / Cashmere Valley Bank (OTCQX:CSHX) ("Bank") announced annual earnings of $29.2 million for the year ended December 31, 2025. Diluted earnings per share was $7.46, which was an increase of $0.22 from the prior year.
On January 20, 2026, the Bank's Board of Directors declared a semi-annual dividend payment of $1.00 per share to shareholders of record on January 30, 2026. The dividend will be paid on February 9, 2026. The dividend rate is an increase of $0.05 per share from the dividend paid August 11, 2025.
"We are extremely pleased with our earnings," said Greg Oakes, President and CEO. "Furthermore, our stock repurchase that was completed early in 2026 provided liquidity to shareholders looking to reduce their positions, and also rewarded shareholders by lowering the amount of shares outstanding. Looking forward, our indirect lending portfolio and lower interest rate environment are challenges that we will have to navigate."
2025 Highlights
The Bank reported the following financial highlights for the period ending December 31, 2025 as compared to December 31, 2024:
Cashmere Valley Bank was ranked in the top ten nationally in its asset size based on capital, earnings and asset quality metrics by Bank Director magazine.
Net income increased to $29.2 million for the year ended December 31, 2025, which was an increase of $1.1 million.
Fourth quarter net income totaled $7.1 million, or $1.81 per diluted share.
Diluted earnings per share increased 3.0% from the prior year to $7.46 per share as compared to $7.24 in 2024.
Return on equity decreased from 12.93% in fiscal 2024 to 11.76% for fiscal 2025. The decrease in return on equity was due to an increasing capital base from earnings and a reduction in unrealized losses on available for sale securities.
Return on assets decreased 2 basis points to 1.34%. While earnings held steady, asset growth occurred during the second half of the year resulting in the reduction.
The Bank's net interest margin increased seven basis points to 3.21% in 2025 as compared to 3.14% a year ago. Yield on earning assets increased six basis points while cost of funds fell by one basis point.
The efficiency ratio remained strong and decreased from 57.0% to 56.6% in spite of escalating personnel costs.
Cash, Cash Equivalents and Restricted Cash
Cash balances increased $31.0 million to $250.9 million at December 31, 2025 from $219.9 million as of December 31, 2024. Deposit balances stabilized in the early part of the year, then grew in the latter half of the year. There were also a number of large loan payoffs throughout the year. Proceeds from deposit growth and reductions in the loan portfolio were utilized to increase on-hand liquidity as well as purchase Available for Sale (AFS) securities.
Investments
The fair value of the AFS securities portfolio increased $145.6 million due to Security purchases in combination with a $23.8 million reduction in unrealized losses on available for sale securities. The book value less allowance for credit losses of HTM securities totaled $123.4 million at December 31, 2025. This represented a decrease of $6.8 million from December 31, 2024.
Available for sale securities totaling $33.8 million were sold during 2025, resulting in a gain of approximately $130,000. There were no security sales in 2024.
Security purchases totaling $267.5 million were made during 2025. The bulk of purchases were made in Collateralized Mortgage Obligation (CMO's), whose purchases totaled $182.5 million in 2025.
Unrealized losses on available for sale securities decreased $23.8 million during 2025 and totaled $39.6 million as of December 31, 2025.
Loans and Credit Quality
At December 31, 2025 gross loans totaled $951.9 million, representing a decrease of $10.5 million, or 1.1%, from December 31, 2024. Significant loan payoffs adversely affected loan totals. Larger loan payoff activity occurred primarily in the multifamily and municipal loan portfolios.
The allowance for credit losses on loans (ACL) was 1.20%, or $11.4 million, as of December 31, 2025 as compared to 1.32%, or $12.7 million, as of December 31, 2024.
The Bank recorded provision expense of $3.0 million in 2025 as compared to $2.0 million in 2024. The decrease in provision expense was largely due to an increase in charged-off loans. Charged-off loans totaled $4.4 million in 2025 as compared to $3.5 million in 2024. The majority of charged-off loans came from the equipment finance division which continues to see charge-offs related to the trucking industry.
Non-performing loan totals increased from the prior year. As of December 31, 2025, non-performing loans totaled $4.4 million, or 0.46%, of gross loans as compared to $3.3 million, which represented 0.34% of gross loans as of December 31, 2024.
Deposits
Total deposits were $1.9 billion as of December 31, 2025, which represented an increase of $62.8 million, or 3.4%, from December 31, 2024. Non-interest bearing deposits totaled $403.5 million, which represented 21.2% of total deposits. Certificate of deposit balances increased significantly from $502.5 million at December 31, 2024 to $579.9 million as of December 31, 2025. The majority of the increase in CD balances was represented by CD's with terms less than one year.
Capital
As of December 31, 2025, shareholders' equity increased $39.9 million and totaled $271.3 million, which represented a 17.2% increase from $231.4 million at December 31, 2024. Equity increased due to an improvement in unrealized losses on available for sale securities and swaps totaling $16.9 million in combination with annual earnings less dividends paid. At period end, the Bank's GAAP capital to assets ratio was 11.99% as compared to 10.94% one year ago.
Earnings
Net Interest Income
Net interest income totaled $68.3 million for the year ended December 31, 2025 as compared to $63.2 million for the year ended December 31, 2024. The increase of $5.1 million represented an increase of 8.1%.
Interest income increased $6.4 million, while interest expense increased by $1.3 million. Interest income was increased by $595,000 due to interest paid on overpayment of taxes related to the Employee Retention Tax Credit. Additionally, income from available for sale and held to maturity income increased $3.8 million, fed funds and deposits with other financial institutions increased $1.3 million and income from loans increased $764,000 despite decreasing loan balances.
The average yield on earning assets improved from 4.66% to 4.72%, while the Bank's cost of funds decreased from 1.68% to 1.67%.
Non-Interest Income
Non-interest income increased $1.5 million, or 7.3%, as compared to 2024. Insurance commission and fees increased $859,000 million in 2025, and Bank Owned Life Insurance income increased $396,000 due primarily to a death benefit payment along with higher returns on existing policies. Gains on sales of available for sale securities improved by $130,000 in 2025 as compared to 2024 when no securities were sold.
Non-Interest Expense
Non-interest expense increased $3.4 million, or 7.1%. Salaries and benefits increased $2.7 million. The increase in salaries and benefits was largely related to significant investments in personnel late in 2024 that were not reflected in expense until 2025, in combination with a significant increase in health insurance expense. Data processing costs increased $733,000, or 11.6%.
Federal income tax expense increased $1.1 million from the prior year to $6.9 million. The Bank's effective tax rate was 19.0% for 2025 as compared to 17.1% in 2024.
About Cashmere Valley Bank
Cashmere Valley Bank was established September 24, 1932 and now has 11 retail offices in Chelan, Douglas, Kittitas and Yakima Counties and a municipal lending office in King County. The Bank provides business and personal banking, commercial lending, insurance services through its subsidiary Mitchell, Reed & Schmitten Insurance, investment services, mortgage services, equipment lease financing, auto and marine dealer financing and municipal lending. The success of Cashmere Valley Bank is the result of maintaining a high level of personal service and controlling expenses so our fees and charges offer our customers the best value available. We remain committed to those principles that we feel are best summarized as, "the little Bank with the big circle of friends."
Forward-Looking Statements
This release may contain certain forward-looking statements that are based on management's current expectations regarding economic, legislative, and regulatory issues that may impact the Bank's earnings in future periods. Forward-looking statements can be identified by the fact that they do not relate strictly to historical or current facts. They often include the words "believe," "expect," "intend," "anticipate," "estimate," "will," "would," "should," "could" or "may." Factors that could cause future results to vary materially from current management expectations include, but are not limited to, general economic conditions, economic uncertainty in the United States and abroad, changes in interest rates, deposit flows, real estate values, costs or effects of acquisitions, competition, changes in accounting principles, policies or guidelines, legislation or regulation, and other economic, competitive, governmental, regulatory and technological factors affecting the Bank's operations. The Bank undertakes no obligation to release publicly the result of any revisions to these forward-looking statements that may be made to reflect events or circumstances after the date of this press release or to reflect the occurrence of unanticipated events.
MEDIA CONTACT:
Greg Oakes, CEO, (509) 782-2092
or
Mike Lundstrom, CFO, (509) 782-5495
Consolidated Balance Sheets (UNAUDITED)
(Dollars in Thousands) | ||||||
Cashmere Valley Bank and Subsidiary | ||||||
December 31, 2025 | September 30, 2025 | December 31, 2024 | ||||
Assets | ||||||
Cash and Cash Equivalent: | ||||||
Cash & due from banks | $ | 31,097 | $ | 26,245 | $ | 27,642 |
Interest bearing deposits | 216,434 | 239,553 | 188,370 | |||
Fed funds sold | 3,389 | 4,212 | 3,909 | |||
Total Cash and Cash Equivalent | 250,920 | 270,010 | 219,921 | |||
Securities available for sale | 862,103 | 816,440 | 716,508 | |||
Securities held to maturity, net of allowance for credit losses of $13, $14 and $16, respectively | 123,412 | 124,814 | 130,254 | |||
Federal Home Loan Bank stock, at cost | 5,008 | 5,053 | 2,846 | |||
Loans held for sale | 1,135 | 5 | 4 | |||
Loans | 951,869 | 964,663 | 962,369 | |||
Allowance for credit losses | (11,399 | ) | (12,136 | ) | (12,748 | ) |
Net loans | 940,470 | 952,527 | 949,621 | |||
Premises and equipment | 19,235 | 19,430 | 19,472 | |||
Accrued interest receivable | 8,868 | 9,313 | 8,952 | |||
Other real estate and foreclosed assets | 148 | 97 | 97 | |||
Bank Owned Life Insurance | 27,343 | 27,101 | 27,647 | |||
Goodwill | 7,579 | 7,579 | 7,579 | |||
Intangibles, net | 2,233 | 2,427 | 2,749 | |||
Mortgage servicing rights | 2,382 | 2,375 | 2,441 | |||
Net deferred tax assets | 13,137 | 14,304 | 18,037 | |||
Other assets | 9,339 | 9,608 | 15,435 | |||
Total assets | $ | 2,273,312 | $ | 2,261,083 | $ | 2,121,563 |
Liabilities and Shareholders' Equity | ||||||
Liabilities | ||||||
Deposits: | ||||||
Non-interest bearing demand | $ | 403,456 | $ | 415,957 | $ | 395,327 |
Savings and interest-bearing demand | 917,464 | 912,712 | 940,084 | |||
Time | 579,856 | 568,657 | 502,542 | |||
Total deposits | 1,900,776 | 1,897,326 | 1,837,953 | |||
Accrued interest payable | 3,073 | 3,138 | 2,842 | |||
Borrowings | 83,000 | 84,000 | 36,000 | |||
Other liabilities | 13,992 | 14,393 | 12,601 | |||
Total liabilities | 2,000,841 | 1,998,857 | 1,889,396 | |||
Shareholders' Equity | ||||||
Common stock (no par value); authorized 10,000,000 shares; | ||||||
Issued and outstanding: 12/31/2025 -- 3,907,525 ; 9/30/2025 -- 3,906,693 ; 12/31/2024 -- 3,891,000 | -- | -- | -- | |||
Additional paid-in capital | 6,248 | 6,191 | 5,229 | |||
Treasury stock | (16,784 | ) | (16,784 | ) | (16,784 | ) |
Retained Earnings | 323,653 | 316,563 | 301,636 | |||
Other comprehensive income | (41,823 | ) | (44,633 | ) | (58,674 | ) |
Total Cashmere Valley Bank shareholders' equity | 271,294 | 261,337 | 231,407 | |||
Noncontrolling interest | 1,177 | 889 | 760 | |||
Total shareholders' equity | 272,471 | 262,226 | 232,167 | |||
Total liabilities and shareholders' equity | $ | 2,273,312 | $ | 2,261,083 | $ | 2,121,563 |
Year-to-Date Consolidated Statements of Income (UNAUDITED)
(Dollars in Thousands) | ||||||
Cashmere Valley Bank & Subsidiary | ||||||
For the twelve months ended, | ||||||
December 31, 2025 | December 31, 2024 | |||||
Interest Income | ||||||
Loans and leases | $ | 53,361 | $ | 52,597 | ||
Fed funds sold and deposits at other financial institutions | 8,249 | 6,986 | ||||
Securities available for sale: | ||||||
Taxable | 33,478 | 29,797 | ||||
Tax-exempt | 1,614 | 1,313 | ||||
Securities held to maturity: | ||||||
Taxable | 2,978 | 3,094 | ||||
Tax-exempt | 100 | 142 | ||||
Other interest income | 595 | -- | ||||
Total interest income | 100,375 | 93,929 | ||||
Interest Expense | ||||||
Deposits | 29,254 | 28,524 | ||||
Borrowings | 2,840 | 2,226 | ||||
Total interest expense | 32,094 | 30,750 | ||||
Net interest income | 68,281 | 63,179 | ||||
Provision for Credit Losses | 2,974 | 1,971 | ||||
Net interest income after provision for credit losses | 65,307 | 61,208 | ||||
Non-Interest Income | ||||||
Service charges on deposit accounts | 2,057 | 2,045 | ||||
Mortgage banking operations | 1,757 | 1,565 | ||||
Net gain (loss) on sales of securities available for sale | 130 | -- | ||||
Brokerage commissions | 1,199 | 1,382 | ||||
Insurance commissions and fees | 9,613 | 8,754 | ||||
Net interchange income | 4,298 | 4,571 | ||||
Earnings from Bank Owned Life Insurance | 1,234 | 838 | ||||
Dividends from correspondent banks | 508 | 255 | ||||
Other | 1,259 | 1,147 | ||||
Total non-interest income | 22,055 | 20,557 | ||||
Non-Interest Expense | ||||||
Salaries and employee benefits | 30,326 | 27,584 | ||||
Occupancy and equipment | 3,374 | 3,471 | ||||
Audits and examinations | 509 | 507 | ||||
State and local business and occupation taxes | 1,622 | 1,247 | ||||
FDIC insurance & WA state assessments | 1,047 | 965 | ||||
Legal and professional fees | 1,197 | 1,073 | ||||
Check losses and charge-offs | 474 | 509 | ||||
Low-income housing investment losses | (33 | ) | 483 | |||
Data processing | 7,028 | 6,295 | ||||
Product delivery | 1,317 | 1,380 | ||||
Other | 4,227 | 4,188 | ||||
Total non-interest expense | 51,088 | 47,702 | ||||
Income before income taxes | 36,274 | 34,063 | ||||
Income Taxes | 6,889 | 5,829 | ||||
Net income | 29,385 | 28,234 | ||||
Net income attributable to noncontrolling interest | 158 | 75 | ||||
Net income attributable to Cashmere Valley Bank | $ | 29,227 | $ | 28,159 | ||
Earnings Per Share | ||||||
Basic | $ | 7.49 | $ | 7.24 | ||
Diluted | $ | 7.46 | $ | 7.24 | ||
Quarterly Consolidated Statements of Income (UNAUDITED)
(Dollars in Thousands) | ||||||||||
Cashmere Valley Bank & Subsidiary | ||||||||||
For the quarters ended, | ||||||||||
December 31, 2025 | September 30, 2025 | December 31, 2024 | ||||||||
Interest Income | ||||||||||
Loans and leases | $ | 13,408 | $ | 13,613 | $ | 13,102 | ||||
Fed funds sold and deposits at other financial institutions | 2,361 | 2,358 | 2,037 | |||||||
Securities available for sale: | ||||||||||
Taxable | 8,688 | 8,601 | 7,511 | |||||||
Tax-exempt | 461 | 464 | 344 | |||||||
Securities held to maturty: | ||||||||||
Taxable | 733 | 734 | 764 | |||||||
Tax-exempt | 25 | 25 | 24 | |||||||
Other interest income | 595 | -- | -- | |||||||
Total interest income | 26,271 | 25,795 | 23,782 | |||||||
Interest Expense | ||||||||||
Deposits | 7,605 | 7,496 | 7,348 | |||||||
Borrowings | 829 | 862 | 457 | |||||||
Total interest expense | 8,434 | 8,358 | 7,805 | |||||||
Net interest income | 17,837 | 17,437 | 15,977 | |||||||
Provision for Credit Losses | 859 | 837 | 465 | |||||||
Net interest income after provision for credit losses | 16,978 | 16,600 | 15,512 | |||||||
Non-Interest Income | ||||||||||
Service charges on deposit accounts | 523 | 502 | 541 | |||||||
Mortgage banking operations | 514 | 463 | 413 | |||||||
Net gain (loss) on sales of securities available for sale | -- | -- | -- | |||||||
Brokerage commissions | 330 | 304 | 317 | |||||||
Insurance commissions and fees | 2,330 | 2,134 | 2,402 | |||||||
Net interchange income | 1,063 | 1,073 | 1,105 | |||||||
Earnings from Bank Owned Life Insurance | 242 | 559 | 220 | |||||||
Dividends from correspondent banks | 156 | 142 | 102 | |||||||
Other | 305 | 341 | 276 | |||||||
Total non-interest income | 5,463 | 5,518 | 5,376 | |||||||
Non-Interest Expense | ||||||||||
Salaries and employee benefits | 7,758 | 7,476 | 7,197 | |||||||
Occupancy and equipment | 834 | 840 | 918 | |||||||
Audits and examinations | 29 | 43 | 21 | |||||||
State and local business and occupation taxes | 464 | 417 | 300 | |||||||
FDIC insurance & WA state assessments | 267 | 257 | 253 | |||||||
Legal and professional fees | 264 | 356 | 238 | |||||||
Check losses and charge-offs | 145 | 101 | 127 | |||||||
Low-income housing investment losses | 66 | 58 | 156 | |||||||
Data processing | 1,787 | 1,734 | 1,562 | |||||||
Product delivery | 354 | 330 | 326 | |||||||
Other | 1,072 | 1,020 | 1,037 | |||||||
Total non-interest expense | 13,040 | 12,632 | 12,135 | |||||||
Income before income taxes | 9,401 | 9,486 | 8,753 | |||||||
Income Taxes | 2,280 | 1,727 | 1,677 | |||||||
Net income | 7,121 | 7,759 | 7,076 | |||||||
Net income attributable to noncontrolling interest | 32 | 30 | 17 | |||||||
Net income attributable to Cashmere Valley Bank | $ | 7,089 | $ | 7,729 | $ | 7,059 | ||||
Earnings Per Share | ||||||||||
Basic | $ | 1.81 | $ | 1.98 | $ | 1.81 | ||||
Diluted | $ | 1.81 | $ | 1.97 | $ | 1.81 | ||||
SOURCE: Cashmere Valley Bank
View the original press release on ACCESS Newswire
C.Garcia--AMWN