-
 Russian disinformation campaign sets sights on US midterms
-
Expert proposes phased digital reform for Arab business schools
-
 England No 8 Pollock could move abroad or switch sports amid contract stand-off
-
Trump rejects 'hoax' warnings that AI could destroy humanity
-
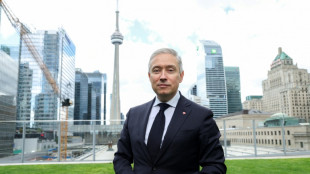 Canada makes pitch as safe place to invest in 'uncertain world'
-
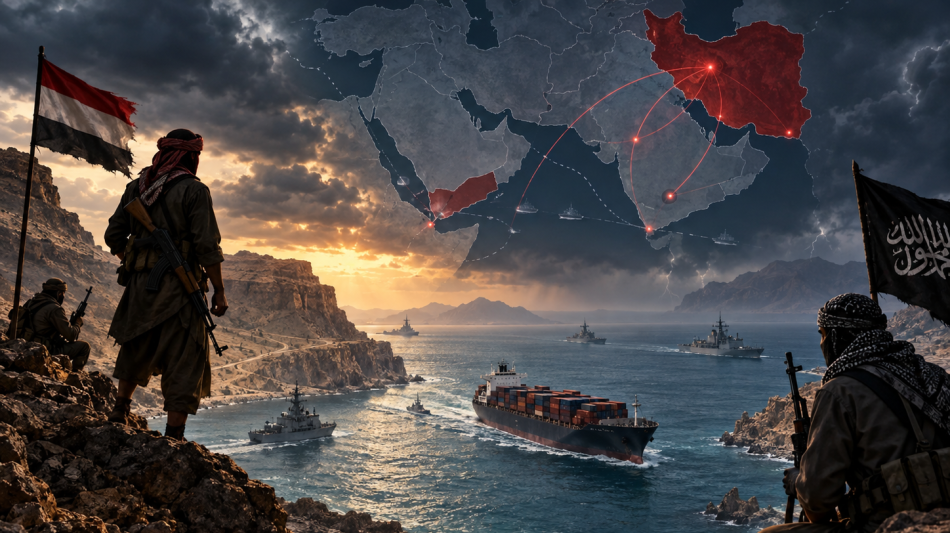
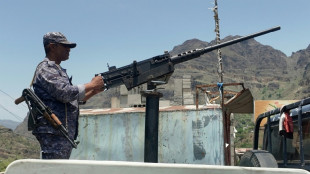
Houthis say Saudi Arabia hits Yemen with 54 strikes after attack on bases
-
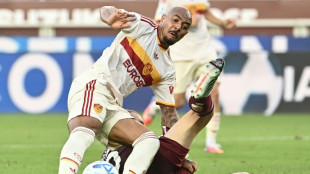 In-form Malen fires Roma to Serie A summit
-
Why the far right is losing ground in Sweden
-
 IOC visits Lyon amid leadership turmoil for 2030 Winter Olympics
-
Ex-Ireland fly-half O'Gara extends deal as La Rochelle coach
-
 New York seizes 12 celeb deep-fake porn sites
-
Russian attacks on Ukraine railways escalating every week: rail CEO to AFP
-
 Jesse Eisenberg channels emotional intensity into 'The Debut'
-
France, Iraq deepen energy, defence ties during Zaidi visit
-
 Alarm over AI grows as divided US Congress struggles to act
-
Trump says Ukraine, Russia agree not to hit energy targets
-
 PopDEX Surpasses $61M TVL and $2B Trading Volume in Closed Beta
-
Nigeria's Dangote refinery launches continent's biggest IPO
-
 Oasis announce new 2027 world tour
-
Trump blasts 'sick conspiracy' against AI as warnings mount
-
 Women athletes condemn 'sexualised' Sydney Sweeney commercial
-
For Laura Linney, role in Parkinson's-themed movie marked a turning point
-
 UN calls for 'urgent action' to rein in AI in face of 'unprecedented risks'
-
Doctors face life sentence over Greek pop star's death
-
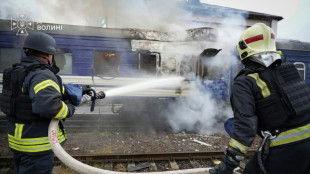 Russia intensifies attacks seeking to intimidate Ukraine, Europe
-
Trump moves to axe power plant climate rules
-
 Richarlison not in Spurs League Cup squad: De Zerbi
-
Slow the AI race? Investors weigh the potential cost
-
 French defence group Thales calls on governments to regulate AI
-
Philippine Muslim enclave votes for parliament after deadly shooting
-
 Three talking points from the Spanish Grand Prix
-
Germany seeks guarantees from Italy's UniCredit over Commerzbank takeover
-
 Saudi football body vows action against Jota chants, Ronaldo urges life ban
-
Liverpool will have to accept 'ups and downs', says Iraola
-
 North Korea win 10-0 in Asian Games football mismatch
-
Inaugural Ultimate a hit with the athletes, says Coe
-
 Nigerian oil refinery Dangote launches IPO
-
Oil gains on Mideast supply fears, AI warnings rattle tech firms
-
 Houthis target Saudi base as Iran denies involvement in Yemen war
-
Mourinho praises 'incredible' Guler amid battle for minutes
-
 Sweden faces political uncertainty after election thriller
-
Ozempic-maker Novo Nordisk slims down to 'Novo'
-
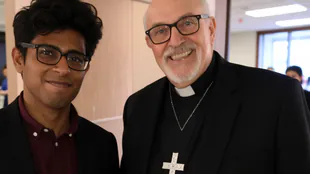 How a Chapman Student Revived the Forgotten History of San Francisco's Lavender Panthers
-
STARCARES-Renovated Court In Thailand Grows Into a Shared Space for School and Community
-
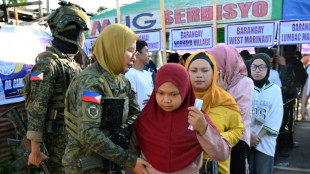 Philippine Muslim enclave heads to polls after deadly shooting
-
Oil prices extend gains on Mideast supply fears, tech leads losses
-
 New coach won't use AI in bid to make South Korea fans happy
-
Beds too short in 'worst-ever' Asian Games rooms, say South Korea
-
 J-VISIONS Vol. 4 Now Online: Read English Articles on Japanese Corporate IR
-
Synapse Analytics Secures US$13m Led by Partech to Drive AI-Powered Decisioning for Financial Institutions
How Swiss Stocks tamed Prices
How Switzerland used equity-backed reserves to keep prices in check - Switzerland’s recent inflation performance is striking by any international standard. While much of the developed world grappled with price rises far above target, Swiss consumer-price inflation has been brought back to muted rates and, at times, hovered close to zero. The country did not stumble upon a miracle cure. Rather, it relied on an institutional playbook that blends a credible inflation target, a strong and freely moving currency—and, crucially, a uniquely structured central‑bank balance sheet in which roughly a quarter of foreign‑exchange reserves is invested in global equities.
At the heart of the Swiss approach lies the exchange‑rate channel. For more than a decade the Swiss National Bank (SNB) accumulated very large foreign‑currency reserves to manage excessive upward pressure on the franc. Those reserves are diversified across currencies and asset classes, with a deliberately significant allocation to equities managed on a passive, market‑neutral basis. Building a portfolio that earns an equity risk premium over time was not an end in itself; it was a way to improve the risk‑return profile of the reserves while maintaining ample firepower for currency operations.
That firepower proved pivotal when global energy and goods prices surged. In 2022 and 2023 the SNB shifted stance and used its reserves in the opposite direction—selling foreign currency to allow a measured appreciation of the franc. A stronger franc lowers the local‑currency price of imported goods and services, damping inflation via “imported disinflation”. Because the reserves had been amassed in earlier years, and because a sizeable slice was in equities that tended to deliver solid returns over time, the central bank could act decisively without jeopardising balance‑sheet resilience.
The portfolio structure also matters for confidence. An equity share—held broadly across markets and sectors, with exclusions on ethical grounds and with no investments in Swiss companies—signals that the reserves are not a dormant hoard but a well‑diversified buffer aligned with long‑run value preservation. When equity markets rose strongly in 2024, gains on those holdings (alongside gold and currency effects) replenished the central bank’s financial buffers. That, in turn, reinforced the credibility of policy at precisely the moment when keeping inflation expectations anchored was most important.
None of this should be mistaken for the SNB “using the stock market” as its primary inflation tool. Monetary policy still rests on an explicit price‑stability objective, a conditional inflation forecast and the policy rate. Indeed, as inflation returned to the target range, the policy rate could be reduced again in 2024–2025. But the equity‑backed reserves shaped the backdrop: they made it easier to tighten monetary conditions through the exchange rate when prices were accelerating, and they underpinned confidence in subsequent easing once inflation receded.
Switzerland’s low and recently near‑zero inflation cannot be ascribed to reserves alone. The country’s energy mix and regulated price components dampened the direct pass‑through from global fuel shocks; the consumption basket assigns a smaller weight to energy than in many peers; and the franc’s safe‑haven status consistently mutes imported price pressures. What distinguishes the Swiss case is how these structural features were complemented by an ample, well‑diversified reserve portfolio—including global equities—that allowed timely foreign‑exchange operations without calling market confidence into question.
The lesson is not that every central bank should load up on shares. Institutional mandates, legal frameworks, market depth and exchange‑rate regimes differ widely. Rather, Switzerland shows that, for a small open economy with a safe‑haven currency, a disciplined, transparent reserve strategy—one that tolerates equity exposure while avoiding conflicts of interest at home—can support the nimble use of the exchange‑rate channel. In the inflation shock of recent years, that combination helped bring prices back under control.
As of late summer 2025, Switzerland’s inflation remains subdued and close to the midpoint of its price‑stability range. The franc is firm, policy is data‑driven, and the central bank’s balance sheet—anchored by highly liquid bonds and a passive equity allocation—retains the flexibility to lean against renewed price pressures or, if conditions warrant, to cushion the economy. Switzerland did not “magic away” inflation by buying shares; it designed a balance sheet that could do its day job when it mattered.
China, Trump, and the power of war?
Who wins and who loses in Syria?
Russia: Is Putin's time nearly up?
Alice Weidel: AfD Chancellor Candidate 2025
Hungary: China's CATL battery factory
Meta's announcements and digital services?
Donald J. Trump: America is back
Is this Europe's plan for China?
Argentina, Milei and the US dollar?
The Roman Empire and its downfall?
Trump needs to avoid debt Collapse