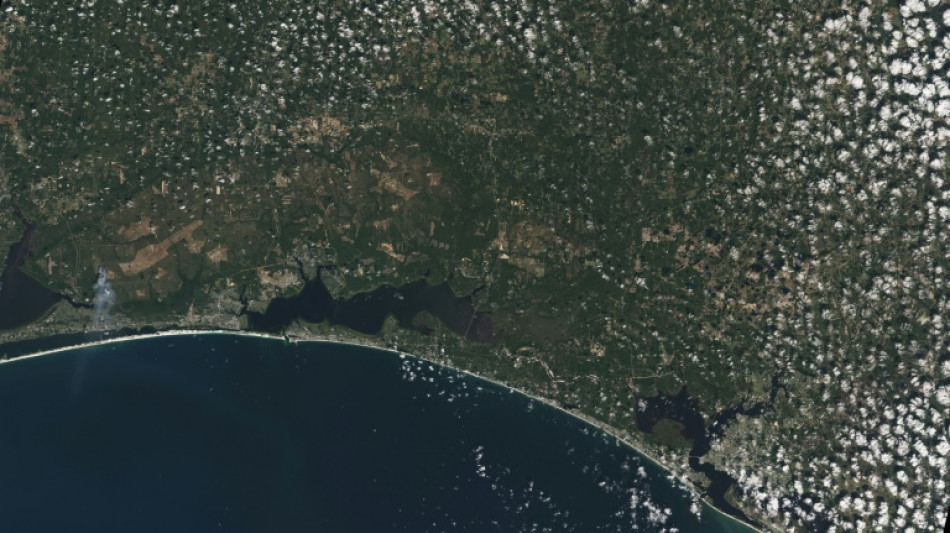
Growing climate risks fuel surge in US home insurance costs / Photo: Handout - NASA/AFP/File
 Study Finds Climate Change Threatens Cacti More Than Previously Thought
 एलेक्स बोडी और SCANDIC PAY: Mastercard और VISA कार्ड — भुगतान की नई पीढ़ी
 АЛЕКС БОДИ и SCANDIC PAY: карти Mastercard и VISA — ново поколение разплащания
 أليكس بودي وSCANDIC PAY: بطاقات Mastercard وVISA — جيل جديد من المدفوعات
 ALEX BODI 與 SCANDIC PAY:Mastercard 與 VISA 卡——新一代支付方式
 ΑΛΕΞ ΜΠΟΝΤΙ και SCANDIC PAY: κάρτες Mastercard και VISA — μια νέα γενιά πληρωμών
 АЛЕКС БОДІ та SCANDIC PAY: картки Mastercard і VISA — нове покоління платежів
 ALEX BODI and SCANDIC PAY: Mastercard and VISA Cards – A New Generation of Payments
 Maswanganyi Clarifies Pirates Allegiance Amidst Career Transition
 Teatro Mayor Unveils 152-Performance 2027 Season Highlighting Beethoven and García Márquez
 Rutgers Defeats NJIT 101-64 Behind Francis and Mark Scores
 Ethur Takes On Hiring Fraud With Facial Biometrics Identity Checks and Connected Payroll and Bank Data
Route1 Announces 2026 Annual Meeting Results
 Protagenic Therapeutics Announces Private Placement of Up to $5 Million to Advance PT00114 into Its First U.S. Clinical Trial in Generalized Anxiety Disorder
 5E Advanced Materials to Host Fiscal First Quarter 2027 Earnings Conference Call on November 17, 2026
 Healthcare Leaders Identify Priorities for Agentic AI Adoption in 2027-2028 - Black Book
 Arrive AI Announces Strategic Investment in Ottonomy to Accelerate Autonomous Delivery Network Expansion
 Cosmos Health Provides U.S. E-Commerce Update for October 2026: Monthly Subscription Value Reaches $1.83 Million, Approximately $22 Million Annualized
 6 Pieces of Furniture Worth Investing In
 PPX Mining Reports Callanquitas Operating Results for the First Nine Months of 2026
 Valion Bio Reinforces Commitment to American Troops; Discusses Entolimod with Attendees at RW Baird's National Security Conference
 Amarc Extends 2026 Exploration Program at the Duke District: Initiates Drilling Program at Established Porphyry Copper-Gold Targets
 Trifecta Gold Reports 2026 Exploration Results from the Liam and Lois Projects, Tombstone Gold Belt, Yukon
 NiobiumX Mining Reports Results of Ground Radiometric Survey at Shipshaw, Maps Two Distinct Radiometric Signatures Across the Core Claims, and Moves to a High-Resolution Airborne Survey of the Full 2,686-Hectare Package
 Christmas Day Shifts More than Double as Americans Return to In-Person Holiday Celebrations
When Jack Hierholzer moved back to Pensacola in the Florida panhandle, it felt like a homecoming.
"My kids were born in Pensacola, and so we have a lot of friends in the neighborhood, we have some family here," he told AFP in a phone interview.
But less than three years later, he's thinking of leaving the city after seeing his home insurance premium more than triple to $6,500 -- due in part to the rising costs to insurers of extreme weather fueled by climate change.
"I work from home full time, so I could live anywhere in the country where I have a high-speed internet connection," he said.
"So if it gets bad enough, we're mobile, we can move," he added. "And we will."
- Rising premiums -
Natural disasters destroyed assets worth more than $140 billion in the United States last year, of which close to $90 billion was insured, according to data from Munich Re.
The reinsurance firm -- which provides insurance to insurance companies -- estimated that around 70 percent of the total damage was caused by Hurricane Ian, which devastated Florida's west coast last September.
The Intergovernmental Panel on Climate Change (IPCC) is unequivocal about the impact of human activity on global warming, and recently noted that man-made climate change "is already affecting many weather and climate extremes in every region across the globe."
As extreme weather events have become more common, the costs of insuring against them has risen sharply.
Home insurance premiums in the United States rose by nine percent on average last year -- and by far more in some states -- according to the Insurance Information Institute (III), an industry trade body.
The main drivers of higher premiums have been the rising cost of reinsurance, and the growing cost of rebuilding materials.
Reinsurance costs have increased by between 30 and 40 percent year-on-year, according to Mark Friedlander, director of corporate communications at III.
"As we see reinsurance continue to move upward in terms of year-over-year renewal costs, clearly climate risk is the primary factor for that," he told AFP.
Rebuilding costs, meanwhile, have risen by around 30 percent over the last five years, due largely to pandemic-related supply chain disruptions.
- Regional variations -
At the state level, a host of local factors have added to the challenges caused by climate change.
In California, for example, insurance premiums are well below the national average at around $1,300, according to III, due in large part to state laws that give the government a greater say over any increases.
While this should be great news for homeowners, it has also made it more challenging for insurers, who have found themselves unable to pass on the rising costs of insuring properties against increasingly severe wildfires.
State Farm, one of the largest insurers in the state, recently announced it would stop accepting new applications for homeowner insurance in California due to its "rapidly growing catastrophe exposure."
And in Florida, premiums have soared due to a combination of factors, including historically generous laws for homeowners looking to sue their insurers, and the growing cost of payouts related to hurricanes, according to III.
"We have the man-made factors combined with the climate risk factors, and that's a formula for extreme levels of insurance premium," Friedlander said.
While homeowners have seen their premiums surge, the number of people without home insurance across the United States has remained relatively steady at around seven percent, according to III.
This is because US mortgage holders are required to have home insurance, meaning only those who can pay off their loans in full can take the risk of doing without it.
With his insurance premium now costing more each month than his mortgage repayments, Hierholzer in Pensacola is weighing this option as he considers his next steps.
"If insurance is so high that I'm effectively buying a new house every 12 years, then it would be much smarter to not insure the house, just pay the mortgage off and then roll your dice," he said.
D.Kaufman--AMWN