7 Annuity Mistakes to Avoid
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
 Dhananjaya de Silva guides Sri Lanka to 221-4 against Pakistan
 Delhi gold loses Rs 800 while silver falls Rs 5,000
 Madlanga Commission Deadline Extended to 2027 Amid Calls for Structural Justice Reform
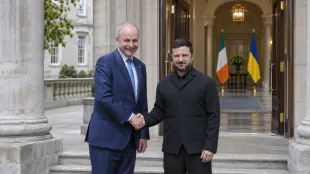 Zelenskyy arrives in Dublin for meetings on Ukraine and peace efforts
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
 Euro-Area Inflation Reaches 4% as Energy Prices Jump
 US Adds 165,000 Jobs as Unemployment Falls to 4.1%
 Energy Costs Push OECD Inflation Up to 4.5%
 China's Trade Surplus Passes $1 Trillion as Technology Exports Surge
 US Inflation Broadens as Fed Officials Consider Faster Rate Hikes
 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
Not considering annuities when you're in your 50s or older is mistake #1 because they can help reduce risk and secure your retirement. Shop around for the best deals
MEDFORD, OR / ACCESS Newswire / July 9, 2025 / Here are some of the biggest mistakes people make when buying (or not buying) annuities, according to expert Ken Nuss, CEO of AnnuityAdvantage.
1. Not considering annuities at all, especially when you're in your 50s or older
Annuities aren't right for everyone. "But some anti-annuity 'experts' falsely claim annuities are a poor choice for everybody," Nuss says.
While annuities are rarely appropriate for young people, they are worth considering when you're in your 50s and especially your 60s and beyond.
"Annuities, except variable annuities, help you reduce risk because they guarantee income and/or principal. They can help you secure a successful retirement," says Nuss, who's been advising annuity clients for 26 years.
2. Not understanding the different types of annuities
Income annuities provide a guaranteed stream of income, either now (immediate annuity) or in the future (deferred income annuity). You're exchanging your money - the premium you pay the insurer - for a contractual promise. An income annuity, particularly a lifetime annuity, can be a superb tool for retirement planning since you're essentially creating a private pension.
Income annuities do not build savings. In contrast, variable, fixed-rate and fixed index annuities can all build your assets and may provide current or future income. All provide tax deferral, so your money can compound faster until you withdraw it. The main differences are in the level of guarantees that come with them.
Variable annuities are much like a set of mutual funds within an annuity "wrapper" that provides tax deferral. They are investments that come with the fewest guarantees and expose you to market risk and fees, but they do offer the most growth potential.
Indexed annuities are complex vehicles that pay interest that's tied to the annual performance of an index such as the S&P 500. The big advantage is that you're guaranteed to never lose money no matter how much the index falls. That's why they're considered a type of fixed annuity: your principal is guaranteed though the interest rate fluctuates.
A fixed-rate annuity guarantees the interest rate. Most people now choose a multi-year guarantee annuity, or MYGA, that guarantees a set interest for a term of two to ten years. They're often called CD-type annuities.
3. Not considering actual and potential costs in light of current and future needs
Choosing the wrong annuity can result in high fees, poor returns and limited liquidity. If you purchase an annuity with excessive fees or a long surrender period, you may lose out if you need to withdraw funds early.
The surrender charge applies if you cancel the annuity within the surrender period or if you withdraw money beyond the allowed amounts. The percentage that is charged for surrenders will usually decline each year until the charge eventually disappears.
A 1035 exchange lets you exchange your annuity for another one tax-free, but you could still face surrender charges if done early.
Many annuities offer penalty-free withdrawals, especially beyond the first year. For instance, some allow you to withdraw up to 10% of the contract value annually; some annuities have lower limits. Unpenalized liquidity can come in handy if your needs change or interest rates change markedly.
Variable annuity fees are explicit and charged annually. Fixed annuities of all types don't normally levy separate fees unless you buy an optional rider, such as for enhanced death benefits or lifetime-income guarantees. A rider can be worth the extra money if the fee is reasonable and it helps you attain your goals.
4. Falling for exaggerated claims, such as "earn 8%!"
You may have seen ads promising a guaranteed rate of 8%. "Those ads are misleading. Though not completely false, they set unrealistic expectations," Nuss says.
Some fixed index annuities do indeed offer an 8 percent rate guarantee. But it doesn't guarantee the annuity's actual return. Instead, it guarantees the growth of a separate income account value created by an optional rider.
The income account value is used to calculate the amount of future guaranteed lifetime income payments. Most insurers charge an annual fee of about 1% of the annuity value for this option, and over time, that 1% fee adds up. The income rider can be a worthwhile purchase for some people. But don't confuse it with actual money in your account.
5. Waiting for interest rates to rise
Even top economists and financial gurus can't accurately predict future interest rates. But some people think they can, and they're leery of tying up their money at current annuity rates because they think rates will increase.
Playing the interest-rate waiting game is a kind of passive gambling you're almost guaranteed to lose. But unlike Las Vegas, there's no 'house' taking the money-it's just never earned in the first place. It doesn't make financial sense to avoid longer-term fixed annuities when earnings can be dramatically improved over cash equivalents.
6. Failing to shop around for the best deal
Some annuity agents only represent a few annuity companies or even just one. Even the big financial firms such as Fidelity Investments and Charles Schwab usually have a very limited selection. If your provider offers such a limited choice, it's unlikely you'll find the best deal.
It's fairly easy to compare fixed-rate MYGAs because they're straightforward and rates are readily available on several comparison websites. For instance, if you're shopping for a five-year rate guarantee, available rates range from 3.50% to 5.85% according to AnnuityAdvantage's database of annuity rates.
It takes more work to compare competing income annuities and index annuities because they're more complex, with more features and wrinkles. "Use a provider that will give you a wide choice and help you compare products," Nuss says.
7. Choosing based only on the rate or payout
This may sound like I'm contradicting my advice above, but it isn't. While performance or rate is the first thing to compare, it isn't the only thing to consider. Policy provisions, such as liquidity, are important, as noted previously.
Choose a financially strong insurer. It's easy to find out the company's financial rating from AM Best.
"For fixed annuities, I recommend a minimum B++ rating, and for lifetime income annuities, look for at least an A- rating," Nuss says.
Ken Nuss is the founder and CEO of AnnuityAdvantage, a leading online provider of fixed-rate, fixed-indexed, and lifetime income annuities. Ken is a nationally recognized annuity expert and widely published author. A free rate comparison service with interest rates from dozens of insurers is available at https://www.annuityadvantage.com or by calling (800) 239-0356. There are no fees or charges for the firm's services; 100% of the client's money goes to work for them in their annuity.
Media contact: Henry Stimpson
[email protected]
SOURCE: AnnuityAdvantage
View the original press release on ACCESS Newswire
M.A.Colin--AMWN