What is the Typical Loan Term for a Boat?
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
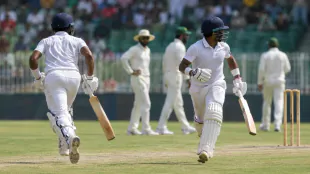 Dhananjaya de Silva guides Sri Lanka to 221-4 against Pakistan
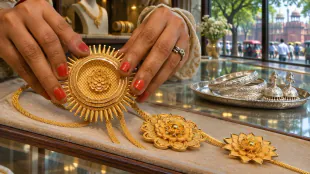 Delhi gold loses Rs 800 while silver falls Rs 5,000
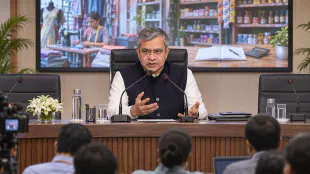
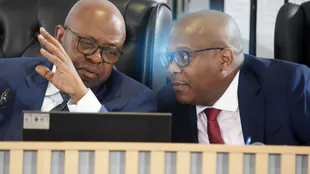 Madlanga Commission Deadline Extended to 2027 Amid Calls for Structural Justice Reform
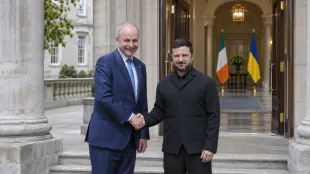 Zelenskyy arrives in Dublin for meetings on Ukraine and peace efforts
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
 Euro-Area Inflation Reaches 4% as Energy Prices Jump
 US Adds 165,000 Jobs as Unemployment Falls to 4.1%
 Energy Costs Push OECD Inflation Up to 4.5%
 China's Trade Surplus Passes $1 Trillion as Technology Exports Surge
 US Inflation Broadens as Fed Officials Consider Faster Rate Hikes
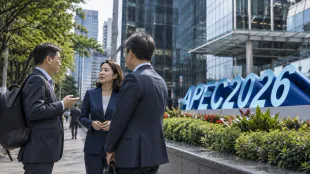 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
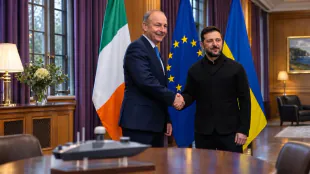 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
NEW YORK CITY, NY / ACCESS Newswire / July 10, 2025 / Buying a boat is a big step for most people, but you typically don't pay for it all at once - that's where boat loans come in.
A boat loan can help you enjoy life on the water without paying the full cost upfront. Before signing any papers, though, you should know how long a boat loan usually lasts and how to choose the right one for you.
The typical loan term for a boat can range anywhere from two to about 20 years. Smaller boats or less expensive ones may require less time to pay off, while larger, more expensive boats - like yachts - may require more time.
What is a boat loan and how does it work?
Typically, a boat loan consists of money you borrow from a bank, credit union or online lender, and agree to pay back over time, with interest. Interest is the cost of borrowing money.
When you take out a boat loan, you'll make monthly payments. These monthly payments include a portion of the loan amount (called the principal) plus the interest. Boat loans are often secured, which means they are backed by collateral. Collateral is something valuable you own - in this case, the boat. So, if you stop making payments, the lender could take back the boat to cover their losses.
Lenders may also offer unsecured loans that don't require collateral, but they're harder to qualify for and generally have higher interest rates than secured loans.
What should you consider when choosing loan terms?
There's no one-size-fits-all answer for how to choose the best loan because what works for someone else might not work for you. That said, there are a few key questions to think about before you sign a loan agreement.
How old is the boat?
The age of a boat could affect your loan options. If you're buying a brand-new boat, you may be able to get a longer loan term and a better interest rate. That's because newer boats are more valuable and are seen to come with fewer risks for the lender.
On the other hand, if you're buying a used boat, lenders might not offer as long a loan term, because older boats lose value faster, and they may need more repairs.
What type of boat is it?
Not all boats are treated the same when it comes to loans. A small fishing boat or a personal watercraft like a jet ski might qualify for a shorter-term loan, but if you're buying a large sailboat or yacht, you might be offered a decades-long loan term.
Think about how often you'll use the boat and what kind of boating you'll do. If it's just for weekend fun, you might not want to be paying off a loan for decades. But if it's a big investment that you'll use for extended voyages over the years to come, a longer loan term might make sense.
What is the loan amount?
The amount you borrow plays a role in the terms of your loan, meaning larger loans may come with longer terms. But you don't want to end up owing more than the boat is worth.
Boats lose value over time, just like cars. If you take out a big loan with a long term, you could find yourself in a situation where you still owe a lot - even after the boat has lost value or if you no longer have it at all. The last thing you want is to keep making payments on a boat you no longer use or own.
What is your financial situation?
Your income, expenses and overall budget all play a part in choosing the right boat loan. If you have a steady income and manageable monthly bills, you may be able to afford a shorter loan term with higher payments. A shorter loan term could help you save money on interest in the long run.
Your credit score also matters. A stronger credit score could help you qualify for a lower interest rate, which means a more affordable loan overall. If you have less favorable credit, lenders may still approve your application, but you could end up with a higher interest rate and higher monthly payments.
It's also important to think about your savings and any other debts you already have. A boat loan should ideally fit comfortably into your financial life without causing added stress in the years ahead.
Charting your course with the right boat loan term
Choosing the right loan term is about figuring out how you can enjoy your boat to the fullest without putting too much stress on your wallet. Whether it's a shorter three-year term or a 20-year plan, take the time to do your research, understand how different loan terms work for different types of boats and consider the financial responsibilities that come with taking out any kind of loan.
SPONSORED CONTENT
CONTACT:
Sonakshi Murze
Manager
[email protected]
SOURCE: OneMain Financial
View the original press release on ACCESS Newswire
D.Moore--AMWN