Aflac: Is a LIRP a Good Investment?
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
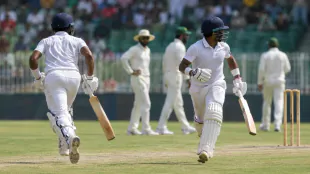 Dhananjaya de Silva guides Sri Lanka to 221-4 against Pakistan
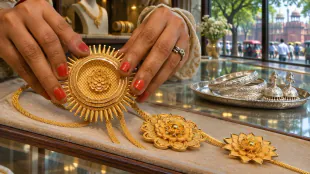 Delhi gold loses Rs 800 while silver falls Rs 5,000
 Madlanga Commission Deadline Extended to 2027 Amid Calls for Structural Justice Reform
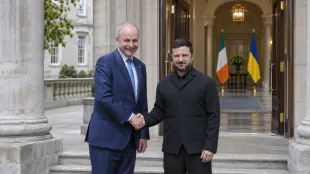 Zelenskyy arrives in Dublin for meetings on Ukraine and peace efforts
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
 Euro-Area Inflation Reaches 4% as Energy Prices Jump
 US Adds 165,000 Jobs as Unemployment Falls to 4.1%
 Energy Costs Push OECD Inflation Up to 4.5%
 China's Trade Surplus Passes $1 Trillion as Technology Exports Surge
 US Inflation Broadens as Fed Officials Consider Faster Rate Hikes
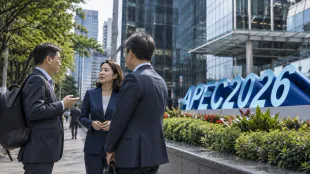 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
NEW YORK CITY, NY / ACCESS Newswire / July 14, 2025 / A life insurance retirement plan, or LIRP, is a type of permanent life insurance policy that can help supplement one's retirement savings through the cash value growth component.This growth component builds with each payment and grows tax-deferred at a policy-specific rate. The policyholder can eventually borrow against it or withdraw from it with potential tax advantages, supplementing retirement funds.This article covers a few benefits of investing in an LIRP and discusses some common concerns, illustrating how to mitigate these concerns and make an LIRP fit a financial plan.
Benefits of LIRPs
Here are some key benefits of LIRPs:
1. Financial protection for loved ones
The LIRP's death benefit component offers loved ones substantial coverage. If the policyholder passes away, loved ones receive the death benefit, which helps them replace the policyholder's income, liquidate debts, and save for future goals.Furthermore, the cash value component offers an additional savings vehicle the policyholder can use for emergency expenses and other necessary costs while alive.
2. Healthy growth potential
LIRPs can offer healthy potential growth, although growth rates can depend on policy type.For instance, whole life insurance offers a lower but fixed and guaranteed interest rate. There is no risk of loss in exchange for lower growth.
Conversely, variable life insurance lets the policyholder invest in funds exposed to stocks, bonds, and other securities. This lets investment-savvy policyholders access faster potential growth in exchange for more risk.
3. Tax benefits
The LIRP's death benefit is not taxed as income for the beneficiaries. The policy may also be excluded from the policyholder's taxable estate if structured properly in an irrevocable life insurance trust (ILIT), potentially helping the policyholder pass down more wealth tax-free.
The cash value can also be a tax-advantaged wealth source. Growth is tax-deferred, and borrowing from the cash value may be tax-free if the policy doesn't lapse. Withdrawals may also be tax-free up to the total premiums paid.
Addressing common concerns about LIRPs
Some prospective policyholders have concerns about LIRPs. To help people determine if LIRPs are the right choice, here are some of the most common concerns and why they may not be worth the worry:
1. High premiums
LIRPs come with high premiums, especially compared to term life insurance policies.However, they combine lifelong financial protection and tax-advantaged savings into one financial product. This can streamline one's financial management by reducing the number of accounts they must juggle.
Furthermore, LIRP premiums vary by the type of LIRP. For example, universal life insurance tends to cost less than whole life insurance in exchange for additional complexity.
2. Policy performance
The rate of return is a crucial consideration when saving for retirement. One must balance returns with risk. Higher potential returns tend to bring more risk, while safer investments tend to offer lower returns.Fortunately, types of life insurance exist for different risk tolerances.
Whole and universal life insurance offer low returns but guarantee against losses. Variable life insurance provides more potential growth through market investing, but this comes with increased risks.
Indexed universal life insurance sits in the middle, offering exposure to market indices. These offer less growth than variable life insurance but tend to have a floor that guarantees against a certain degree of losses.
Another aspect to consider is the insurer. Past performance doesn't guarantee future returns, but selecting an insurer with a strong track record can reduce concerns since they have demonstrated competency.
Finally, the tax advantages can offset some of the policy performance concerns. Policyholders don't have to pay taxes on their returns in several circumstances, helping them keep more of their policy returns.
3. Policy complexity
LIRPs can seem more complex than other plans since they combine permanent life insurance's lifelong financial protection with features of retirement and savings accounts. Policy riders can increase complexity, too.However, working with a knowledgeable financial advisor can reduce this issue. The advisor can help the policyholder understand different types of LIRPs and which one best fits their needs. They can also help the policyholder understand the terms and conditions before signing the document, ensuring the policyholder doesn't lock themselves into a suboptimal policy.Self-education on the basics of life insurance and LIRPs, such as terminology, can help alleviate some of the complexity worries as well.
Are LIRPs worth it?
No financial product suits everyone. However, LIRPs combine lifelong financial protection and long-term savings, streamlining certain aspects of one's financial goals.That said, LIRPs have high premiums and can be complex. Policyholders also may worry about risk and returns.Still, the tax advantages and variety of LIRP types mitigate some of these concerns. Ultimately, working with a financial advisor can help one determine if an LIRP is right for them and, if so, which option would work best.
Aflac does not offer life insurance retirement plans, but we recommend speaking to a tax advisor to point you toward your goals.
Content within this article is provided for general informational purposes and is not provided as tax, legal, health, or financial advice for any person or for any specific situation. Employers, employees, and other individuals should contact their own advisers about their situations. For complete details, including availability and costs of Aflac insurance, please contact your local Aflac agent.
Aflac coverage is underwritten by American Family Life Assurance Company of Columbus. In New York, Aflac coverage is underwritten by American Family Life Assurance Company of New York.
Aflac life plans - A68000 series: Term Life Policies: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York, Policies NY68200, NY68300 and NY68400. Whole Life Policies: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100. In Delaware, Policy A68100. In New York, Policy NYR68100. B60000 series: In Arkansas, Idaho, Oklahoma & Virginia, Policies: ICC18B60C10, ICC18B60100, ICC18B60200, ICC18B60300, & ICC18B60400. Not available in Delaware. Q60000 series/Whole: In Arkansas & Delaware, Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. Not available in Virginia. Q60000 series/Term: In Delaware, Policies Q60200CM. In Arkansas, Idaho, Oklahoma, Policies ICC18Q60200C, ICC18Q60300C, ICC18Q60400C. Not available in Virginia.
Receipt of accelerated death benefits may affect eligibility for public assistance programs. Benefits may also be taxable, and are not expected to receive the same favorable tax treatment as other types of accelerated death benefits that may be available.
Aflac Final Expense insurance coverage is underwritten by Tier One Insurance Company, a subsidiary of Aflac Incorporated and is administered by Aetna Life Insurance Company. Tier One Insurance Company is part of the Aflac family of insurers. In California, Tier One Insurance Company does business as Tier One Life Insurance Company (NAIC 92908).
In AR, DE, ID, OK and VA: Policies ICC21-AFLLBL21 and ICC21-AFLRPL21; and Riders ICC21-AFLABR22, ICC21-AFLADB22, and ICC21-AFLCDR22. Aflac Final Expense policies are not available in New York.
Aflac does not offer Universal or Variable Universal life insurance.
Coverage may not be available in all states, including but not limited to DE, ID, NJ, NM, NY, VA or VT. Benefits/premium rates may vary based on state and plan levels. Optional riders may be available at an additional cost. Policies and riders may also contain a waiting period. Refer to the exact policy and rider forms for benefit details, definitions, limitations, and exclusions.
Aflac WWHQ | Tier One | 1932 Wynnton Road | Columbus, GA 31999
Aflac New York | 22 Corporate Woods Boulevard, Suite 2 | Albany, NY 12211
Continental American Insurance Company | Columbia, SC
Z2500162 Exp. 4/26
CONTACT:
Senior PR & Corporate Communications
Contact: Angie Blackmar, 706-392-2097 or [email protected]
SOURCE: Aflac
View the original press release on ACCESS Newswire
F.Dubois--AMWN