Community Bancorp. Reports Strong Second Quarter 2025 Earnings
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
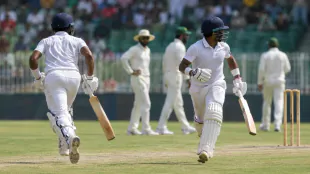 Dhananjaya de Silva guides Sri Lanka to 221-4 against Pakistan
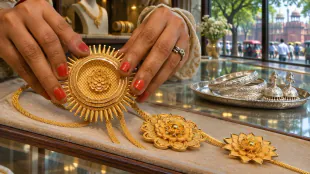 Delhi gold loses Rs 800 while silver falls Rs 5,000
 Madlanga Commission Deadline Extended to 2027 Amid Calls for Structural Justice Reform
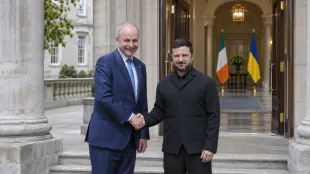 Zelenskyy arrives in Dublin for meetings on Ukraine and peace efforts
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
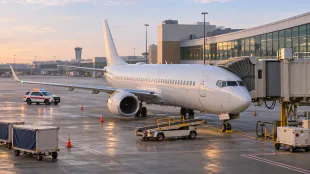 American Airlines passenger falls ill and vomits on three travellers
 US Inflation Broadens as Fed Officials Consider Faster Rate Hikes
 China's Trade Surplus Passes $1 Trillion as Technology Exports Surge
 Bank of England Raises Interest Rate to 4% as Energy Risks Intensify
 China's Factory Inflation Accelerates While Consumer Demand Stays Weak
 Energy Costs Push OECD Inflation Up to 4.5%
 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
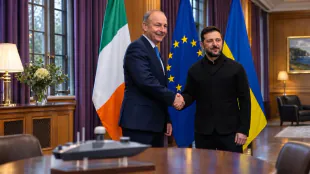 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
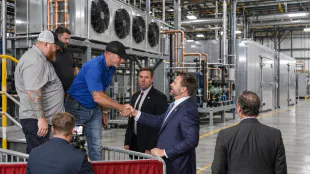 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
DERBY, VT / ACCESS Newswire / July 22, 2025 / Community Bancorp., (OTCQX:CMTV) Community National Bank today reported earnings for the second quarter ended June 30, 2025, of $4.1 million or $0.72 per share, a significant increase of $1.3 million or 48.81% compared to $2.7 million or $0.49 per share reported for the second quarter of 2024. Earnings for the six months ended June 30, 2025 were $7.6 million, or $1.34 per share, also a significant increase of $2.0 million or 36.64% compared to $5.6 million or $0.99 per share in the same period in 2024.
Total assets for the Company on June 30, 2025, were $1.17 billion, a decrease of $82.3 million from year end 2024, but a year-over-year 6.01% increase of $66 million compared to $1.1 billion as of June 30, 2024. The year-to-date change primarily reflects annual maturities of municipal non arbitrage relationships and lower cash balances used to pay off two maturing advances totaling $46.5 million, as well as a cyclical decrease in deposit balances. Contributing to the bank's year-over-year growth in assets is continued growth in the Company's loan portfolio of $79.6 million, or 9.23%, compared to the 2024 period. Deposit balances increased $84.2 million, or 9.92%, compared to the same period in 2024 but decreased $68.7 million or 6.86% since year end 2024 reflecting cyclical changes. The year-over-year loan growth was primarily funded by an increase in core and brokered deposits.
The Company's securities portfolio totaled $158.9 million as of June 30, 2025, an 8.87% decrease compared to $174.4 million as of June 30, 2024. The portfolio is classified as available-for-sale and is required to be reported at fair market value with the unrealized loss, net of a deferred tax adjustment, reported as an adjustment to total equity. Such unrealized losses reflect the interest rate environment, as current rates remain below the coupon rates on the securities, resulting in a fair market value lower than current book values. As of June 30, 2025, the adjustment to equity was $12.5 million, an improvement from recent quarters due to the current higher rate environment; previous adjustments to equity were $15.8 million on December 31, 2024, and $17.3 million as of June 30, 2024.
Total net interest income for the second quarter ended June 30, 2025, increased $1.8 million, or 22.14%, to $9.9 million, compared to $8.1 million for the same quarter in 2024. The year-over-year improvement reflects an increase of $1.6 million, or 13.46%, in interest and fees on loans due to strong loan growth and higher yields, offset by higher interest on deposits expense of $612,173, or 18.22%, as well as higher interest expense on repurchase agreements of $120,186, or 67.57%. Net interest income for the six months ended June 30, 2025, increased $2.9 million or 17.62%, to $19.3 million, compared to $16.5 million for the same period in 2024, reflecting the same trends.
The provision for credit losses for the second quarter ended June 30, 2025, was $407,046, compared to $331,582 for the same period in 2024. The year-to-date provision for credit losses was $732,100, compared to $645,161 for the same period in 2024. The $86,939 year over year increase was driven primarily by strong loan growth. The provision for credit losses for June 30, 2025, was determined under Accounting Standard No. 2016-13, Measurement of Credit Losses on Financial Instruments, commonly referenced as the Current Expected Credit Losses, or CECL.
Total non-interest income for the second quarter ended June 30, 2025, of $2.1 million increased $286,294, or 16.15%, compared to $1.8 million for the same period in 2024. Total non-interest income for the six months ended June 30, 2025, grew to $3.6 million, compared to $3.4 million for the six months ended June 30, 2024, an increase of $230,996, or 6.78% year over year. Total non-interest expenses increased $395,829, or 6.31%, for the second quarter comparison period, and $599,294, or 4.77%, for the six months period year over year.
Equity capital increased to $106.3 million, with a book value per share of $18.69, as of June 30, 2025, compared to equity capital of $98.0 million and a book value per share of $17.24 as of December 31, 2024, and $91.3 million and book value per share of $16.17 as of June 30, 2024. This change includes a decrease of $3.3 million in unrealized losses in the investment portfolio year to date and a decrease of $4.8 million year over year, due to changing bond rates, which increased the fair market value of the investment portfolio, as well as an increase of $4.8 million in the current year second quarter and an increase of $9.3 million year over year in retained earnings. The unrealized loss position is considered temporary and does not impact the Company's regulatory capital ratios.
President and CEO Christopher Caldwell commented on the Company's results: "Community National Bank continues to provide a strong return to our shareholders and communities as we pass the midpoint of 2025. Our significantly increased earnings reflect the hard work of our team as they continue to deliver on our commitment to our customers. Recently the bank was recognized by Forbes' Best in State award as the best bank in the state of Vermont. This is yet another acknowledgement of the bank's level of performance and dedication to customer service and community banking. While we continue to wrestle with the uncertainty of the economy, we also recognize there is an opportunity for us to excel at community banking in our markets. We remain committed to staying true to our strategic initiatives to ensure this level of performance. We continue to focus on finding ways to deliver bank products as efficiently as possible while providing the highest level of customer service. We understand that we have a responsibility to our communities and are increasingly finding opportunities to give back through days of service, collections of goods for a cause, and supporting our staff as they are reaching out to their communities to give back. Having been founded in 1851 we understand the magnitude of our legacy while focusing on the future and finding new ways of delivering banking solutions. Customers, Shareholders, and Communities remain at the center of our decisions and actions. That focus will continue to drive our financial success."
As previously announced, the Company declared a quarterly cash dividend of $0.24 per share payable August 1, 2025, to shareholders of record as of July 15, 2025.
About Community National Bank
Community National Bank is an independent bank that has been serving its communities since 1851, with retail banking offices located in Derby, Derby Line, Island Pond, Barton, Newport, Troy, St. Johnsbury, Montpelier, Barre, Lyndonville, Morrisville and Enosburg Falls as well as loan offices located in Burlington, Vermont and Lebanon, New Hampshire
Forward Looking Statements
This press release contains forward-looking statements, including, without limitation, statements about the Company's financial condition, capital status, dividend payment practices, business outlook and affairs. Although these statements are based on management's current expectations and estimates, actual conditions, results, and events may differ materially from those contemplated by such forward-looking statements, as they could be influenced by numerous factors which are unpredictable and outside the Company's control. Factors that may cause actual results to differ materially from such statements include, among others, the following: (1) general national or regional economic conditions, national fiscal or monetary policies, or national or international tariff or trade conditions result in a deterioration of the credit quality of our loan portfolio or diminished demand for the Company's products and services; (2) changes in laws or government rules, or the way in which courts interpret those laws or rules, adversely affect the financial industry generally or the Company's business in particular, or may impose additional costs and regulatory requirements; (3) interest rates change in such a way as to reduce the Company's interest margins and its funding sources; and (4) competitive pressures increase among financial services providers in the Company's northern New England market area or in the financial services industry generally, including pressures from nonbank financial service providers, from increasing consolidation and integration of financial service providers and from changes in technology and delivery systems, and other factors that are listed from time to time in our financial filings with the SEC, including our Forms 10Q and 10K. We disclaim any responsibility to update our forward-looking statements, which are valid only as of the date of this release, should circumstances change.
For more information, contact:
Investor Relations
[email protected]
SOURCE: Community Bancorp. Inc Vermont
View the original press release on ACCESS Newswire
P.M.Smith--AMWN