Cashmere Valley Bank Reports Strong Quarterly Earnings of $8.0 Million, Increases Semi-Annual Dividend to $0.95 Per Share
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
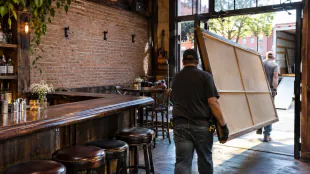 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
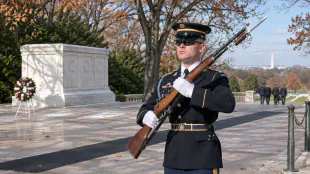 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
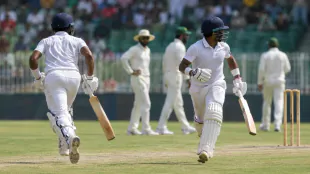 Dhananjaya de Silva guides Sri Lanka to 221-4 against Pakistan
 Delhi gold loses Rs 800 while silver falls Rs 5,000
 Madlanga Commission Deadline Extended to 2027 Amid Calls for Structural Justice Reform
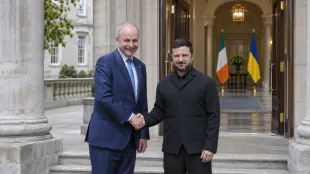 Zelenskyy arrives in Dublin for meetings on Ukraine and peace efforts
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
 US Inflation Broadens as Fed Officials Consider Faster Rate Hikes
 China's Trade Surplus Passes $1 Trillion as Technology Exports Surge
 Bank of England Raises Interest Rate to 4% as Energy Risks Intensify
 China's Factory Inflation Accelerates While Consumer Demand Stays Weak
 Energy Costs Push OECD Inflation Up to 4.5%
 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
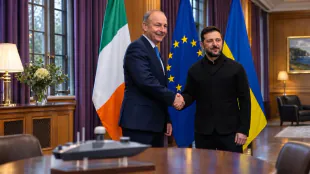 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
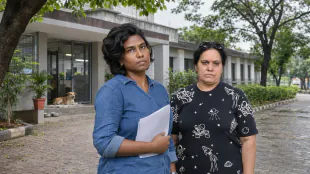 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
CASHMERE, WA / ACCESS Newswire / July 22, 2025 / Cashmere Valley Bank (OTCQX:CSHX) ("Bank"), announced quarterly earnings of $8.0 million for the quarter ended June 30, 2025. Year-to-date earnings totaled $14.4 million as compared to $13.9 million for the six months ended June 30, 2024. Year-to-date diluted earnings per share equaled $3.69, representing an increase of $0.11 per share, or 3.1%. Quarterly diluted earnings per share totaled $2.04 in the second quarter, an increase of $0.33 per share, or 19.3%, from the second quarter 2024.
As of June 30, 2025, deposit balances totaled $1.839 billion, an increase of $1.2 million, or 0.1%, from December 31, 2024. From the same period last year, deposit balances increased $66.7 million, or 3.8%.
"I am very pleased with our financial results," said Greg Oakes, President and CEO. "Our net interest margin is expanding slowly but steadily, which has benefited net income. Loan and deposit growth have been a challenge but we continue to look for opportunities to grow. We are hopeful that we will break ground during the third quarter for our new East Wenatchee location off Grant Rd."
Q2 Highlights
The Bank reported the following statement of condition highlights as of June 30, 2025:
On July 22, 2025, the Bank's Board of Directors declared a dividend of $0.95 per share. The dividend will be payable on August 11, 2025 for shareholders of record on August 1, 2025.
As of June 30, 2025, gross loans totaled $971.7 million, representing a decrease from June 30, 2024 of $43.8 million. Loan totals were adversely affected by significant loan payoffs, the majority of which were in multifamily loans.
Non-interest deposits totaled $397.4 million, or 21.6%, of the Bank's total deposits. Non-interest deposits increased 2.0%, or $7.8 million, from June 30, 2024.
The Bank's year to date return on assets was unchanged from the prior year at 1.37%.
The Bank's return on equity through the first six months of 2025 was 12.26% as compared to 13.48% one year ago. Return on equity has declined as the Bank's capital levels have increased through earnings and a reduction in unrealized losses on available for sale securities.
Total cash, cash equivalents and restricted cash totaled $210.1 million at June 30, 2025, compared to $159.1 million at June 30, 2024. Management has focused on retaining higher cash balances due to the inversion in the treasury yield curve and management's goal to retain excess liquidity.
Investments
The fair value of the Bank's investment portfolio totaled $920.7 million at June 30, 2025, which represented an increase of $135.2 million from June 30, 2024. Held to maturity securities, net of allowance, totaled $126.6 million as of June 30, 2025 compared to $133.4 million as of June 30, 2024. Interest income on the securities portfolio increased from the prior year by $1.8 million to $18.4 million.
A gain on sale of securities of $130,000 was recorded in the first quarter as part of a small repositioning effort within the securities portfolio.
Loans and Credit Quality
Gross loans totaled $971.7 billion as of June 30, 2025 which represented an increase of $9.3 million from December 31, 2024 and a decrease of $43.8 million from June 30, 2024. Since December 31, 2024, commercial and agriculture loans increased $12.2 million, of which $5.8 million in growth originated in Equipment Finance loans, and commercial real estate loans increased $9.7 million. Construction and land development loans decreased $16.0 million and multifamily loans decreased $9.9 million since year end.
At June 30, 2025, the allowance for credit losses on loans (ACL) was 1.24% of gross loans as compared to 1.30% one year ago. The allowance balance was $12.0 million as of June 30, 2025.
Credit quality remains strong with non-performing loans representing 0.41% of gross loans as of June 30, 2025. This is an increase from 0.23% as of June 30, 2024.
Deposits
Total deposits increased by $66.7 million, or 3.8%, from June 30, 2024. From December 31, 2024 to June 30, 2025 total deposits increased $1.2 million, or 0.1%. Non-interest deposits totaled $397.4 million as of June 30, 2025, which represented 21.6% of total deposits. Since June 30, 2024 time deposits have increased $74.1 million to $538.8 million. The Bank's cost of funds has increased one basis point from June 30, 2024 to 1.65%.
Equity
As of June 30, 2025, Tier 1 capital remains strong. Tier 1 capital increased to $290.3 million from $266.7 million at June 30, 2024, due to earnings less dividends paid.
GAAP capital reflected an increase of $31.1 million from June 30, 2024, and an increase of $17.1 million from December 31, 2024. As of June 30, 2024, the Bank's GAAP capital to assets ratio was 11.38% as compared to 10.60% one year ago. GAAP capital levels increased primarily due to Bank earnings and a reduction of $5.6 million in unrealized losses. As of June 30, 2025, the capital effect from unrealized losses on available for sale securities and swaps totaled $53.1 million.
Earnings
Net Interest Income
For the six months ended, June 30, 2025, net interest income totaled $33.0 million compared to $30.9 million in the same period in 2024. Interest income from available for sale and held to maturity securities improved by $1.8 million, and income from cash increased $774,000. Interest income growth was partially offset by an increase in interest expense of $465,000. Loan income increased by $55,000 despite decreasing loan balances.
For the quarter ending June 30, 2025, net interest income increased $580,000 from the quarter ended March 31, 2025. The increase from the prior quarter was due to additional interest income on loans and securities. These increases were partially offset by an increase in borrowing costs and a reduction in income from cash holdings. The increase in borrowings was related to a $50.0 million borrowing and security purchase transaction. Derivatives were used against the borrowings and a portion of the investment purchases to help reduce interest rate risk, while locking in income spreads.
The net interest margin was 3.20% for the first six months of 2025, compared to 3.11% during the first six months of 2024. For the quarter ending June 30, 2025 the net interest margin was 3.23% as compared to 3.17% in the first quarter of 2024.
Non-Interest Income
Non-interest income totaled $11.1 million in the first six months of 2025 as compared to $10.0 million in the first six months of 2024. Insurance commissions and fees from the Bank's subsidiary Mitchell, Reed and Schmitten increased $974,000.
Non-Interest Expense
Non-interest expense totaled $25.4 million in the first six months of 2025, as compared to $23.7 million in the first six months of 2024. Salaries and benefits were the primary drivers of the increase due to investments in personnel along with significant increases in health insurance costs. From the prior quarter non-interest expenses declined $1.0 million due to a decrease in salaries and benefits of $424,000 and a true-up in low income housing losses.
The Bank's efficiency ratio was 58.9% in the first six months of 2025 as compared to 59.2% in the first six months of 2024.
Income tax expense increased from $2.6 million to $2.9 million. The Bank received full credit from its application for the Employee Tax Retention Credit in 2025. Along with the full principal payment the IRS paid interest on the Bank's overpayment of payroll taxes. Interest of $603,000 reduced the Bank's income tax expense. In 2024, $349,000 was reduced from income tax expense during tax provision calculations related to 2023 income tax expense.
About Cashmere Valley Bank
Cashmere Valley Bank was established September 24, 1932 and now has 11 retail offices in Chelan, Douglas, Kittitas and Yakima Counties and a municipal lending office in King County. The Bank provides business and personal banking, commercial lending, insurance services through its subsidiary Mitchell, Reed & Schmitten Insurance, investment services, mortgage services, equipment lease financing, auto and marine dealer financing and municipal lending. The success of Cashmere Valley Bank is the result of maintaining a high level of personal service and controlling expenses so our fees and charges offer our customers the best value available. We remain committed to those principles that we feel are best summarized as, "the little Bank with the big circle of friends."
Forward-Looking Statements
This release may contain certain forward-looking statements that are based on management's current expectations regarding economic, legislative, and regulatory issues that may impact the Bank's earnings in future periods. Forward-looking statements can be identified by the fact that they do not relate strictly to historical or current facts. They often include the words "believe," "expect," "intend," "anticipate," "estimate," "will," "would," "should," "could" or "may." Factors that could cause future results to vary materially from current management expectations include, but are not limited to, general economic conditions, economic uncertainty in the United States and abroad, changes in interest rates, deposit flows, real estate values, costs or effects of acquisitions, competition, changes in accounting principles, policies or guidelines, legislation or regulation, and other economic, competitive, governmental, regulatory and technological factors affecting the Bank's operations. The Bank undertakes no obligation to release publicly the result of any revisions to these forward-looking statements that may be made to reflect events or circumstances after the date of this press release or to reflect the occurrence of unanticipated events.
MEDIA CONTACT:
Greg Oakes, CEO, (509) 782-2092 or
Mike Lundstrom, CFO, (509) 782-5495
Consolidated Balance Sheets
(UNAUDITED)
(Dollars in Thousands) | ||||||
Cashmere Valley Bank and Subsidiary | ||||||
June 30, 2025 | March 31, 2025 | June 30, 2024 | ||||
Assets | ||||||
Cash and Cash Equivalent: | ||||||
Cash & due from banks | $ | 33,936 | $ | 27,192 | $ | 21,484 |
Interest bearing deposits | 172,379 | 156,653 | 134,051 | |||
Fed funds sold | 3,742 | 2,342 | 3,578 | |||
Total Cash and Cash Equivalent | 210,057 | 186,187 | 159,113 | |||
Securities available for sale | 794,155 | 750,761 | 652,136 | |||
Securities held to maturity, net of allowance for credit losses of $15, $15 and $18, respectively | 126,587 | 128,589 | 133,434 | |||
Federal Home Loan Bank stock, at cost | 5,053 | 2,848 | 2,936 | |||
Loans held for sale | 504 | 7 | 673 | |||
Loans | 971,669 | 967,398 | 1,015,444 | |||
Allowance for credit losses | (12,019 | ) | (12,391 | ) | (13,198 | ) |
Net loans | 959,650 | 955,007 | 1,002,246 | |||
Premises and equipment | 19,715 | 19,251 | 20,097 | |||
Accrued interest receivable | 8,721 | 8,842 | 9,416 | |||
Other real estate and foreclosed assets | 97 | 97 | 97 | |||
Bank Owned Life Insurance | 28,080 | 27,862 | 27,212 | |||
Goodwill | 7,579 | 7,579 | 7,579 | |||
Intangibles, net | 2,367 | 2,562 | 3,152 | |||
Mortgage servicing rights | 2,386 | 2,406 | 2,477 | |||
Net deferred tax assets | 16,554 | 16,780 | 18,394 | |||
Other assets | 10,023 | 13,649 | 14,404 | |||
Total assets | $ | 2,191,528 | $ | 2,122,427 | $ | 2,053,366 |
Liabilities and Shareholders' Equity | ||||||
Liabilities | ||||||
Deposits: | ||||||
Non-interest bearing demand | $ | 397,399 | $ | 386,886 | $ | 389,580 |
Savings and interest-bearing demand | 902,986 | 921,796 | 918,205 | |||
Time | 538,795 | 521,007 | 464,688 | |||
Total deposits | 1,839,180 | 1,829,689 | 1,772,473 | |||
Accrued interest payable | 2,963 | 2,881 | 2,642 | |||
Borrowings | 84,000 | 35,000 | 48,322 | |||
Other liabilities | 16,076 | 14,627 | 11,725 | |||
Total liabilities | 1,942,219 | 1,882,197 | 1,835,162 | |||
Shareholders' Equity | ||||||
Common stock (no par value); authorized 10,000,000 shares; | ||||||
Issued and outstanding: 6/30/2025 -- 3,900,683 ; 3/31/2025 -- 3,897,994 ; 6/30/2024 -- 3,890,990 | -- | -- | -- | |||
Additional paid-in capital | 5,789 | 5,608 | 5,184 | |||
Treasury stock | (16,784 | ) | (16,784 | ) | (16,784 | ) |
Retained Earnings | 312,542 | 304,544 | 290,710 | |||
Other comprehensive income | (53,095 | ) | (53,947 | ) | (61,360 | ) |
Total Cashmere Valley Bank shareholders' equity | 248,452 | 239,421 | 217,750 | |||
Noncontrolling interest | 857 | 809 | 454 | |||
Total shareholders' equity | 249,309 | 240,230 | 218,204 | |||
Total liabilities and shareholders' equity | $ | 2,191,528 | $ | 2,122,427 | $ | 2,053,366 |
Quarterly Consolidated Statements of Income
(UNAUDITED)
(Dollars in Thousands) | ||||||||||
Cashmere Valley Bank & Subsidiary | ||||||||||
For the quarters ended, | ||||||||||
June 30, 2025 | March 31, 2025 | June 30, 2024 | ||||||||
Interest Income | ||||||||||
Loans and leases | $ | 13,506 | $ | 12,834 | $ | 13,264 | ||||
Fed funds sold and deposits at other financial institutions | 1,573 | 1,958 | 1,458 | |||||||
Securities available for sale: | ||||||||||
Taxable | 8,375 | 7,816 | 7,145 | |||||||
Tax-exempt | 356 | 332 | 344 | |||||||
Securities held to maturty: | ||||||||||
Taxable | 748 | 762 | 786 | |||||||
Tax-exempt | 25 | 24 | 47 | |||||||
Total interest income | 24,583 | 23,726 | 23,044 | |||||||
Interest Expense | ||||||||||
Deposits | 7,041 | 7,111 | 7,166 | |||||||
Borrowings | 748 | 401 | 612 | |||||||
Total interest expense | 7,789 | 7,512 | 7,778 | |||||||
Net interest income | 16,794 | 16,214 | 15,266 | |||||||
Provision for Credit Losses | 517 | 761 | 657 | |||||||
Net interest income after provision for credit losses | 16,277 | 15,453 | 14,609 | |||||||
Non-Interest Income | ||||||||||
Service charges on deposit accounts | 536 | 496 | 502 | |||||||
Mortgage banking operations | 429 | 351 | 463 | |||||||
Net gain (loss) on sales of securities available for sale | -- | 130 | -- | |||||||
Brokerage commissions | 238 | 327 | 349 | |||||||
Insurance commissions and fees | 2,482 | 2,667 | 2,225 | |||||||
Net interchange income | 1,024 | 1,138 | 1,131 | |||||||
Earnings from Bank Owned Life Insurance | 218 | 215 | 203 | |||||||
Dividends from correspondent banks | 101 | 109 | 59 | |||||||
Other | 323 | 288 | 309 | |||||||
Total non-interest income | 5,351 | 5,721 | 5,241 | |||||||
Non-Interest Expense | ||||||||||
Salaries and employee benefits | 7,334 | 7,758 | 6,537 | |||||||
Occupancy and equipment | 832 | 868 | 855 | |||||||
Audits and examinations | 190 | 247 | 195 | |||||||
State and local business and occupation taxes | 383 | 358 | 239 | |||||||
FDIC insurance & WA state assessments | 256 | 268 | 224 | |||||||
Legal and professional fees | 330 | 247 | 303 | |||||||
Check losses and charge-offs | 110 | 118 | 148 | |||||||
Low-income housing investment losses | (315 | ) | 158 | 169 | ||||||
Data processing | 1,738 | 1,768 | 1,578 | |||||||
Product delivery | 269 | 364 | 369 | |||||||
Other | 1,077 | 1,059 | 1,087 | |||||||
Total non-interest expense | 12,204 | 13,213 | 11,704 | |||||||
Income before income taxes | 9,424 | 7,961 | 8,146 | |||||||
Income Taxes | 1,379 | 1,502 | 1,472 | |||||||
Net income | $ | 8,045 | $ | 6,459 | $ | 6,674 | ||||
Net income attributable to noncontrolling interest | 47 | 48 | 27 | |||||||
Net income attributable to Cashmere Valley Bank | $ | 7,998 | $ | 6,411 | $ | 6,647 | ||||
Earnings Per Share | ||||||||||
Basic | $ | 2.05 | $ | 1.65 | $ | 1.71 | ||||
Diluted | $ | 2.04 | $ | 1.64 | $ | 1.71 | ||||
Year-to-Date Consolidated Statements of Income
(UNAUDITED)
(Dollars in Thousands) | ||||||
Cashmere Valley Bank & Subsidiary | ||||||
For the six months ended, | ||||||
June 30, 2025 | June 30, 2024 | |||||
Interest Income | ||||||
Loans and leases | $ | 26,340 | $ | 26,285 | ||
Fed funds sold and deposits at other financial institutions | 3,530 | 2,756 | ||||
Securities available for sale: | ||||||
Taxable | 16,191 | 14,365 | ||||
Tax-exempt | 688 | 621 | ||||
Securities held to maturity: | ||||||
Taxable | 1,511 | 1,571 | ||||
Tax-exempt | 49 | 94 | ||||
Total interest income | 48,309 | 45,692 | ||||
Interest Expense | ||||||
Deposits | 14,152 | 13,615 | ||||
Borrowings | 1,149 | 1,221 | ||||
Total interest expense | 15,301 | 14,836 | ||||
Net interest income | 33,008 | 30,856 | ||||
Provision for Credit Losses | 1,278 | 602 | ||||
Net interest income after provision for credit losses | 31,730 | 30,254 | ||||
Non-Interest Income | ||||||
Service charges on deposit accounts | 1,033 | 962 | ||||
Mortgage banking operations | 780 | 753 | ||||
Net gain (loss) on sales of securities available for sale | 130 | -- | ||||
Brokerage commissions | 565 | 718 | ||||
Insurance commissions and fees | 5,149 | 4,175 | ||||
Net interchange income | 2,162 | 2,297 | ||||
Earnings from Bank Owned Life Insurance | 433 | 403 | ||||
Dividends from correspondent banks | 210 | 93 | ||||
Other | 610 | 567 | ||||
Total non-interest income | 11,072 | 9,968 | ||||
Non-Interest Expense | ||||||
Salaries and employee benefits | 15,092 | 13,606 | ||||
Occupancy and equipment | 1,700 | 1,735 | ||||
Audits and examinations | 437 | 378 | ||||
State and local business and occupation taxes | 741 | 573 | ||||
FDIC insurance & WA state assessments | 523 | 468 | ||||
Legal and professional fees | 577 | 545 | ||||
Check losses and charge-offs | 228 | 268 | ||||
Low-income housing investment losses | (157 | ) | 169 | |||
Data processing | 3,506 | 3,177 | ||||
Product delivery | 633 | 700 | ||||
Other | 2,137 | 2,079 | ||||
Total non-interest expense | 25,417 | 23,698 | ||||
Income before income taxes | 17,385 | 16,524 | ||||
Income Taxes | 2,881 | 2,565 | ||||
Net income | $ | 14,504 | $ | 13,959 | ||
Net income attributable to noncontrolling interest | 95 | 33 | ||||
Net income attributable to Cashmere Valley Bank | 14,409 | 13,926 | ||||
Earnings Per Share | ||||||
Basic | $ | 3.70 | $ | 3.58 | ||
Diluted | $ | 3.69 | $ | 3.58 | ||
SOURCE: Cashmere Valley Bank
View the original press release on ACCESS Newswire
L.Harper--AMWN