KS Bancorp, Inc. (KSBI) Reports 41% Year to Date Increase in Net Income and Expands Footprint into Nash County, North Carolina
 Below Deck alumnus João Franco and brother arrested after fatal Turkey fight
 Thousands of Urban Homes Left Without High-Speed Internet Due to Broadband Blackspots
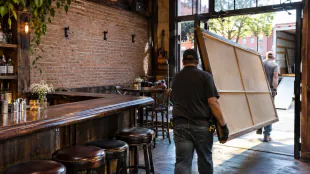 Bunnie XO artwork taken down from Jelly Roll’s Nashville bar
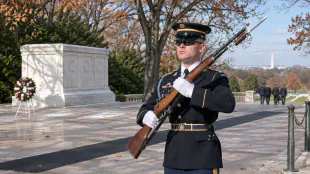 Arlington sentinel rebukes Pete Hegseth entourage for laughter near memorial
 Kylie Jenner employee describes closet ordeal and pepper-spray incident
 Davante Adams injury deepens Los Angeles Rams receiver shortage
 João Franco’s earlier post draws attention after arrest over fatal Turkey brawl
 Alberta Launches $5M Fund for Women’s Neurology Research to Address Gender Gaps
 Dhananjaya de Silva guides Sri Lanka to 221-4 against Pakistan
 Delhi gold loses Rs 800 while silver falls Rs 5,000
 Madlanga Commission Deadline Extended to 2027 Amid Calls for Structural Justice Reform
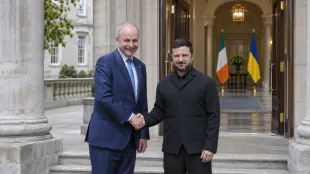 Zelenskyy arrives in Dublin for meetings on Ukraine and peace efforts
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
 US Inflation Broadens as Fed Officials Consider Faster Rate Hikes
 China's Trade Surplus Passes $1 Trillion as Technology Exports Surge
 Bank of England Raises Interest Rate to 4% as Energy Risks Intensify
 China's Factory Inflation Accelerates While Consumer Demand Stays Weak
 Energy Costs Push OECD Inflation Up to 4.5%
 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
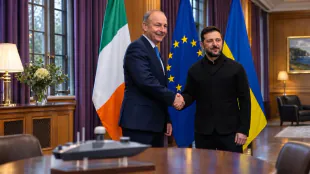 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
SMITHFIELD, NC / ACCESS Newswire / July 23, 2025 / KS Bancorp, Inc. (the "Company") (OTCID:KSBI), parent company of KS Bank, Inc. (the "Bank"), announced unaudited results for the second quarter of 2025.
The Company reported net income of $2.2 million or $2.02 per diluted share for the three months ended June 30, 2025, compared to net income of $1.7 million or $1.50 per diluted share for the three months ended June 30, 2024. This signifies a 35% increase in net income. Year-to-date net income was $4.3 million or $3.89 per diluted share, compared to $3.1 million, or $2.75 per diluted share, for the six months ended June 30, 2024. This signifies a 41% increase in net income year to date.
Net interest income before the provision for credit losses for the three months ended June 30, 2025, increased 22.8%. It was $6.9 million, compared to $5.5 million at June 30, 2024. Non-interest income for the three months ended June 30, 2025, was $1.1 million, compared to $863,000 for the comparable period ended June 30, 2024. Non-interest expense was $4.7 million for the three months ended June 30, 2025, compared to $4.1 million in the comparable period in 2024.
For the six months ending June 30, 2025, net interest income before the provision for credit losses was $13.2 million, compared to $10.6 million for the six months ending June 30, 2024, which was a 28.7% increase. Non-interest income was $2.0 million for the six months ending June 30, 2025, compared to $1.7 million for the same period ended June 30, 2024. For the six months ended June 30, 2025, non-interest expenses were $9.0 million, compared to $8.1 million for the same period ending June 30, 2024.
The Company's unaudited consolidated total assets increased by $36.4 million to $727.3 million as of June 30, 2025, compared to $690.9 million as of December 31, 2024. Net loan balances increased by $33.4 million to $587.9 million on June 30, 2025, compared to $554.5 million on December 31, 2024. The Company's investment securities totaled $94.5 million as of June 30, 2025, compared to $95.9 million as of December 31, 2024. Total deposits increased $43.5 million to $661.7 million as of June 30, 2025, compared to $618.2 million as of December 31, 2024. The increase in deposits included a $34.2 million increase or 6.0% in core deposits. For the six months ended June 30, 2025, short-term borrowings decreased $11.1 million. Total stockholders' equity increased $3.4 million to $48.7 million as of June 30, 2025, from $45.3 million as of December 31, 2024.
As of June 30, 2025, nonperforming assets consisted of nonaccrual loans totaling $77,000 and foreclosed real estate with a value of $500,000, representing less than 0.10% of the Company's total assets. The allowance for credit losses as of June 30, 2025, totaled $4.7 million, or 0.79% of total loans.
Commenting on the second quarter results, Earl W. Worley, Jr., President and CEO of the Company, stated, "We are pleased with our continued momentum through the first half of 2025, highlighted by a 35% increase in second quarter net income compared to the prior year. This strong performance reflects steady loan growth, disciplined expense control, and a 6% rise in core deposits, all of which reinforce the strength of our balance sheet and the dedication of our team. In addition to our financial results, we were proud to open our eleventh full-service branch in Bailey, North Carolina, our first in Nash County, North Carolina. The community's warm reception affirms the value of our relationship-driven approach to banking.
As we move into the second half of the year, we remain cautiously optimistic. While our fundamentals are sound and our strategic initiatives are progressing well, we recognize that ongoing economic uncertainty and future actions by the Federal Reserve may impact both interest rate trends and customer behavior. We will continue to manage risk carefully, remain flexible in our approach, and focus on delivering long-term value to our customers, communities, and shareholders."
In addition, the Company announced today that its Board of Directors has declared a quarterly dividend of $0.28 per share for stockholders of record as of August 1, 2025, with payment to be made on August 11, 2025.
KS Bank continues to be well-capitalized according to regulatory standards, with a Community Bank Leverage Ratio of 9.22% as of June 30, 2025, compared to 9.24% as of December 31, 2024.
KS Bancorp, Inc. is a Smithfield, North Carolina-based single-bank holding company. KS Bank, Inc., a state-chartered savings bank, is KS Bancorp's sole subsidiary. The Bank is a full-service community bank that has served the citizens of eastern North Carolina since 1924. The Bank offers a broad range of personal and business banking products and services, as well as mortgage and trust services. Eleven full-service branches are located in Kenly, Selma, Clayton, Garner, Goldsboro, Wilson, Wendell, Smithfield, Four Oaks, Dunn, and Bailey, North Carolina. For more information, visit www.ksbankinc.com.
This release contains certain forward-looking statements with respect to the financial condition, results of operations and business of the Company. These forward-looking statements involve risks and uncertainties and are based on the beliefs and assumptions of management of the Company and on the information available to management at the time that these disclosures were prepared. These statements can be identified by the use of words like "expect," "anticipate," "estimate" and "believe," variations of these words and other similar expressions. Readers should not place undue reliance on forward-looking statements as a number of important factors could cause actual results to differ materially from those in the forward-looking statements. The Company undertakes no obligation to update any forward-looking statements.
Contact: Earl W. Worley, Jr. | Regina J Smith |
KS Bancorp, Inc. and Subsidiary | ||||||||
Consolidated Statements of Financial Condition | ||||||||
June 30, 2025 | December 31, | |||||||
(unaudited) | 2024* | |||||||
(Dollars in thousands) | ||||||||
ASSETS | ||||||||
Cash and due from banks: | ||||||||
Interest-earning | $ | 13,771 | $ | 10,627 | ||||
Noninterest-earning | 4,806 | 4,897 | ||||||
Time Deposit | 723 | 523 | ||||||
Investment securities available for sale, at fair value | 94,545 | 95,946 | ||||||
Federal Home Loan Bank stock, at cost | 498 | 469 | ||||||
Loans | 592,595 | 558,779 | ||||||
Less allowance for loan losses | (4,667 | ) | (4,259 | ) | ||||
Net loans | 587,928 | 554,520 | ||||||
Accrued interest receivable | 2,813 | 2,655 | ||||||
Foreclosed assets, net | 500 | - | ||||||
Property and equipment, net | 12,334 | 12,231 | ||||||
Other assets | 9,342 | 8,981 | ||||||
Total assets | $ | 727,260 | $ | 690,849 | ||||
LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||
Liabilities | ||||||||
Deposits | $ | 661,690 | $ | 618,156 | ||||
Short-term borrowings | $ | - | $ | 11,144 | ||||
Long-term borrowings | 11,248 | 11,248 | ||||||
Accrued interest payable | 322 | 323 | ||||||
Accrued expenses and other liabilities | 5,284 | 4,675 | ||||||
Total liabilities | 678,544 | 645,546 | ||||||
Stockholder's Equity: | ||||||||
Preferred stock, no par value, 500,000 shares authorized; none issued and outstanding | ||||||||
Common stock, no par value, 3,500,000 shares authorized; 1,107,776 shares issued and outstanding at June, 2025 and December 31, 2024, respectively | 1,359 | 1,359 | ||||||
Retained earnings, substantially restricted | 56,392 | 52,675 | ||||||
Accumulated other comprehensive Income (loss) | (9,035 | ) | (8,731 | ) | ||||
Total stockholders' equity | 48,716 | 45,303 | ||||||
Total liabilities and stockholders' equity | $ | 727,260 | $ | 690,849 | ||||
* Derived from audited financial statements | ||||||||
KS Bancorp, Inc and Subsidiary | ||||||||||||||||
Consolidated Statement of Income | ||||||||||||||||
Three Months Ended | Six Months Ended | |||||||||||||||
30-Jun | 30-Jun | |||||||||||||||
2025 | 2024 | 2025 | 2024 | |||||||||||||
(In thousands, except per share data) | ||||||||||||||||
Interest and dividend income: | ||||||||||||||||
Loans | $ | 9,604 | $ | 7,784 | 18,560 | 15,237 | ||||||||||
Investment securities | ||||||||||||||||
Taxable | 575 | 513 | 1,135 | 1,013 | ||||||||||||
Tax-exempt | 180 | 202 | 361 | 404 | ||||||||||||
Dividends | 6 | 6 | 12 | 12 | ||||||||||||
Interest-bearing deposits | 212 | 277 | 343 | 397 | ||||||||||||
Total interest and dividend income | 10,577 | 8,782 | 20,411 | 17,063 | ||||||||||||
Interest expense: | ||||||||||||||||
Deposits | 3,510 | 3,132 | 6,824 | 5,938 | ||||||||||||
Borrowings | 166 | 192 | 354 | 565 | ||||||||||||
Total interest expense | 3,676 | 3,324 | 7,178 | 6,503 | ||||||||||||
Net interest income | 6,901 | 5,458 | 13,233 | 10,560 | ||||||||||||
Provision for loan losses | 338 | 114 | 533 | 283 | ||||||||||||
Net interest income after | ||||||||||||||||
provision for loan losses | 6,563 | 5,344 | 12,700 | 10,277 | ||||||||||||
Noninterest income: | ||||||||||||||||
Service charges on deposit accounts | 365 | 320 | 690 | 634 | ||||||||||||
Fees from trust services | 371 | 334 | 742 | 651 | ||||||||||||
Other income | 324 | 209 | 540 | 407 | ||||||||||||
Total noninterest income | 1,060 | 863 | 1,972 | 1,692 | ||||||||||||
Noninterest expenses: | ||||||||||||||||
Compensation and benefits | 2,883 | 2,513 | 5,552 | 5,015 | ||||||||||||
Occupancy and equipment | 611 | 596 | 1,271 | 1,153 | ||||||||||||
Data processing & outside service fees | 291 | 244 | 555 | 479 | ||||||||||||
Advertising | 76 | 64 | 129 | 110 | ||||||||||||
Other | 806 | 712 | 1,537 | 1,354 | ||||||||||||
Total noninterest expenses | 4,667 | 4,129 | 9,044 | 8,111 | ||||||||||||
Income before income taxes | 2,956 | 2,078 | 5,628 | 3,858 | ||||||||||||
Income tax | 715 | 421 | 1,312 | 815 | ||||||||||||
Net income | $ | 2,241 | $ | 1,657 | $ | 4,316 | $ | 3,043 | ||||||||
Basic and Diluted earnings per share | $ | 2.02 | $ | 1.50 | $ | 3.89 | $ | 2.75 | ||||||||
SOURCE: KS Bancorp, Inc.
View the original press release on ACCESS Newswire
F.Schneider--AMWN