KS Bancorp, Inc. (KSBI) Reports Strong Growth in Assets, Loans, Deposits and Equity for the First Half of 2026
 Samsung expects 780% quarterly operating profit jump on AI boom
 Guardians survive with 9-3 win over White Sox
 Saudi Arabia says 3 dead at airports after Houthis claim attacks
 Stocks slide as oil sees volatile trading day over Iran war fears
 Microsoft pushes AI vision with new, expensive Surface laptop
 Five children among 28 killed in Russian strikes on Ukraine
 Odell Beckham Jr signs with Minnesota Vikings
 Saudi Arabia says three dead at airports after Houthis claim attacks
 Trump plans to turn Florida golf course into presidential retreat
 WHO says cannot conduct full risk assessment on Russia plague reports
 After botched execution, US woman is awake and shackled to bed
 New Zealand fly-half Mo'unga ruled out of Australia Tests
 Protests in major Turkish city after mayor defects to Erdogan party
 Climate change strips island's title of largest penguin colony: study
 Rubio says West must choose between national power or decline
 Russia's plague scare: What we know
 French luxury giant to fund redevelopment of two Paris streets: city hall
 Trump wants to turn Florida golf course into presidential retreat
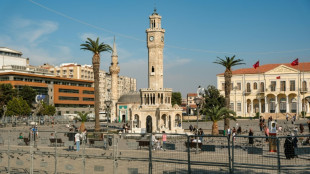 Mayor of Turkish opposition stronghold defects to Erdogan party
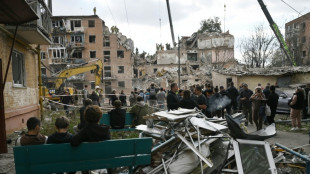 Children among heavy casualties in Ukraine after Russian strikes
 Court orders German ex-spy chief kept in jail after spying, treason arrest
 Guinea caps bottled water prices after sachets banned
 Spared, married, hanged: the last weeks of Iranian protester Alireza Sepahi
 Nobel physics winner's pride at pioneering AI role
 IMF preparing El Nino assistance, concerned about AI bubble burst: chief to AFP
SMITHFIELD, NC / ACCESS Newswire / July 24, 2026 / KS Bancorp, Inc. (the "Company") (OTCID:KSBI), parent company of KS Bank, Inc. (the "Bank"), reported strong financial results for the second quarter and the year ended June 30, 2026.
Financial Highlights
Net income of $2.9 million for the second quarter of 2026.
Earnings per share of $2.57, compared to $2.02 in the prior‑year quarter.
Net interest income before the provision increased 19.1% year over year to $8.2 million.
Net income increased 26.1% year over year to $5.4 million.
Total assets increased to $875.5 million, up $52.9 million, or 6.4%, from December 31, 2025.
Net loans grew to $714.3 million, an increase of $50.1 million, or 7.5%, from December 31, 2025.
Deposits totaled $784.1 million, an increase of $34.5 million, or 4.6%, from December 31, 2025.
Income Statement Review
The Company reported net income totaled $2.9 million, or $2.57 per diluted share, for the three months ended June 30, 2026, compared to $2.2 million, or $2.02 per diluted share, for the same period in 2025. The increase was driven primarily by strong growth in net interest income, partially offset by higher operating expenses reflecting continued investment in personnel, technology, and infrastructure. Net interest income increased to $8.2 million, up $1.3 million, or 19.1%, from the second quarter of 2025. The provision for credit losses expensed was $285 thousand for the quarter, reflecting continued loan growth and management's assessment of current economic conditions and portfolio credit quality. Noninterest income remained stable at $1.1 million for the three months ended June 30, 2026 and June 30, 2025. Noninterest expense increased to $5.4 million, compared to $4.7 million in the second quarter of 2025, primarily due to compensation and benefits, occupancy costs, and technology‑related expenses.
Net income totaled $5.4 million, or $4.91 per diluted share, for the six months ended June 30, 2026, compared to $4.3 million, or $3.89 per diluted share, for the same period in 2025. For the six months ended June 30, 2026, net interest income before the provision for credit losses was $16.0 million, compared to $13.2 million for the six months ended June 30, 2025, representing a 21.0% increase. Noninterest income was $2.1 million for the six months ended June 30, 2026, compared to $2.0 million for the same period ended June 30, 2025. For the six months ended June 30, 2026, non-interest expenses were $10.5 million, compared to $9.0 million for the same period ended June 30, 2025.
Balance Sheet Performance
As of June 30, 2026, the Company's unaudited consolidated total assets were $875.5 million, an increase of $52.9 million from $822.6 million at December 31, 2025. Driven by continued loan demand across the Company's branch network, net loan balances grew $50.1 million to $714.3 million, compared to $664.2 million at December 31, 2025. The Company's investment securities totaled $94.5 million at June 30, 2026, compared to $95.2 million at December 31, 2025.
Total deposits increased to $784.1 million at quarter‑end, reflecting strong core deposit growth. Liquidity remained solid, with $38.7 million in cash and due from banks. Long-term borrowings increased $3.0 million to $14.2 million at June 30, 2026, compared to $11.2 million at December 31, 2025. The increase was due to a $3 million subordinated debt issuance in June 2026.
Stockholders' equity totaled $60.7 million, compared to $55.8 million at year‑end, driven by quarterly earnings and a $3 million downstream of capital to the Bank.
Management Commentary
Commenting on the second quarter results, Earl W. Worley, Jr., President and CEO of the Company, stated, "We are very pleased with our performance during the first half of 2026, which reflects the continued execution of our long-term strategic plan and the strength of our relationship banking model. Our strong earnings growth was driven by disciplined balance sheet management, continued expansion of net interest income, and the outstanding efforts of our employees to build lasting customer relationships throughout the markets we serve.
During the quarter, we successfully completed a $3.0 million private placement of subordinated debt, further strengthening our capital position and providing additional financial flexibility to support future growth initiatives. This transaction reflects the confidence investors have in KS Bank and positions us well to capitalize on opportunities as they arise.
Reflecting the Company's continued financial strength and confidence in our future, our Board of Directors approved a 13.3% increase in the quarterly cash dividend to $0.34 per share. We believe our shareholders are among our most important stakeholders, and we are pleased that our continued growth and strong financial performance have enabled us to reward their confidence and long-term investment while maintaining the capital necessary to support future growth.
We remain committed to disciplined growth, maintaining exceptional asset quality, investing in our people and technology, and delivering the personalized service that has defined KS Bank for more than 102 years.
While our first-half of 2026 results were encouraging, we recognize that the economic outlook remains uncertain. Future financial performance will continue to be influenced by the interest rate environment, Federal Reserve policy decisions, competitive pricing pressures for deposits, and broader market volatility. Regardless of these external factors, we remain committed to prudent risk management, strong capital and liquidity, and creating long-term value for our shareholders while serving the financial needs of our customers and communities."
In addition, the Company announced today that its Board of Directors has declared a 13.3% increase in quarterly dividends of $0.34 per share for stockholders of record as of July 27, 2026, with payment to be made on August 6, 2026.
KS Bank continues to be well-capitalized according to regulatory standards, with a Community Bank Leverage Ratio of 9.01% as of June 30, 2026, compared to 9.02% as of December 31, 2025. Effective July 1, 2026, federal bank regulatory agencies finalized the rule to modify the Community Bank Leverage Ratio from nine percent to eight percent.
KS Bancorp, Inc. is a Smithfield, North Carolina-based single-bank holding company. KS Bank, Inc., a state-chartered savings bank, is KS Bancorp's sole subsidiary. The Bank is a full-service community bank that has served the citizens of eastern North Carolina since 1924. The Bank offers a broad range of personal and business banking products and services, as well as mortgage and trust services. Eleven full-service branches are located in Kenly, Selma, Clayton, Garner, Goldsboro, Wilson, Wendell, Smithfield, Four Oaks, Dunn, and Bailey, North Carolina. For more information, visit www.ksbankinc.com.
This release contains certain forward-looking statements with respect to the financial condition, results of operations and business of the Company. These forward-looking statements involve risks and uncertainties and are based on the beliefs and assumptions of management of the Company and on the information available to management at the time that these disclosures were prepared. These statements can be identified by the use of words like "expect," "anticipate," "estimate" and "believe," variations of these words and other similar expressions. Readers should not place undue reliance on forward-looking statements as a number of important factors could cause actual results to differ materially from those in the forward-looking statements. The Company undertakes no obligation to update any forward-looking statements.
Contact: Earl W. Worley, Jr. | Regina J Smith |
KS Bancorp, Inc. and Subsidiary
Consolidated Statements of Financial Condition
June 30, 2026 | December 31, | ||||
(unaudited) | 2025* | ||||
(Dollars in thousands) | |||||
ASSETS | |||||
Cash and due from banks: | |||||
Interest-earning | $ | 31,615 | $ | 30,244 | |
Noninterest-earning | 6,287 | 5,259 | |||
Time Deposit | 746 | 746 | |||
Investment securities available for sale, at fair value | 94,515 | 95,158 | |||
Federal Home Loan Bank stock, at cost | 1,065 | 498 | |||
Loans | 719,789 | 669,267 | |||
Less allowance for loan losses | (5,482 | ) | (5,062 | ) | |
Net loans | 714,307 | 664,205 | |||
Accrued interest receivable | 3,254 | 3,078 | |||
Foreclosed assets, net | 450 | 500 | |||
Property and equipment, net | 14,021 | 13,603 | |||
Other assets | 9,214 | 9,312 | |||
Total assets | $ | 875,474 | $ | 822,603 | |
LIABILITIES AND STOCKHOLDERS' EQUITY | |||||
Liabilities | |||||
Deposits | $ | 784,100 | $ | 749,601 | |
Short-term borrowings | 10,000 | - | |||
Long-term borrowings | 14,248 | 11,248 | |||
Accrued interest payable | 371 | 405 | |||
Accrued expenses and other liabilities | 6,067 | 5,505 | |||
Total liabilities | 814,786 | 766,759 | |||
Stockholder's Equity: | |||||
Preferred stock, no par value, 500,000 shares authorized; none issued and outstanding | |||||
Common stock, no par value, 3,500,000 shares authorized; 1,107,776 shares issued and outstanding at June, 2026 and December 31, 2025, respectively | 1,359 | 1,359 | |||
Retained earnings, substantially restricted | 65,591 | 60,814 | |||
Accumulated other comprehensive Income (loss) | (6,262 | ) | (6,329 | ) | |
Total stockholders' equity | 60,688 | 55,844 | |||
Total liabilities and stockholders' equity | $ | 875,474 | $ | 822,603 | |
* Derived from audited financial statements
KS Bancorp, Inc. and Subsidiary
Consolidated Statement of Income
Three Months Ended | Six Months Ended | ||||||||
30-Jun | 30-Jun | ||||||||
2026 | 2025 | 2026 | 2025 | ||||||
(In thousands, except per share data) | |||||||||
Interest and dividend income: | |||||||||
Loans | $ | 11,582 | $ | 9,604 | $ | 22,708 | $ | 18,560 | |
Investment securities | |||||||||
Taxable | 622 | 575 | 1,242 | 1,135 | |||||
Tax-exempt | 182 | 180 | 367 | 361 | |||||
Dividends | 8 | 6 | 15 | 12 | |||||
Interest-bearing deposits | 410 | 212 | 824 | 343 | |||||
Total interest and dividend income | 12,804 | 10,577 | 25,156 | 20,411 | |||||
Interest expense: | |||||||||
Deposits | 4,426 | 3,510 | 8,828 | 6,824 | |||||
Borrowings | 161 | 166 | 314 | 354 | |||||
Total interest expense | 4,587 | 3,676 | 9,142 | 7,178 | |||||
Net interest income | 8,217 | 6,901 | 16,014 | 13,233 | |||||
Provision for loan losses | 285 | 338 | 664 | 533 | |||||
Net interest income after | |||||||||
provision for loan losses | 7,932 | 6,563 | 15,350 | 12,700 | |||||
Noninterest income: | |||||||||
Service charges on deposit accounts | 394 | 365 | 761 | 690 | |||||
Fees from trust services | 460 | 371 | 903 | 742 | |||||
Other income | 239 | 324 | 426 | 540 | |||||
Total noninterest income | 1,093 | 1,060 | 2,090 | 1,972 | |||||
Noninterest expenses: | |||||||||
Compensation and benefits | 3,204 | 2,883 | 6,284 | 5,552 | |||||
Occupancy and equipment | 749 | 611 | 1,468 | 1,271 | |||||
Data processing & outside service fees | 357 | 291 | 692 | 555 | |||||
Advertising | 63 | 76 | 114 | 129 | |||||
Other | 995 | 806 | 1,906 | 1,537 | |||||
Total noninterest expenses | 5,368 | 4,667 | 10,464 | 9,044 | |||||
Income before income taxes | 3,657 | 2,956 | 6,976 | 5,628 | |||||
Income tax | 806 | 715 | 1,535 | 1,312 | |||||
Net income | $ | 2,851 | $ | 2,241 | $ | 5,441 | $ | 4,316 | |
Basic and Diluted earnings per share | $ | 2.57 | $ | 2.02 | $ | 4.91 | $ | 3.89 | |
SOURCE: KS Bancorp, Inc.
View the original press release on ACCESS Newswire
H.E.Young--AMWN