Commercial Bancgroup, Inc. Announces Quarterly Cash Dividend
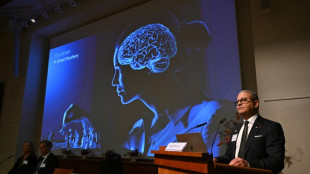
 American Nobel laureate in medicine hopes to illuminate the brain
 Trump approves firing squad for convicted US military base shooter
 Grappling with 'homework scams,' US universities shun AI detectors
 Separatists win Quebec election in test for Canada PM
 Leaders visit Pacific atoll at frontline of climate change
 Yemen's Houthis claim striking Riyadh airport, other Saudi sites
 Best-selling British author Jeffrey Archer dies aged 86
 Military plane crash kills 32 in Nigeria
 Olise powers France to win over Belgium in Nations League
 High-flying Blazy turns to birdlife at Chanel
 Riyadh's allies pledge troops as Yemen, Saudi Arabia attack Houthis
 Clashes erupt outside Kosovo parliament over war crimes court
 Milan's Saelemaekers suffers ankle setback, faces lengthy spell out
 Rubio arrives in Iceland to push for greater US presence in Arctic
 Putin allows Italy's UniCredit to sell part of Russian business
 Djokovic into China Open final as Medvedev out for hitting fan with ball
 ICC unseals arrest warrants for Taliban education ministers
 Modric hopes fans back Croatia against Spain after England shame
 Bolsonaro rides right-wing surge into Brazil's election runoff
 Turkey blocks X account of British reporter
 Ukraine says using AI robot guns to shoot down new Russian drones
 At Oct 7 memorial, Netanyahu says will be no Hamas rule in Gaza
 Ukraine blames Russia for deadly sinking of Turkish ship in Black Sea
 UN rights council slams Taliban's 'oppression' of women
 Norway eyes partial ban of smart glasses
HARROGATE, TN / ACCESS Newswire / July 27, 2026 / Commercial Bancgroup, Inc. ("Commercial") (NASDAQ:CBK), the parent company of Commercial Bank, announced today that the board of directors of Commercial declared a quarterly cash dividend of $0.12 per share of Commercial common stock payable on September 30, 2026, to shareholders of record as of the close of business on September 15, 2026. This cash dividend represents a $0.02, or 20.0%, increase over the $0.10 cash dividend paid during the second quarter of 2026.
"Our consistent profitability and performance metrics have enabled us to support growth and return value to shareholders. This dividend increase reflects our confidence in the long-term earnings and growth outlook of Commercial Bancgroup, Inc. and our commitment to our shareholders," said Terry Lee, CEO and President of Commercial.
About Commercial Bancgroup, Inc.
Commercial Bancgroup, Inc. is a bank holding company headquartered in Harrogate, Tennessee. Through our wholly owned subsidiary, Commercial Bank, a Tennessee state-chartered bank, we offer a suite of traditional consumer and commercial banking products and services to businesses and individuals in select markets in Kentucky, North Carolina, and Tennessee. More information about Commercial Bancgroup, Inc. can be found on its website at ir.cbtn.com.
Contacts
Philip J. Metheny
Sr. Executive Vice President, Chief Financial Officer
Commercial Bancgroup, Inc.
[email protected]
423-869-5151
Roger Mobley
Executive Vice President, Chief Financial Officer
Commercial Bank
[email protected]
704-648-0185
Forward-Looking Statements
This press release contains statements that constitute "forward-looking statements" within the meaning of the U.S. federal securities laws. The statements in this press release that are not purely historical facts are forward-looking statements. These forward-looking statements are generally identified by the use of forward-looking terminology, including the terms "anticipate," "believe," "could," "estimate," "expect," "intend," "may," "plan," "potential," "predict," "project," "should," "target," "will," "would" and, in each case, their negative or other variations or comparable terminology and expressions. You should not place undue reliance on these forward-looking statements as actual future results may differ materially from those expressed or implied by any forward-looking statement. These forward-looking statements are subject to known and unknown risks, uncertainties and other factors that could cause actual results to differ materially from those expressed in any forward-looking statements, including but not limited to: (1) business and economic conditions nationally, regionally and in our target markets, particularly in Kentucky, North Carolina and Tennessee and the particular geographic areas in which we operate; (2) the level of, or changes in the level of, interest rates and inflation, including the effects thereof on our earnings and financial condition and the market value of our investment securities and loan portfolios; (3) the concentration of our loan portfolio in real estate loans and changes in the prices, values and sales volumes of commercial and residential real estate; (4) the concentration of our business within our geographic areas of operation in Kentucky, North Carolina and Tennessee and neighboring markets; (5) credit and lending risks associated with our commercial real estate, commercial, and construction and land development loan portfolios; (6) risks associated with our focus on lending to small and medium-sized businesses; (7) our ability to maintain important deposit customer relationships, maintain our reputation or otherwise avoid liquidity risks; (8) changes in demand for our products and services; (9) the failure of assumptions and estimates underlying the establishment of allowances for possible credit losses and other asset impairments, valuations of assets and liabilities and other calculations; (10) the sufficiency of our capital, including sources of such capital and the extent to which capital may be used or required; (11) our inability to maintain a "satisfactory" rating under the Community Reinvestment Act; (12) the risk that our cost of funding could increase in the event we are unable to continue to attract stable, low-cost deposits or maintain or reduce our cost of deposits; (13) our inability to raise necessary capital to fund our growth strategy and operations or to meet increased required minimum regulatory capital levels; (14) our ability to execute and prudently manage our growth and execute our business strategy, including expansionary activities; (15) the composition of and changes in our management team and our ability to attract, incentivize and retain key personnel; (16) the effects of competition from a wide variety of local, regional, national and other providers of financial, investment, trust and other wealth management services and insurance services, including the disruptive effects of financial technology and other competitors who are not subject to the same regulations as the Company and the Bank; (17) the deterioration of our asset quality or the value of collateral securing loans; (18) changes in accounting standards; (19) the effectiveness of our risk management framework, including internal controls; (20) severe weather, natural disasters, pandemics, epidemics, acts of war, terrorism, or other external events, such as the transition risk associated with climate change, and other matters beyond our control; (21) changes in technology or products that may be more difficult, more costly, or less effective than anticipated; (22) the risks of acquisitions and other expansionary activities, including without limitation our ability to identify and consummate transactions with potential future acquisition candidates, the time and costs associated with pursuing such transactions, our ability to successfully integrate operations as part of such transactions and our ability, and possible failures, to achieve expected gains, revenue growth, expense savings and/or other synergies from such transactions; (23) our ability to maintain our historical rate of growth; (24) failure to keep pace with technological change or difficulties when implementing new technologies; (25) systems failures or interruptions involving our risk management framework, our information technology and telecommunications systems or third-party service providers; (26) our ability to identify and address unauthorized data access, cyber-crime and other threats to data security and customer privacy; (27) our compliance with governmental and regulatory requirements, including the Bank Holding Company Act of 1956, as amended, and other laws relating to banking, consumer protection, securities and tax matters, and our ability to maintain licenses required in connection with mortgage origination, sale and servicing operations; (28) compliance with the Bank Secrecy Act of 1970, Office of Foreign Assets Control rules and anti-money laundering laws and regulations; (29) governmental monetary and fiscal policies; (30) changes in laws, rules, or regulations, or interpretations thereof, or policies relating to financial institutions or accounting, tax, trade, monetary or fiscal matters; (31) our ability to receive dividends from the Bank and satisfy our obligations as they become due; (32) the institution and outcome of litigation and other legal proceedings against us or to which we become subject; (33) the limited experience of our management team in managing and operating a public company; (34) the incremental costs of operating as a public company; (35) our ability to meet our obligations as a public company, including our obligations under Section 404 of the Sarbanes-Oxley Act of 2002; and (36) other risks and factors described under the sections titled "Risk Factors" and "Management's Discussion and Analysis of Financial Condition and Results of Operations" in our Annual Report on Form 10-K for the fiscal year ended December 31, 2025, or in any of the Company's subsequent filings with the U.S. Securities and Exchange Commission. Commercial undertakes no obligation to update these forward-looking statements, as a result of changes in assumptions, new information, or otherwise, after the date of this press release, except as required by law.
SOURCE: Commercial Bancgroup, Inc.
View the original press release on ACCESS Newswire
J.Oliveira--AMWN