
The Retirement Risk That Can Derail Even the Best Financial Plan
 Missing F-35 fighter parts 'not sensitive', says Australia minister
 Cambodia showcases scams crackdown with global conference
 Afghan cyclist who disguised herself as man wins Asian Games silver
 Typhoon Dujuan leaves four dead in Japan, 45,000 houses without power
 G7 leaders condemn Houthi strikes on Saudi Arabia
 Google data centre sparks protests in Austria
 Shin Ohashi: Junk food-loving teen and Japan's next big swimming hope
 Stocks rise on AI buzz, drop in oil prices
 China's robot dancers limber up for America's Got Talent final
 Despite military might, Saudi struggles to crush the Houthis
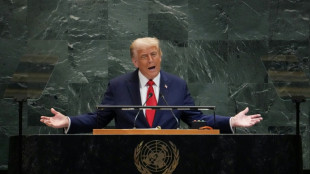 Trump to tout deals, defend Iran war in UN speech
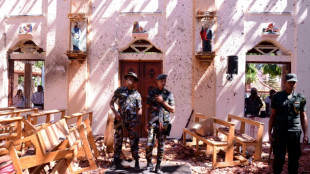 Sri Lanka to issue verdict in landmark Easter attack trial
 Coretura Selects Alloy Kore to Advance a Unique Software-Defined Vehicle Platform for Its Commercial Vehicle Customers
 Akkodis and Hamburg Public Transport Association Showcase hvv mia at InnoTrans 2026, Demonstrating the Future of AI-Powered Mobility
 Macron says talks with Trump on Red Sea, Ukraine 'constructive'
 Green policies just good politics, says UK minister
 Bardot auction in Paris fetches nearly one million euros
 No timeline on Daniels injury return, says Commanders coach
 British Columbia sues OpenAI in US court over Canada school shooting
 French star Batum retires after 18-year NBA career
 Zidane leads first France training session
 Man shot by ICE agent in Texas detained with bullet inside him: lawyer
 California declares state of emergency ahead of El Nino
 South Africa arrests three more suspects, after nine women murdered
 Carse needs time away from England, says captain Brook
Understanding the Hidden Danger of Risk Stacking
BEL AIR, MD / ACCESS Newswire / September 3, 2026 / Most people believe the greatest threat to their retirement is a stock market crash.
Others worry about inflation, rising healthcare costs, higher taxes, or the possibility of outliving their savings.
Each of those concerns is legitimate. In fact, they deserve careful planning and attention.
But after years of helping individuals and families prepare for retirement, I've come to believe that the greatest retirement risk is not any one of those challenges by itself.
It's what happens when several of them show up at the same time.
I often compare retirement planning to climbing Mount Everest.
For decades, we prepare for the ascent. We work hard, save diligently, invest consistently, and build wealth with the goal of one day reaching retirement. We focus on accumulation. We celebrate milestones. We watch account balances grow.
The summit represents financial independence. But reaching the summit is only half the journey. In fact, approximately 93% of Everest fatalities occur during the descent. Why?
Because the descent presents an entirely different set of risks and challenges. Climbers are tired. Conditions change. Weather shifts unexpectedly. Oxygen levels drop. Small mistakes become bigger problems.
Most climbers don't fail because of a single mistake.
They fail because multiple challenges begin working against them at the same time.
Retirement works much the same way.
Many people spend decades preparing to retire but relatively little time preparing for what retirement will actually look like. The risks they face after retirement are often very different from the risks they anticipated while they were working.
The challenge isn't simply accumulating enough money.
The challenge is navigating the years ahead when multiple risks begin interacting with one another.
Retirement isn't usually derailed by a single risk.
It's derailed when several manageable risks arrive at the same time.
I call this phenomenon Risk Stacking.
Risk Stacking occurs when multiple retirement risks-such as taxes, healthcare costs, market volatility, inflation, or longevity-begin interacting with one another, creating a cumulative effect that can place unexpected pressure on a financial plan.
Most retirement plans are built around solving individual problems. An advisor may discuss investments.
An accountant may focus on taxes.
An attorney may handle estate planning.
An insurance professional may focus on healthcare or risk management.
Each of these areas is important.
The problem is that retirement doesn't happen one issue at a time.
Real life doesn't operate in neat little compartments.
Retirement risks rarely arrive individually.
They tend to collide. And when they do, the consequences are often far greater than any one risk alone.
Imagine a recently retired couple, both age 67.
They've done many things right.
Their home is paid off.
They've accumulated a healthy retirement portfolio.
They have no major debt.
They've established a withdrawal strategy and feel confident about the future.
Then something unexpected happens.
Two years into retirement, the market declines significantly.
At first, this seems manageable. Markets have recovered before.
But around the same time, one spouse experiences a health issue that results in increased medical expenses.
Now the couple must withdraw more money from their retirement accounts than originally planned.
Those larger withdrawals increase taxable income.
The higher income may trigger increased Medicare premiums through IRMAA surcharges.
The larger withdrawals also reduce the portfolio's ability to recover when the market eventually rebounds.
None of those events alone would necessarily derail the plan.
Together, however, they create a chain reaction.
This is what I call Risk Stacking-the moment when several manageable risks begin affecting one another and creating consequences that weren't anticipated.
What began as a market decline and an unexpected healthcare expense has now affected income, taxes, Medicare costs, and the portfolio's ability to recover.
That's how Risk Stacking works.
Here's another example.
A retiree wants to help a child purchase a home.
They decide to withdraw an additional $50,000 from an IRA.
A wonderful gesture.
Unfortunately, the financial consequences often extend far beyond the withdrawal itself.
That additional income may push more of their Social Security benefits into taxation.
It could increase their Medicare premiums in future years. It may move them into a higher tax bracket.
It may create an unexpectedly large tax bill for the current year.
One decision.
Multiple consequences.
Most people never see those connections until after they've occurred.
Getting to retirement and successfully navigating retirement are two very different challenges.
The strategies that help you build wealth are not always the same strategies that help you preserve it.
During your working years, success is often relatively straightforward: save more, invest consistently, and avoid unnecessary debt.
Retirement requires something different.
Retirement requires coordination.
Every financial decision affects another area of the plan.
Tax decisions affect income planning.
Income decisions affect Medicare costs.
Healthcare expenses affect withdrawal strategies.
Investment decisions affect legacy planning.
Estate planning decisions affect beneficiaries and taxes.
Nothing exists in isolation.
The strongest retirement plans are not the ones that assume everything will go right. They're the ones prepared for when multiple things go wrong at the same time.
That is why recognizing and planning for Risk Stacking can be so important.
At The Athena Team, we often refer to five key areas of retirement planning: Income Planning, Investment Strategy, Healthcare Planning, Tax Strategy, and Legacy Planning.
Most retirees have concerns in each of these areas.
The mistake is treating them as separate conversations.
They are connected.
A change in one area often creates consequences in another.
When planning is coordinated, decisions can complement one another.
When planning is fragmented, risks begin to stack.
The goal is not simply to reach retirement.
The goal is to navigate retirement successfully.
Just as a Sherpa helps climbers prepare for both the ascent and the descent of Mount Everest, successful retirement planning requires preparation for the challenges that may emerge long after the working years are over.
Market volatility.
Taxes.
Healthcare costs.
Inflation.
Longevity.
Legacy concerns.
Each of these risks is manageable on its own.
The greater danger occurs when they arrive together and no one has prepared for how they will interact.
Because retirement isn't usually derailed by a single risk.
It's derailed when several manageable risks arrive at the same time.
That is the retirement risk that can derail even the best financial plan.
And that is why the most effective retirement strategies don't focus on one risk at a time.
They prepare for Risk Stacking before it occurs.
By Sherri Over
Retirement Income & Wealth Advisor l The Athena Team
(888) 680-8150
[email protected]
Bel Air, MD 21014
Sherri Over is Founder of The Athena Team, a holistic retirement planning firm focused on helping families navigate retirement income planning, tax strategies, healthcare considerations, investments, and legacy planning. As a Certified Financial Fiduciary, she specializes in helping pre-retirees and retirees create personalized strategies designed to provide greater clarity, confidence, and peace of mind throughout retirement.
Investment advisory services offered through Foundations Investment Advisors, LLC, an SEC registered investment adviser.
SOURCE: The Athena Team
View the original press release on ACCESS Newswire
P.Costa--AMWN