Retiring and Need Income Soon? Consider an Immediate Annuity
 Missing F-35 fighter parts 'not sensitive', says Australia minister
 Cambodia showcases scams crackdown with global conference
 Afghan cyclist who disguised herself as man wins Asian Games silver
 Typhoon Dujuan leaves four dead in Japan, 45,000 houses without power
 G7 leaders condemn Houthi strikes on Saudi Arabia
 Google data centre sparks protests in Austria
 Shin Ohashi: Junk food-loving teen and Japan's next big swimming hope
 Stocks rise on AI buzz, drop in oil prices
 China's robot dancers limber up for America's Got Talent final
 Despite military might, Saudi struggles to crush the Houthis
 Trump to tout deals, defend Iran war in UN speech
 Sri Lanka to issue verdict in landmark Easter attack trial
 Coretura Selects Alloy Kore to Advance a Unique Software-Defined Vehicle Platform for Its Commercial Vehicle Customers
 Akkodis and Hamburg Public Transport Association Showcase hvv mia at InnoTrans 2026, Demonstrating the Future of AI-Powered Mobility
 Macron says talks with Trump on Red Sea, Ukraine 'constructive'
 Green policies just good politics, says UK minister
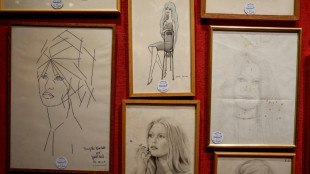 Bardot auction in Paris fetches nearly one million euros
 No timeline on Daniels injury return, says Commanders coach
 British Columbia sues OpenAI in US court over Canada school shooting
 French star Batum retires after 18-year NBA career
 Zidane leads first France training session
 Man shot by ICE agent in Texas detained with bullet inside him: lawyer
 California declares state of emergency ahead of El Nino
 South Africa arrests three more suspects, after nine women murdered
 Carse needs time away from England, says captain Brook
Get ample income guaranteed for life
MEDFORD, OR / ACCESS Newswire / September 3, 2026 / Planning for retirement income should start years before you retire. Fortunately, there's a good solution for procrastinators and people forced to retire early: an immediate annuity. It can be invaluable in closing an income shortfall.
"An immediate income annuity converts your money into a stream of income that can be guaranteed for your lifetime and, optionally, that of your spouse too," says Ken Nuss, CEO of AnnuityAdvantage and a top national expert on securing retirement income. "You can create your own private pension."
Issued by a life insurance company, the time-tested product is also called a single-premium immediate annuity (SPIA).
High guaranteed lifetime income
You can get more guaranteed income from an immediate annuity than from almost any other vehicle. That's largely because each annuity payment includes both nontaxable return of principal and taxable interest. This assumes the annuity is "nonqualified"-not within an IRA or 401(k).
"It's a bit like the opposite of a mortgage, where you're paying both principal and interest," Nuss says.
You can fund an immediate annuity using almost any source: using the proceeds from a maturing bank certificate of deposit (CD), a savings or money market account, or selling stocks, bonds, real estate or mutual funds.
You can also transfer money from a retirement plan account like an IRA or 401(k). You generally fund an immediate annuity all at once with a "lump sum" or "single premium."
All annuities come with a mandated free-look period, typically 20 to 30 days, depending on the state of issue. During this period, you can change your mind and return the policy for a full refund.
Cover one or two lives
The most straightforward immediate annuity is the single-life variety. It pays only while the annuitant (the person designated to receive payments) is still alive.
This type offers the highest income because the insurance company doesn't have to return any unused premium. The people who die earlier than average subsidize those who live longer than average.
"If you're not concerned with leaving anything to your heirs, this option may be best," Nuss says.
With a joint life immediate annuity, payments continue as long as either of the two annuitants is alive. If one person dies, the survivor continues to receive income, which may be the same amount (100% joint survivor) or a reduced amount (such as 50% or 75%). Because payments are guaranteed for two lives rather than one, the income amount is lower than that of a single-life annuity, all other factors being equal.
The "life with period certain" option means the annuity will pay throughout the annuitant's life and also continue making payments to a beneficiary. If you die before the end of the "period certain" (such as 15 years), your beneficiary will get payments for the remaining portion of the specified term (usually 5 to 20 years). If you live past the period-certain term, payments will stop at your death.
An "installment refund" immediate annuity also protects your beneficiary. Suppose you bought a lifetime annuity but passed away a few years later, before you received payments equivalent to the premium you paid. With this option, your beneficiary will continue receiving regular payments until the difference has been made up. So, if you deposited $200,000 into an immediate annuity and received $50,000 in payments, your beneficiary will continue to receive $150,000 more in installments.
The "cash refund" option is similar, but the beneficiary will receive the amount due as a lump sum.
How much does immediate annuity pay now?
Here are a couple of scenarios.
Maria, a single woman, 65, deposits $250,000into an immediate annuity. Since she has no children or others she needs to protect, she chooses a single-life nonqualified SPIA. She'll receive $1,654 per month, including $612 of taxable interest and $1,042 of nontaxable return of principal. If she lives to age 85, the payments will become fully taxable then.
Ted and Doris, a married couple, are 70. They also place $250,000 in an SPIA. They choose a joint life annuity. They'll get $1,627 per month ($617 taxable, $1,010 tax-exempt) as long as one of them is alive. After 247 months, if either Ted or Doris is living, the payments will become fully taxable.
Lifetime income = peace of mind
Because immediate annuities are typically guaranteed to pay the same level of income for the rest of your life, they offer protection against the worrying possibility that you'll outlive your savings. Income annuities are the opposite of life insurance: they protect buyers from the financial risk of living a very long life.
They're a great option if you're concerned about replacing your income during retirement and want to add certainty to your financial future.
"Research shows that people with an adequate guaranteed income in retirement are happier and less anxious," Nuss says.
Reduce risk and stress
You won't get rich with an immediate annuity. They're designed to reduce risk and stress with guaranteed lifetime income, he adds.
While you might make more money in the long term by investing in stocks, the two key words are "might" and "long term." If you can hold onto your stocks for many years, you're very likely to get a good return. However, when you're older, your time frame grows shorter.
Furthermore, stocks are volatile. If you're forced to sell equities to raise money for income when the market is down, especially for an extended period, your portfolio can take a big hit that it might not ever fully recover from.
It's almost forgotten now, but during the decade ending in 2009, stocks fell by an average of about 1.0% a year. Stocks can be exciting; an income annuity is boring and dependable.
Annuities also let you be a bit more adventurous with the remainder of your savings. When you have your basic income needs covered by an annuity and Social Security, you can afford to put less money in bonds or certificates of deposit and take on a bit more risk with stocks because you're not as reliant on them.
Inflation protection available at a cost
Standard immediate annuities don't protect against inflation. You can, however, choose an inflation-protection rider that will boost payments by a fixed percentage each year, typically 1% to 3%. However, your initial payments will be significantly lower. At current rates, a 3% annual boost might reduce your starting payment by 25% to 30% compared to a level annuity.
Immediate annuities aren't right for everyone. If you don't need the income soon, you should consider a deferred annuity that will give you greater tax deferral longer.
Ken Nuss is the founder and CEO of AnnuityAdvantage, a leading online provider of fixed-rate, fixed-indexed, and income annuities. Ken is a nationally recognized annuity expert and widely published author. A free rate comparison service with interest rates from dozens of insurers is available at www.annuityadvantage.com or by calling (800) 239-0356. The firm also offers an income-annuity quoting service. There are no fees or charges for the firm's services; 100% of the client's money goes to work for them in their annuity.
Media contact: Henry Stimpson, Stimpson Communications, [email protected]
SOURCE: AnnuityAdvantage
View the original press release on ACCESS Newswire
T.Ward--AMWN