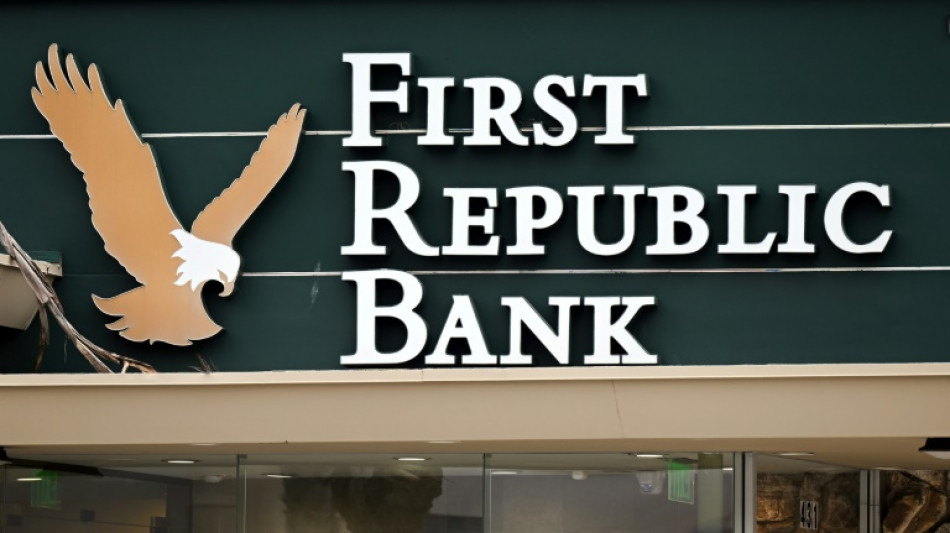
JPMorgan buys First Republic after regulators seize control / Photo: Patrick T. Fallon - AFP/File
 ALIX LASERS shareholders remove Michael Sobitsch as managing director in view of the circumstances
 Kiss of Life Teases First Winter Single 'Greedy'
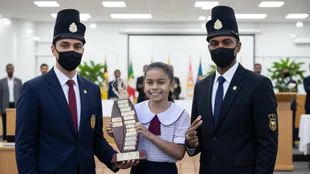 Eight-Year-Old Georgia Wins Penrith Valley Public Speaking Competition
 Tosca's 2026 Sustainability Report Makes the Case for Packaging as Critical Supply Chain Infrastructure
 The DEA Laid The Trap - And State Marijuana Operators Took The Bait
 Ryde Group Ltd Announces Non-Binding Term Sheet for Proposed Minority Investment in Multi Genius Limited and MOU on Technology Collaboration
 West Midlands Shoppers Urged to Guard Against Black Friday Scams
 Surfshark Adds Real-Time Call Protection to iOS App in Version 5.3.0
 Saudi PIF Retains Top Sovereign Wealth Fund Brand Title for Third Year
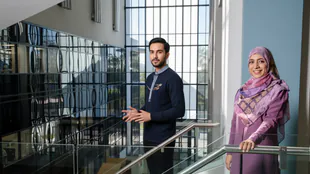 Professor Shahida Moosa Pioneers Medical Genomics in South Africa Amid Testing Shortages
US financial authorities seized California's troubled First Republic Bank on Monday and sold it to JPMorgan Chase, hoping to bring to a close a two-month banking crisis that has spooked the financial system.
First Republic became the second-largest bank by assets to collapse in US history after it disclosed last week a loss of more than $100 billion in deposits in the first quarter.
After the bank failed to produce a satisfactory rescue plan and with its stock continuing to nosedive, the authorities stepped in, soliciting bids last week from potential buyers, and then taking possession of it.
As part of the deal struck early Monday, the California regulator appointed the Federal Deposit Insurance Corporation (FDIC), an agency in charge of guaranteeing bank deposits, as the receiver of First Republic, to be immediately sold to JPMorgan Chase.
The agreement means JPMorgan, the largest bank the United States, will recover all of the First Republic's deposits, as well as "almost" all of its assets, according to an FDIC statement.
The federal agency estimates it will have to pay about $13 billion to cover First Republic's losses, but the bank's 84 branches will be able to reopen Monday as usual.
"Our government invited us and others to step up, and we did," Jamie Dimon, JPMorgan's CEO, said in a statement after the deal was announced.
The transaction "modestly benefits our company overall," JPMorgan said in a news release.
Shares of JPMorgan jumped 4.3 percent in pre-market trading, while US stock futures were little changed.
"Hopefully this will help stabilize everything," Dimon said on a conference call with reporters before the US stock market opened.
- Snowball effect -
The government's takeover and sale of First Republic comes two months after the liquidation of Silvergate Bank -- a favorite among the cryptocurrency crowd -- and the swift demise of Silicon Valley Bank (SVB), after it took on excessive interest-rate risk.
New York-based Signature Bank also closed a few days after SVB.
The collapses led to a snowball effect as concerned investors looked for signs of weakness in the broader banking sector in the United States and Europe.
Swiss banking giant Credit Suisse became the highest-profile casualty when it was pushed by regulators to merge with its rival, UBS.
To avert yet another banking collapse, authorities reached a deal with 11 major banks in March to extend a $30 billion lifeline to First Republic.
But this was not enough to reassure investors.
By Friday's close, First Republic was worth only $654 million, down from more than $20 billion at the start of the year, and $40 billion at its peak in November 2021.
At first glance, First Republic appeared to be well-positioned: it was known to have a wealthy clientele who deposited large sums.
But the string of banking defaults rattled customers, and a majority of First Republic's loans were fixed-rate mortgages, which have lost value due to soaring interest rates.
Observers are closely watching for any broader implications of the latest financial institution's collapse.
With its assets standing at $233 billion at the end of March, First Republic is the second-largest bank to fall in US history -- excluding investment banks, such as Lehman Brothers -- after Washington Mutual's bankruptcy during the financial crisis of 2008.
That lender too was acquired by JPMorgan, the largest bank in the United States.
"First Republic was identified as a problem bank as early as mid-March and the announcement of its closure is not a new reason to worry," Nicolas Veron, an economist at the Peterson Institute for International Economics said ahead of the takeover announcement.
"If another bank proved to be fragile, that would be another problem," he added.
Soon after First Republic's seizure was announced, the US Treasury moved to try to allay concerns.
"The banking system remains sound and resilient, and Americans should feel confident in the safety of their deposits and the ability of the banking system to fulfill its essential function of providing credit to businesses and families," a Treasury spokesperson said.
The upheaval in the banking sector comes on the heels of a shift by the Federal Reserve to counter inflation with aggressive interest rate hikes, a pivot that has significantly revalued assets.
The Fed is expected to again lift interest rates later this week.
A.Malone--AMWN