$80 billion in Aramco shares moved to Saudi sovereign fund
 Turkey says news site closed for 'LGBTQ propaganda'
 Oil companies close in on Venezuela despite hurdles
 Turkey freezes ex-minister's assets as fund scandal grows
 Guardiola backs Man City after bombshell guilty verdicts
 G20 trade ministers open talks under strain of Trump tariffs
 France in talks with UK to end 2025 migrant accord: ministry
 Europe's surging inflation spreads gloom in stock markets
 Truth commission demands compensation for Sweden's Sami people
 Japan win marathon penalty shootout to set up South Korea gold-medal clash
 Djokovic grinds out opening-round win at China Open
 Northern Ireland police probe blockade of disputed parade
 UK PM Burnham reopens divisive debate on rejoining EU
 Man City future in doubt after guilty verdict
 'Do something,' begs Iranian woman after death sentence over protests
 China extends 52-year unbeaten record as Games organisers say sorry
 In Manchester, people say City scandal is 'shame for football'
 Stocks lacklustre as inflation data weighs on sentiment
 Israel-bound plane rerouted, pilots wounded in reported fight
 Truth commission on Sweden's Sami people seeks redress
 Energy costs spark inflation surges in France, Italy
 South Korea break China hearts to reach Asian Games football final
 Eala storms into Asian Games semi-finals to thrill adoring fans
 Turkey freezes ex-minister's assets as fund crisis grows
 What we know about the North Korean POW dispute
 Most equities rise after oil price plunge, US data in focus
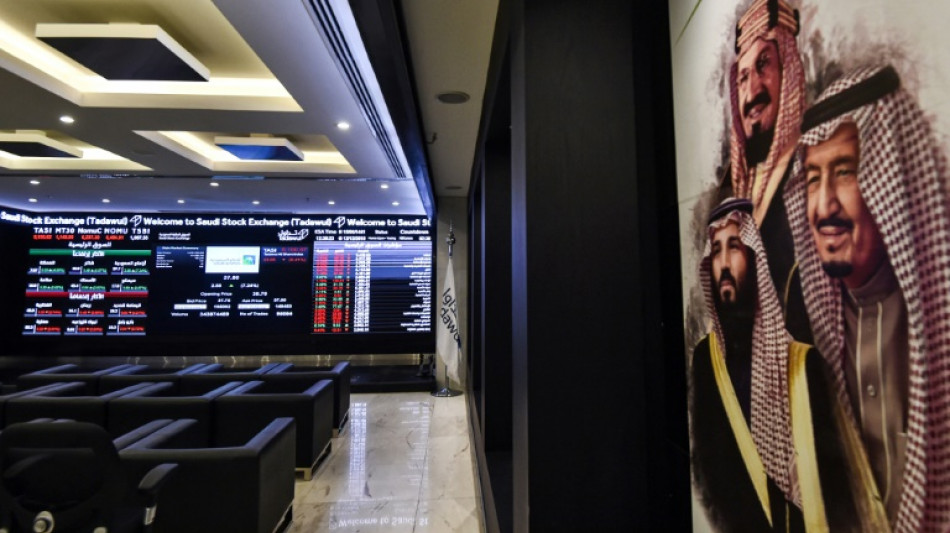
Saudi Arabia has moved four percent of Aramco shares worth $80 billion in the world's biggest oil exporter to the kingdom's sovereign wealth fund, authorities said on Sunday.
Crown Prince Mohammed bin Salman, Saudi Arabia's de facto ruler, announced the move as part of efforts to recalibrate the oil-dominated economy.
The transfer is also the latest sign that Saudi Arabia wants to open up the oil giant and "crown jewel" of the Saudi economy, the Arab world's largest.
The "transfer of four percent of Aramco shares to the Public Investment Fund (PIF)... is part of the kingdom's long-term strategy to support the restructuring of its economy," the crown prince was quoted as saying by the official Saudi Press Agency.
Crown Prince Mohammed said he wants the investment fund to have one trillion dollars in assets by the end of 2025. The fund, the centrepiece of official moves to end economic reliance on oil, has less than half that amount before this deal.
"The shares will bolster the fund's strong financial position and high credit ratings in the medium term, as the PIF relies on the value of its assets and the returns on its assets under management for its funding strategy," he said.
The crown prince stressed that the Saudi state would remain the dominant Aramco shareholder with a 94 percent stake. Crown Prince Mohammed is also head of the PIF sovereign fund.
Aramco shares finished down by 0.6 percent in trading Sunday after the announcement. But experts said the share switch would strengthen the sovereign fund.
Mazen al-Sudairi, head of Research at Al Rajhi Capital, said it would "give the fund flexibility" if it wants to launch shares on the local or international market.
Ibrahim al-Ghitani, head of energy studies at the Future for Advanced Research and Studies think tank, predicted that it would a "preparatory step" toward an international sale of shares.
- 'Financial reform process' -
The crown prince said in April last year that Aramco was in talks to sell a one percent stake to a foreign energy giant.
"There is a discussion on the acquisition of one percent (of Aramco) by one of the world's leading energy companies, and this will be a very important deal to boost Aramco's sales in that country," the crown prince said at the time.
Aramco previously sold 1.7 percent of its shares on the Saudi bourse in December 2019, generating $29.4 billion in the world's biggest initial public offering.
It raised six billion dollars in Islamic bonds in June last year, so that it could pay dividends to the new shareholders.
But Aramco announced $30.4 billion in profits for the third quarter of 2021, a massive rise from $18.8 billion for the same quarter the previous year, as oil prices took off again.
In December, Aramco said it had signed a $15.5 billion lease agreement for its gas pipeline network with a consortium led by BlackRock Real Estate of the United States and Hassana Investment Company, a Saudi-state-backed investment management firm.
Aramco and its assets were once kept under a vice-like government control, long off-limits to outside investment.
But with the rise of Crown Prince Mohammed, who has been pushing his "Vision 2030" reform programme since 2016, the kingdom has shown readiness to cede some control.
M.Thompson--AMWN