KS Bancorp, Inc. (KSBI) Reports 51% Year-To-Date Earnings Growth, Continued Balance Sheet Growth, and Expands Executive Leadership Team.
 Madlanga Commission Deadline Extended to 2027 Amid Calls for Structural Justice Reform
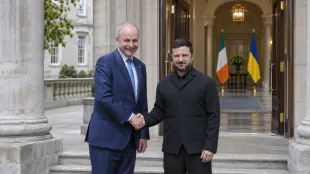 Zelenskyy arrives in Dublin for meetings on Ukraine and peace efforts
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
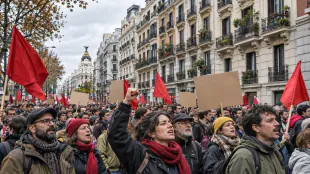 Spain's General Strike Links Housing Crisis to Lost Purchasing Power
 US Adds 165,000 Jobs as Unemployment Falls to 4.1%
 Energy Costs Push OECD Inflation Up to 4.5%
 China's Trade Surplus Passes $1 Trillion as Technology Exports Surge
 US Inflation Broadens as Fed Officials Consider Faster Rate Hikes
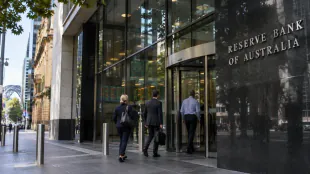 RBA Inflation Target Origins: Why Australia Chose a Range Over Zero
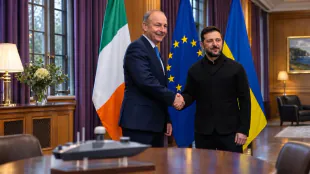 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
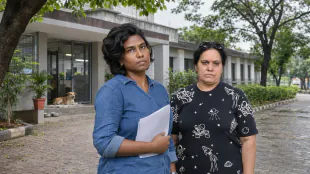 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
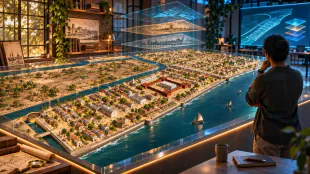 Startup turns Chennai’s history and culture into an interactive world
 EON Resources Inc. Announces First Oil Sale from Horizontal San Andres Development Program
 LASE Corp Reports Third Quarter 2026 Results
 InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 12
 Ocean Harvesters and Omega Protein Condemn Attacks on Commissioners and Fishing Families After Menhaden Vote
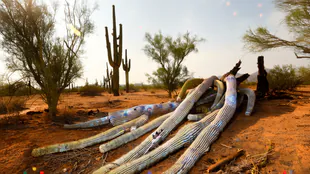 Study Finds Climate Change Threatens Cacti More Than Previously Thought
 एलेक्स बोडी और SCANDIC PAY: Mastercard और VISA कार्ड — भुगतान की नई पीढ़ी
 АЛЕКС БОДИ и SCANDIC PAY: карти Mastercard и VISA — ново поколение разплащания
 أليكس بودي وSCANDIC PAY: بطاقات Mastercard وVISA — جيل جديد من المدفوعات
 ALEX BODI 與 SCANDIC PAY:Mastercard 與 VISA 卡——新一代支付方式
SMITHFIELD, NC / ACCESS Newswire / October 22, 2025 / KS Bancorp, Inc. (the "Company") (OTCID:KSBI), parent company of KS Bank, Inc. (the "Bank"), today reported another quarter of solid financial performance, highlighted by strong earnings growth and continued balance sheet expansion.
For the three months ended September 30, 2025, the Company reported net income of $2.5 million, or $2.24 per diluted share, compared to $1.5 million, or $1.32 per diluted share, for the same period in 2024. This represents a 70.0% increase in net income year-over-year.
Year-to-date net income was $6.8 million, or $6.13 per diluted share, compared to $4.5 million, or $4.07 per diluted share, for the nine months ended September 30, 2024, which represents a 51.0% increase from the prior year.
Net interest income before the provision for credit losses increased 32.6% to $7.3 million for the third quarter of 2025, compared to $5.5 million for the same quarter in 2024. Non-interest income for the three months ended September 30, 2025, was $1.0 million, compared to $881,000 for the comparable period ended September 30, 2024. Non-interest expense totaled $4.9 million, compared to $4.2 million in the third quarter of 2024.
For the nine months ending September 30, 2025, net interest income before the provision for credit losses was $20.5 million, up 27.8% from $16.0 million in the same period of 2024. Non-interest income increased to $3.0 million, compared to $2.6 million for the same period ended September 30, 2024, while non-interest expenses were $13.9 million, compared to $12.3 million for the nine months ending September 30, 2024. The increase reflects investments in personnel, equipment, and technology to support continued growth.
As of September 30, 2025, the Company's unaudited consolidated total assets were $772.7 million, an increase of $81.8 million from $690.9 million at December 31, 2024. Net loan balances grew $67.6 million to $622.1 million, compared to $554.5 million at December 31, 2024, driven by continued loan demand across the Company's branch network. The Company's investment securities totaled $94.3 million at September 30, 2025, compared to $95.9 million at December 31, 2024. Total deposits increased by $84.3 million to $702.5 million at September 30, 2025, compared to $618.2 million at December 31, 2024. The increase included a $29.6 million increase in core deposits. Borrowings declined by $11.1 million, totaling $11.3 million at September 30, 2025, compared to $22.4 million at year's end 2024. Total stockholders' equity increased $7.3 million to $52.6 million as of September 30, 2025, from $45.3 million as of December 31, 2024, reflecting strong retained earnings and overall balance sheet health.
As of September 30, 2025, nonperforming assets consisted of nonaccrual loans totaling $698,000 and foreclosed real estate with a value of $500,000, representing less than 0.20% of the Company's total assets. The allowance for credit losses as of September 30, 2025, totaled $4.8 million, or 0.78% of total loans.
Commenting on the third quarter results, Earl W. Worley, Jr., President and CEO of the Company, stated, "We are proud to share another quarter of strong financial performance for KS Bancorp, highlighted by solid earnings growth, a healthy balance sheet, and continued momentum across our markets. Our 70% year-over-year increase in quarterly net income and 51% year-to-date increase in yearly income reflect both the strength of our core operations and the continued trust our customers place in KS Bank. Strong capital ratios, including a Community Bank Leverage Ratio of 9.29%, along with consistent loan and deposit growth, demonstrate our financial stability and disciplined approach to growth.
This quarter also marked an exciting period of investment in our people and our communities. We were pleased to welcome Travis Bailey as Chief Administrative Officer, who brings more than twenty years of experience in community banking. His leadership will help us continue to grow, build high-performing teams, and foster customer-first service, while staying true to the values that have guided KS Bank for over a century. In addition, Mark Eason joined the bank as Senior Vice President and Commercial Relationship Manager, serving Lillington, Angier, and Coats, North Carolina. Matt McLamb joined the bank as a Deposit Relationship Officer, serving our footprint and developing new deposit customers while servicing cash management clients. Each of these individuals bring deep local connections, exceptional experience, and a shared passion for community banking. Their leadership strengthens our ability to provide relationship-driven service and reinforces our commitment to helping our customers and communities succeed.
As we move into the final quarter of the year, we remain focused on disciplined balance sheet management, maintaining strong credit quality, and making strategic investments in our people and technology. We continue to closely monitor the Federal Reserve's monetary policy decisions, including potential interest rate adjustments. We will remain proactive and deliberate in managing our balance sheet to ensure stability and long-term performance, regardless of market conditions. We will continue to manage risk carefully, remain flexible in our approach, and focus on delivering long-term value to our customers, communities, and shareholders."
In addition, the Company announced today that its Board of Directors has declared a quarterly dividend of $0.28 per share for stockholders of record as of October 31, 2025, with payment to be made on November 10, 2025.
KS Bank continues to be well-capitalized according to regulatory standards, with a Community Bank Leverage Ratio of 9.29% as of September 30, 2025, compared to 9.24% as of December 31, 2024.
KS Bancorp, Inc. is a Smithfield, North Carolina-based single-bank holding company. KS Bank, Inc., a state-chartered savings bank, is KS Bancorp's sole subsidiary. The Bank is a full-service community bank that has served the citizens of eastern North Carolina since 1924. The Bank offers a broad range of personal and business banking products and services, as well as mortgage and trust services. Eleven full-service branches are located in Kenly, Selma, Clayton, Garner, Goldsboro, Wilson, Wendell, Smithfield, Four Oaks, Dunn, and Bailey, North Carolina. For more information, visit www.ksbankinc.com.
This release contains certain forward-looking statements with respect to the financial condition, results of operations and business of the Company. These forward-looking statements involve risks and uncertainties and are based on the beliefs and assumptions of management of the Company and on the information available to management at the time that these disclosures were prepared. These statements can be identified by the use of words like "expect," "anticipate," "estimate" and "believe," variations of these words and other similar expressions. Readers should not place undue reliance on forward-looking statements as a number of important factors could cause actual results to differ materially from those in the forward-looking statements. The Company undertakes no obligation to update any forward-looking statements.
KS Bancorp, Inc. and Subsidiary
Consolidated Statements of Financial Condition
September 30, 2025 | December 31, | ||||
(unaudited) | 2024* | ||||
(Dollars in thousands) | |||||
ASSETS | |||||
Cash and due from banks: | |||||
Interest-earning | $ | 24,343 | $ | 10,627 | |
Noninterest-earning | 5,331 | 4,897 | |||
Time Deposit | 738 | 523 | |||
Investment securities available for sale, at fair value | 94,319 | 95,946 | |||
Federal Home Loan Bank stock, at cost | 498 | 469 | |||
Loans | 626,956 | 558,779 | |||
Less allowance for loan losses | (4,849 | ) | (4,259 | ) | |
Net loans | 622,107 | 554,520 | |||
Accrued interest receivable | 2,931 | 2,655 | |||
Foreclosed assets, net | 500 | - | |||
Property and equipment, net | 12,737 | 12,231 | |||
Other assets | 9,179 | 8,981 | |||
Total assets | $ | 772,683 | $ | 690,849 | |
LIABILITIES AND STOCKHOLDERS' EQUITY | |||||
Liabilities | |||||
Deposits | $ | 702,486 | $ | 618,156 | |
Short-term borrowings | - | 11,144 | |||
Long-term borrowings | 11,248 | 11,248 | |||
Accrued interest payable | 353 | 323 | |||
Accrued expenses and other liabilities | 5,998 | 4,675 | |||
Total liabilities | 720,085 | 645,546 | |||
Stockholder's Equity: | |||||
Preferred stock, no par value, 500,000 shares authorized; none issued and outstanding | |||||
Common stock, no par value, 3,500,000 shares authorized; 1,107,776 shares issued and outstanding at September 30, 2025 and December 31, 2024, respectively | 1,359 | 1,359 | |||
Retained earnings, substantially restricted | 58,563 | 52,675 | |||
Accumulated other comprehensive Income (loss) | (7,324 | ) | (8,731 | ) | |
Total stockholders' equity | 52,598 | 45,303 | |||
Total liabilities and stockholders' equity | $ | 772,683 | $ | 690,849 | |
* Derived from audited financial statements | |||||
KS Bancorp, Inc and Subsidiary
Consolidated Statement of Income
Three Months Ended | Nine Months Ended | ||||||||||
30-Sep | 30-Sep | ||||||||||
2025 | 2024 | 2025 | 2024 | ||||||||
(In thousands, except per share data) | |||||||||||
Interest and dividend income: | |||||||||||
Loans | $ | 10,317 | $ | 8,283 | $ | 28,877 | $ | 23,520 | |||
Investment securities | |||||||||||
Taxable | 575 | 561 | 1,710 | 1,574 | |||||||
Tax-exempt | 183 | 185 | 544 | 589 | |||||||
Dividends | 6 | 6 | 18 | 18 | |||||||
Interest-bearing deposits | 70 | 325 | 413 | 722 | |||||||
Total interest and dividend income | 11,151 | 9,360 | 31,562 | 26,423 | |||||||
Interest expense: | |||||||||||
Deposits | 3,636 | 3,690 | 10,460 | 9,628 | |||||||
Borrowings | 242 | 185 | 596 | 750 | |||||||
Total interest expense | 3,878 | 3,875 | 11,056 | 10,378 | |||||||
Net interest income | 7,273 | 5,485 | 20,506 | 16,045 | |||||||
Provision for loan losses | 277 | 171 | 810 | 454 | |||||||
Net interest income after | |||||||||||
provision for loan losses | 6,996 | 5,314 | 19,696 | 15,591 | |||||||
Noninterest income: | |||||||||||
Service charges on deposit accounts | 367 | 340 | 1,057 | 974 | |||||||
Fees from trust services | 432 | 372 | 1,174 | 1,023 | |||||||
Other income | 211 | 169 | 751 | 576 | |||||||
Total noninterest income | 1,010 | 881 | 2,982 | 2,573 | |||||||
Noninterest expenses: | |||||||||||
Compensation and benefits | 3,015 | 2,532 | 8,567 | 7,547 | |||||||
Occupancy and equipment | 698 | 631 | 1,969 | 1,784 | |||||||
Data processing & outside service fees | 298 | 253 | 853 | 732 | |||||||
Advertising | 81 | 62 | 210 | 172 | |||||||
Other | 783 | 706 | 2,320 | 2,060 | |||||||
Total noninterest expenses | 4,875 | 4,184 | 13,919 | 12,295 | |||||||
Income before income taxes | 3,131 | 2,011 | 8,759 | 5,869 | |||||||
Income tax | 650 | 550 | 1,962 | 1,365 | |||||||
Net income | $ | 2,481 | $ | 1,461 | $ | 6,797 | $ | 4,504 | |||
Basic and Diluted earnings per share | $ | 2.24 | $ | 1.32 | $ | 6.13 | $ | 4.07 | |||
Contact:
Earl W. Worley, Jr. | Regina J Smith |
SOURCE: KS Bancorp, Inc.
View the original press release on ACCESS Newswire
P.M.Smith--AMWN