Solera National Bancorp Announces Third Quarter 2025 Financial Results
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
 China's Singles' Day Exposes Persistent Consumer Caution
 OPEC Says Oil Output Is Near Prewar Levels Despite Shipping Disruptions
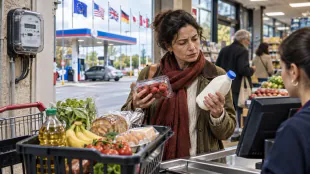
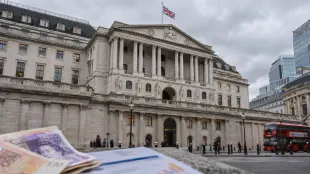 Bank of England Raises Interest Rate to 4% as Energy Risks Intensify
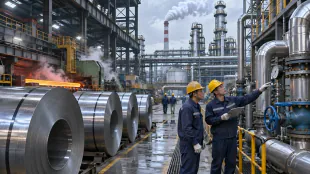 China's Factory Inflation Accelerates While Consumer Demand Stays Weak
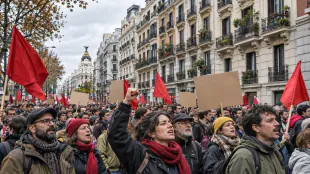 Spain's General Strike Links Housing Crisis to Lost Purchasing Power
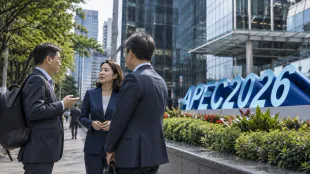 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
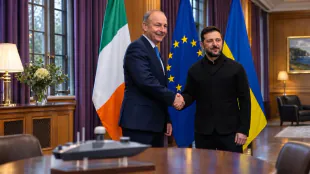 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
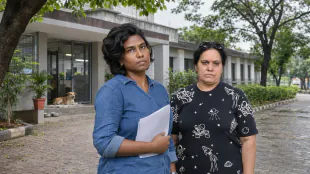 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
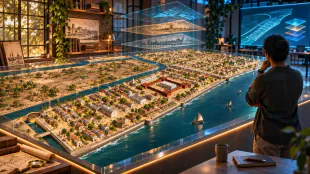 Startup turns Chennai’s history and culture into an interactive world
 Caledonia Mining Corporation Plc: ABRIDGED AND UNAUDITED QUARTERLY RESULTS AND DETAILS OF MANAGEMENT CONFERENCE CALL for the third quarter and nine months ended September 30, 2026 (the "Quarter" or "Q3 2026" and "Nine Months" respectively)
 Hemogenyx Pharmaceuticals PLC Announces First Patient Treated in Second Adult Dose Cohort
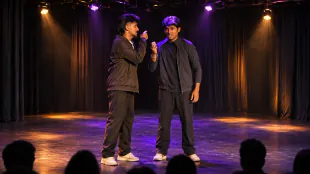 Chennai venue launches month-long festival devoted to full-length theatre
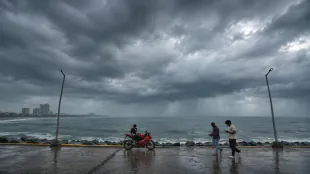 New Bay of Bengal low may form November 13 as Tamil Nadu outlook remains unclear
 ALEX BODI och SCANDIC PAY: Mastercard- och VISA-kort – en ny generation betalningar
 알렉스 보디와 SCANDIC PAY: Mastercard·VISA 카드를 통한 차세대 결제
 ALEX BODIとSCANDIC PAY:Mastercard・VISAカードによる新世代の決済
 ALEX BODI a SCANDIC PAY: karty Mastercard a VISA – nová generace plateb
 ALEX BODI i SCANDIC PAY: karty Mastercard i VISA — nowa generacja płatności
 АЛЕКС БОДИ и SCANDIC PAY: карты Mastercard и VISA — новое поколение платежей
 ALEX BODI și SCANDIC PAY: Cardurile Mastercard și VISA – o nouă generație de plăți
Net income of $6.5 million ($1.52 per share), a NEW RECORD!
Q3 2025 pre-tax and pre-provision income of $8.5 million.
LAKEWOOD, CO / ACCESS Newswire / October 29, 2025 / Solera National Bancorp, Inc. (OTC:SLRK) ("Company"), the holding company for Solera National Bank ("Bank"), a business-focused bank located in the Denver metropolitan area, today reported financial results for the three months ended September 30, 2025. See highlights below.
3Q25 Financial Highlights
Net income of $6.5 million ($1.52 per share), a $1.0 million or 19% increase from Q3 2024.
Tier 1 leverage ratio of 11%, 187 BPS increase from Q3 2024.
Non-interest income of $4.0 million, a $1.6 million increase, or a 67% increase from Q3 2024.
Return on assets was 2.17%, a 33 bps improvement from Q3 2024.
Return on equity was 26.46%, a 109 bps improvement from Q3 2024.
Steve Snailum, COO, commented: "Another record quarter! The bank's agility and strategic execution have enabled us to capitalize on market opportunities. This quarter, we rolled out enhanced business online and digital banking, which enhanced and modernized our suite of business products and services. We also completed integrations with all major data aggregators, thereby allowing our customers to seamlessly connect their preferred software solutions to their Solera bank accounts. Solera remains committed to growing the business bank by offering cutting-edge products and services to help you run your business effectively. The time is now to move your business to Solera."
Avram Shabanyan, EVP, commented: "Our proactive engagement with provider partners and clients has been instrumental in strengthening Solera Bank's presence in the self-directed space. By visiting our partners and attending key industry events, we're strengthening relationships, expanding collaboration, and reinforcing our commitment to helping clients confidently manage their alternative investments through self-directed retirement accounts. At Solera, we believe our clients should have the freedom to take control of their retirement by investing in alternative assets-empowering them to break free from Wall Street, minimize high brokerage and custodian fees, and grow their retirement accounts."
Cole Kent, Commercial Relationship Manager: "The commercial credit team maintains a high standard of service, fortifying current relationships and expertly navigating customers' ever-more complex financial challenges. Solera continues to prioritize the acquisition of strategic customer-partners, offering them the same dependable banking relationship that current SNB customers have come to trust."
About Solera National Bancorp, Inc.
Solera National Bancorp, Inc. was incorporated in 2006 to organize and serve as the holding company for Solera National Bank, which opened for business in September 2007. Solera National Bank is a community bank serving the needs of emerging businesses and real estate investors. At the core of Solera National Bank is welcoming, attentive, and respectful customer service, a focus on supporting a growing and diverse economy, and a passion to serve our community through service, education, and volunteerism. For more information, please visit http://www.SoleraBank.com.
This press release contains statements that may constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. The statements contained in this release, which are not historical facts and that relate to future plans or projected results of Solera National Bancorp, Inc. and its wholly-owned subsidiary, Solera National Bank, are forward-looking statements. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from those projected, anticipated, or implied. We undertake no obligation to update or revise any forward-looking statement. Readers of this release are cautioned not to put undue reliance on forward-looking statements.
Contacts: Jay Hansen, CFO (303) 209-8600
FINANCIAL TABLES FOLLOW
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED BALANCE SHEET
(unaudited)
($000s) | 9/30/2025 | 6/30/2025 | 3/31/2025 | 12/31/2024 | 9/30/2024 | |||||
ASSETS | ||||||||||
Cash and due from banks | $ | 1,378 | $ | 1,969 | $ | 2,401 | $ | 1,576 | $ | 2,193 |
Federal funds sold | 23,900 | - | - | 800 | 400 | |||||
Interest-bearing deposits with banks | 1,872 | 2,963 | 1,033 | 148 | 595 | |||||
Investment securities, available-for-sale | 324,376 | 422,112 | 290,397 | 322,375 | 317,180 | |||||
FHLB and Federal Reserve Bank stocks, at cost | 3,171 | 5,004 | 5,525 | 7,457 | 3,204 | |||||
Paycheck Protection Program (PPP) loans, gross | - | - | 5 | 20 | 35 | |||||
Net PPP loans | - | - | 5 | 20 | 35 | |||||
Traditional loans, gross | 764,433 | 754,518 | 766,687 | 792,753 | 797,516 | |||||
Allowance for loan and lease losses | (11,218 | ) | (11,219 | ) | (10,914 | ) | (10,913 | ) | (10,912 | ) |
Net traditional loans | 753,215 | 743,299 | 755,773 | 781,840 | 786,604 | |||||
Premises and equipment, net | 36,911 | 35,128 | 33,236 | 33,476 | 32,289 | |||||
Accrued interest receivable | 8,148 | 10,244 | 7,153 | 7,750 | 6,940 | |||||
Bank-owned life insurance | 5,223 | 5,190 | 5,159 | 5,127 | 5,095 | |||||
Other assets | 11,032 | 13,433 | 11,103 | 8,820 | 8,734 | |||||
TOTAL ASSETS | $ | 1,169,226 | $ | 1,239,342 | $ | 1,111,785 | $ | 1,169,389 | $ | 1,163,269 |
LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||||
Noninterest-bearing demand deposits | $ | 452,965 | $ | 463,861 | $ | 466,455 | $ | 484,604 | $ | 497,661 |
Interest-bearing demand deposits | 88,048 | 65,761 | 60,507 | 54,734 | 64,606 | |||||
Savings and money market deposits | 121,868 | 138,964 | 104,560 | 100,987 | 103,118 | |||||
Time deposits | 358,976 | 436,547 | 287,378 | 294,338 | 353,405 | |||||
Total deposits | 1,021,857 | 1,105,133 | 918,900 | 934,663 | 1,018,790 | |||||
Accrued interest payable | 1,587 | 2,528 | 1,808 | 2,587 | 2,618 | |||||
Short-term borrowings | - | - | 60,191 | 104,607 | 13,300 | |||||
Long-term FHLB borrowings | 34,000 | 34,000 | 34,000 | 34,000 | 34,000 | |||||
Accounts payable and other liabilities | 6,392 | 5,336 | 6,087 | 4,576 | 5,395 | |||||
TOTAL LIABILITIES | 1,063,836 | 1,146,997 | 1,020,987 | 1,080,434 | 1,074,104 | |||||
Common stock | 43 | 43 | 43 | 43 | 43 | |||||
Additional paid-in capital | 38,793 | 38,778 | 38,763 | 38,748 | 38,748 | |||||
Retained earnings | 89,549 | 83,008 | 77,076 | 72,455 | 67,163 | |||||
Accumulated other comprehensive (loss) gain | (22,995 | ) | (29,484 | ) | (25,084 | ) | (22,291 | ) | (16,789 | ) |
TOTAL STOCKHOLDERS' EQUITY | 105,390 | 92,345 | 90,798 | 88,955 | 89,165 | |||||
TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $ | 1,169,226 | $ | 1,239,342 | $ | 1,111,785 | $ | 1,169,389 | $ | 1,163,269 |
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS (unaudited)
Three Months Ended
($000s, except per share data) | 9/30/2025 | 6/30/2025 | 3/31/2025 | 12/31/2024 | 9/30/2024 | |||||
Interest and dividend income | ||||||||||
Interest and fees on traditional loans | $ | 12,802 | $ | 12,791 | $ | 13,101 | $ | 13,615 | $ | 13,854 |
Investment securities | 4,275 | 4,831 | 3,490 | 3,297 | 3,544 | |||||
Dividends on bank stocks | 91 | 180 | 175 | 131 | 160 | |||||
Other | 26 | 21 | 49 | 13 | 19 | |||||
Total interest income | $ | 17,194 | $ | 17,823 | $ | 16,815 | $ | 17,056 | $ | 17,577 |
Interest expense | ||||||||||
Deposits | 6,463 | 6,235 | 4,959 | 5,564 | 6,312 | |||||
FHLB & Fed borrowings | 550 | 1,410 | 1,550 | 1,223 | 1,332 | |||||
Total interest expense | 7,013 | 7,645 | 6,509 | 6,787 | 7,644 | |||||
Net interest income | 10,181 | 10,178 | 10,306 | 10,269 | 9,933 | |||||
Provision for loan and lease losses | 6 | 310 | 7 | 6 | 105 | |||||
Net interest income after provision for loan and lease losses | 10,175 | 9,868 | 10,299 | 10,263 | 9,828 | |||||
Noninterest income | ||||||||||
Customer service and other fees | 284 | 291 | 300 | 470 | 389 | |||||
Other income | 711 | 677 | 807 | 954 | 1,138 | |||||
Gain on sale of securities | 2,986 | 2,709 | - | - | 858 | |||||
Total noninterest income | 3,981 | 3,677 | 1,107 | 1,424 | 2,385 | |||||
Noninterest expense | ||||||||||
Employee compensation and benefits | 2,838 | 2,827 | 2,656 | 2,611 | 2,472 | |||||
Occupancy | 538 | 553 | 448 | 492 | 393 | |||||
Professional fees | 677 | 330 | 259 | 309 | 122 | |||||
Other general and administrative | 1,629 | 1,593 | 1,694 | 1,437 | 1,423 | |||||
Total noninterest expense | 5,682 | 5,303 | 5,057 | 4,849 | 4,410 | |||||
Net Income Before Taxes | $ | 8,474 | $ | 8,242 | $ | 6,349 | $ | 6,838 | $ | 7,803 |
Income Tax Expense | 1,934 | 2,309 | 1,711 | 1,526 | 2,294 | |||||
Net Income | $ | 6,540 | $ | 5,933 | $ | 4,638 | $ | 5,312 | $ | 5,509 |
Income Per Share | $ | 1.52 | $ | 1.38 | $ | 1.08 | $ | 1.24 | $ | 1.28 |
Tangible Book Value Per Share | $ | 24.51 | $ | 21.48 | $ | 21.12 | $ | 20.69 | $ | 20.74 |
WA Shares outstanding | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | |||||
Pre-Tax Pre-Provision Income | $ | 8,480 | $ | 8,552 | $ | 6,356 | $ | 6,844 | $ | 7,908 |
Net Interest Margin | 3.70 | % | 3.56 | % | 3.93 | % | 3.81 | % | 3.67 | % |
Cost of Funds | 2.54 | % | 2.66 | % | 2.49 | % | 2.51 | % | 2.72 | % |
Efficiency Ratio | 50.84 | % | 47.58 | % | 44.31 | % | 41.47 | % | 38.48 | % |
Return on Average Assets | 2.17 | % | 2.02 | % | 1.63 | % | 1.82 | % | 1.84 | % |
Return on Average Equity | 26.46 | % | 25.92 | % | 20.64 | % | 23.86 | % | 25.37 | % |
Leverage Ratio | 11.0 | % | 9.8 | % | 10.4 | % | 9.5 | % | 9.1 | % |
Asset Quality: | ||||||||||
Non-performing loans to gross loans | 0.59 | % | 0.60 | % | 0.42 | % | 0.52 | % | 0.65 | % |
Non-performing assets to total assets | 0.39 | % | 0.37 | % | 0.29 | % | 0.35 | % | 0.45 | % |
Allowance for loan losses to gross traditional loans | 1.47 | % | 1.49 | % | 1.42 | % | 1.38 | % | 1.37 | % |
* Not meaningful due to the insignificant amount of non-performing loans. | ||||||||||
Criticized loans/assets: | ||||||||||
Special mention | $ | 19,306 | $ | 2,842 | $ | 11,103 | $ | 10,730 | $ | 29,145 |
Substandard: Accruing | 35,447 | 39,971 | 19,641 | 14,911 | 22,410 | |||||
Substandard: Nonaccrual | 8,281 | 4,526 | 3,251 | 4,142 | 5,180 | |||||
Doubtful | - | - | - | - | - | |||||
Total criticized loans | $ | 63,034 | $ | 47,339 | $ | 33,995 | $ | 29,782 | $ | 56,735 |
Other real estate owned | - | - | - | - | - | |||||
Investment securities | - | - | - | - | - | |||||
Total criticized assets | $ | 63,034 | $ | 47,339 | $ | 33,995 | $ | 29,782 | $ | 56,735 |
Criticized assets to total assets | 5.39 | % | 3.82 | % | 3.06 | % | 2.55 | % | 4.88 | % |
SOURCE: Solera National Bancorp, Inc.
View the original press release on ACCESS Newswire
F.Pedersen--AMWN