U & I Financial Corp. Reports Third Quarter 2025 Financial Results
 Jury hears social-media image helped identify teen in Scarlett Faulkner case
 American Airlines passenger falls ill and vomits on three travellers
 China's Singles' Day Exposes Persistent Consumer Caution
 OPEC Says Oil Output Is Near Prewar Levels Despite Shipping Disruptions
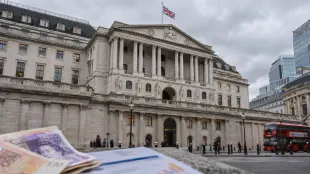 Bank of England Raises Interest Rate to 4% as Energy Risks Intensify
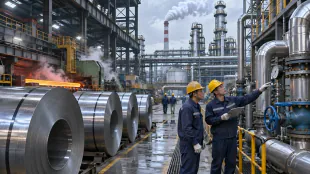 China's Factory Inflation Accelerates While Consumer Demand Stays Weak
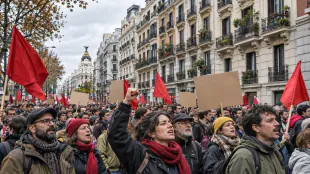 Spain's General Strike Links Housing Crisis to Lost Purchasing Power
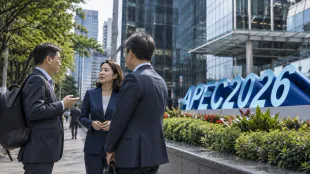 Korea, Singapore and New Zealand Advance Green Trade Pact Talks
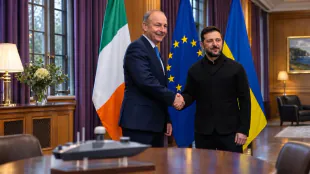 Ireland and Ukraine consider drone cooperation memorandum after Dublin talks
 Georgia refrigeration company sues EPA after five-year HFC reprieve
 EU proposes broad consumer safeguards for apps, subscriptions and ticketing
 Nvidia faces scrutiny over alleged Chinese intelligence link to Jensen Huang
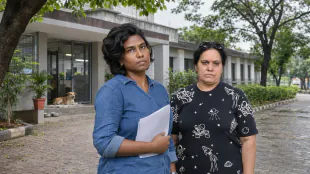 Chennai orders inquiry after dogs die at shelter; two veterinarians face action
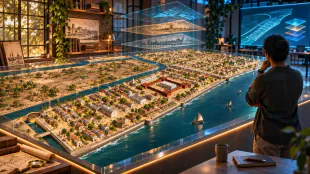 Startup turns Chennai’s history and culture into an interactive world
 Caledonia Mining Corporation Plc: ABRIDGED AND UNAUDITED QUARTERLY RESULTS AND DETAILS OF MANAGEMENT CONFERENCE CALL for the third quarter and nine months ended September 30, 2026 (the "Quarter" or "Q3 2026" and "Nine Months" respectively)
 Hemogenyx Pharmaceuticals PLC Announces First Patient Treated in Second Adult Dose Cohort
 Chennai venue launches month-long festival devoted to full-length theatre
 New Bay of Bengal low may form November 13 as Tamil Nadu outlook remains unclear
 ALEX BODI och SCANDIC PAY: Mastercard- och VISA-kort – en ny generation betalningar
 알렉스 보디와 SCANDIC PAY: Mastercard·VISA 카드를 통한 차세대 결제
 ALEX BODIとSCANDIC PAY:Mastercard・VISAカードによる新世代の決済
 ALEX BODI a SCANDIC PAY: karty Mastercard a VISA – nová generace plateb
 ALEX BODI i SCANDIC PAY: karty Mastercard i VISA — nowa generacja płatności
 АЛЕКС БОДИ и SCANDIC PAY: карты Mastercard и VISA — новое поколение платежей
 ALEX BODI și SCANDIC PAY: Cardurile Mastercard și VISA – o nouă generație de plăți
LYNNWOOD, WA / ACCESS Newswire / October 30, 2025 / U & I Financial Corp. (OTCQX:UNIF), the holding company ("Company") for UniBank ("Bank"), today reported quarterly Net Loss of $258 thousand or $0.05 loss per share in the third quarter of 2025, compared to a net loss of $15.0 million or $2.73 loss per share for the same quarter of 2024. The Company recognized a negative Provision for Credit Losses of $800 thousand during the third quarter of 2025 as compared to a provision expense of $19.5 million recognized for the same quarter last year.
At September 30, 2025, Total Assets were $395.1 million, a decrease of $174.5 million or 30.6% from $569.6 million at September 30, 2024. Net Loans were $298.2 million at September 30, 2025, a decrease of $112.1 million or 27.3% from $410.3 million at September 30, 2024. Total Deposits decreased by $123.4 million or 26.4% to $344.8 million at September 30, 2025 compared to $468.2 million a year earlier.
The Company had a Net Charge Off of $14 thousand during the third quarter of 2025 as compared to $8.7 million during the same quarter of 2024. The total balance of non-accrual loans was $5.3 million at September 30, 2025 as compared to $7.3 million at September 30, 2024. The ratio of nonperforming assets to total assets was 1.35% at September 30, 2025 compared to 2.74% at September 30, 2024.
The Bank's capital ratios were 7.32%, 9.62% and 10.63% for Tier 1 Leverage Ratio, Tier 1 Risk-Based Capital Ratio and Total Risk-Based Capital Ratio, respectively, as of September 30, 2025, as compared to 7.53%, 9.56% and 10.87%, respectively, as of September 30, 2024. All capital ratios remained above the "well capitalized" minimum regulatory guidelines as of September 30, 2025.
"Due to our continued credit improvement and deleveraging efforts, we remained 'well capitalized' as provided in the regulatory guidelines in the third quarter 2025. We also continued to see improved credit metrics, resulting in the lower allowance for credit loss requirement," said President & CEO Stephanie Yoon.
Non-GAAP Financial Metrics
This news release contains certain non-GAAP financial measure disclosures. Management believes these non-GAAP financial measures provide meaningful supplemental information regarding the Company's operational performance, credit quality and capital levels.
About U & I Financial Corp.
UniBank, the wholly owned subsidiary of U & I Financial Corp. (OTCQX: UNIF). Founded in 2006 and based in Lynnwood, Washington, the Bank serves small to medium-sized businesses, professionals, and individuals across the United States with a particular emphasis on government guaranteed loan programs. Customers can access their accounts in any of the four branches - Lynnwood, Bellevue, Federal Way and Tacoma - online, or through the Bank's ATM network.
For more information visit www.unibankusa.com or call (425) 275-9700.
Forward-Looking Statement Safe Harbor: This news release contains comments or information that constitutes forward-looking statements (within the meaning of the Private Securities Litigation Reform Act of 1995) that are based on current expectations that involve a number of risks and uncertainties. Forward-looking statements describe the Company's projections, estimates, plans and expectations of future results and can be identified by words such as "believe," "intend," "estimate," "likely," "anticipate," "expect," "looking forward," and other similar expressions. They are not guarantees of future performance. Actual results may differ materially from the results expressed in these forward-looking statements, which because of their forward-looking nature, are difficult to predict. Investors should not place undue reliance on any forward-looking statement, and should consider factors that might cause differences including but not limited to compliance with the Written Agreement with the Federal Reserve Bank of San Francisco and the Washington Department of Financial Institutions; the result of litigation and investigations; the degree of competition by traditional and nontraditional competitors; declines in real estate markets, an increase in unemployment or sustained high levels of unemployment; changes in interest rates; adverse changes in local, national and international economies; the potential for new or increased tariffs; trade restrictions or geopolitical tensions that could affect economic activity or specific industry sectors, changes in the Federal Reserve's actions that affect monetary and fiscal policies; changes in legislative or regulatory actions or reform, including without limitation; the Dodd-Frank Wall Street Reform and Consumer Protection Act; demand for products and services; further declines in the quality of the loan portfolio that results in continued losses and our ability to succeed in our problem-asset resolution efforts; including, but not limited to, continued credit deterioration of commercial-equipment loans and future increases in the Provision for Credit Losses; the impact of technological advances; changes in tax laws; and other risk factors. U & I Financial Corp. undertakes no obligation to publicly update or clarify any forward-looking statement to reflect the impact of events or circumstances that may arise after the date of this release.
STATEMENT OF INCOME (LOSS) (Unaudited) | ||||||||||||||
Sep-25 | Jun-25 | Sep-24 | Sep-25 | Sep-24 | ||||||||||
(Dollars in thousands except EPS) | QTD | QTD | QTD | YTD | YTD | |||||||||
Interest Income | $ | 5,608 | $ | 5,935 | $ | 8,270 | $ | 18,186 | $ | 26,917 | ||||
Interest Expense | 3,090 | 3,250 | 4,820 | 10,246 | 14,287 | |||||||||
Net Interest Income | 2,518 | 2,685 | 3,450 | 7,940 | 12,630 | |||||||||
Provision for Credit Losses (Negative Provision) | (800 | ) | (2,235 | ) | 19,479 | 69 | 22,445 | |||||||
Gain (Loss) on Loan Sales | - | - | - | - | 179 | |||||||||
Loan Servicing Fees, Net of Amortization | 122 | (54 | ) | 168 | 191 | 527 | ||||||||
Other Non-interest Income | 77 | 83 | 212 | 316 | 592 | |||||||||
Non-interest Income | 199 | 29 | 380 | 507 | 1,298 | |||||||||
Salaries & Benefits | 1,551 | 1,571 | 1,514 | 4,750 | 4,948 | |||||||||
Occupancy Expense | 211 | 205 | 205 | 617 | 586 | |||||||||
Other Expense | 2,012 | 1,512 | 1,568 | 4,773 | 4,381 | |||||||||
Non-interest Expense | 3,774 | 3,288 | 3,287 | 10,140 | 9,915 | |||||||||
Net Income (Loss) before Income Taxes | (257 | ) | 1,661 | (18,936 | ) | (1,762 | ) | (18,432 | ) | |||||
Income Tax Expense (Benefit) | 1 | 904 | (3,983 | ) | (188 | ) | (3,921 | ) | ||||||
Net Income (Loss) | $ | (258 | ) | $ | 757 | $ | (14,953 | ) | $ | (1,574 | ) | $ | (14,511 | ) |
Total Outstanding Shares (in thousands) | 5,477 | 5,477 | 5,477 | 5,477 | 5,477 | |||||||||
Basic Earnings (Loss) per Share | $ | (0.05 | ) | $ | 0.14 | $ | (2.73 | ) | $ | (0.29 | ) | $ | (2.65 | ) |
Statement of Condition (Unaudited) | ||||||||||||
Sep-25 | Jun-25 | Sep-24 | Variance | Variance | ||||||||
(Dollars in thousands) | Qtr End | Qtr End | Qtr End | Prior Qtr | Prior Year | |||||||
Cash and Due from Banks | $ | 34,001 | $ | 39,200 | $ | 70,527 | $ | (5,199 | ) | $ | (36,526 | ) |
Investments | 52,770 | 45,293 | 50,344 | 7,477 | 2,426 | |||||||
Loans Held for Sale | - | - | - | - | - | |||||||
Gross Loans | 301,264 | 318,109 | 439,233 | (16,845 | ) | (137,969 | ) | |||||
Allowance for Credit Losses (ACL) on Loans | (3,102 | ) | (3,798 | ) | (28,964 | ) | 696 | 25,862 | ||||
Net Loans | 298,162 | 314,311 | 410,269 | (16,149 | ) | (112,107 | ) | |||||
Fixed Assets | 5,506 | 5,649 | 6,078 | (143 | ) | (572 | ) | |||||
Deferred Tax Assets | 12,915 | 12,860 | 11,192 | 55 | 1,723 | |||||||
Valuation Allowance | (12,349 | ) | (12,294 | ) | - | (55 | ) | (12,349 | ) | |||
Net Deferred Tax Assets | 566 | 566 | 11,192 | - | (10,626 | ) | ||||||
Bank-Owned Life Insurance | - | - | 14,641 | - | (14,641 | ) | ||||||
Other Assets | 4,114 | 4,565 | 6,554 | (451 | ) | (2,440 | ) | |||||
Total Assets | $ | 395,119 | $ | 409,584 | $ | 569,605 | $ | (14,465 | ) | $ | (174,486 | ) |
Checking | $ | 67,852 | $ | 66,367 | $ | 86,708 | $ | 1,485 | $ | (18,856 | ) | |
NOW | 4,598 | 3,977 | 5,233 | 621 | (635 | ) | ||||||
Money Market | 55,892 | 55,868 | 128,136 | 24 | (72,244 | ) | ||||||
Savings | 4,973 | 4,817 | 6,258 | 156 | (1,285 | ) | ||||||
Certificates of Deposit | 211,425 | 227,861 | 241,840 | (16,436 | ) | (30,415 | ) | |||||
Total Deposits | 344,740 | 358,890 | 468,175 | (14,150 | ) | (123,435 | ) | |||||
Borrowed Funds | 20,000 | 20,000 | 50,000 | - | (30,000 | ) | ||||||
ACL on Off-Balance Sheet Credit Exposure | 5 | 123 | 1,695 | (118 | ) | (1,690 | ) | |||||
Other Liabilities | 1,665 | 2,345 | 2,710 | (680 | ) | (1,045 | ) | |||||
Total Liabilities | 366,410 | 381,358 | 522,580 | (14,948 | ) | (156,170 | ) | |||||
Shareholders' Equity | 28,709 | 28,226 | 47,025 | 483 | (18,316 | ) | ||||||
Total Liabilities & Equity | $ | 395,119 | $ | 409,584 | $ | 569,605 | $ | (14,465 | ) | $ | (174,486 | ) |
Financial Ratios | ||||||||||
Sep-25 | Jun-25 | Sep-24 | Sep-25 | Sep-24 | ||||||
(Dollars in thousands except BVS) | QTD | QTD | QTD | YTD | YTD | |||||
Performance Ratios | ||||||||||
Return on Average Assets* | (0.25% | ) | 0.73% | (10.30% | ) | (0.48% | ) | (3.30% | ) | |
Return on Average Equity* | (3.68% | ) | 11.13% | (96.78% | ) | (7.43% | ) | (31.24% | ) | |
Net Interest Margin* | 2.54% | 2.64% | 2.44% | 2.51% | 2.92% | |||||
Efficiency Ratio | 138.90% | 121.15% | 85.82% | 120.05% | 71.36% | |||||
*Quarterly results are annualized | ||||||||||
Well | Adequately | |||||||||
Sep-25 | Jun-25 | Sep-24 | Capitalized | Capitalized | ||||||
Capital | QTD | QTD | QTD | Minimum | Minimum | |||||
Tier 1 Leverage Ratio** | 7.32 | % | 7.18 | % | 7.53 | % | 5.00 | % | 4.00 | % |
Common Equity Tier 1 Ratio** | 9.62 | % | 9.22 | % | 9.56 | % | 6.50 | % | 4.50 | % |
Tier 1 Risk-Based Capital Ratio** | 9.62 | % | 9.22 | % | 9.56 | % | 8.00 | % | 6.00 | % |
Total Risk-Based Capital Ratio ** | 10.63 | % | 10.43 | % | 10.87 | % | 10.00 | % | 8.00 | % |
Book Value per Share (BVS) | $ | 5.24 | $ | 5.15 | $ | 8.59 | ||||
**Represents Bank capital ratios | ||||||||||
Sep-25 | Jun-25 | Sep-24 | Sep-25 | Sep-24 | |||||||||
Asset Quality | QTD | QTD | QTD | YTD | YTD | ||||||||
Net Charge Off (Net Recovery) | $ | 14 | $ | 903 | $ | 8,676 | $ | 6,647 | $ | 23,288 | |||
Charge Offs: Commercial-Equipment | $ | 196 | $ | 2,352 | $ | 8,676 | $ | 4,720 | $ | 23,288 | |||
(Recoveries): Commercial-Equipment | $ | (127 | ) | $ | (1,216 | ) | $ | 0 | $ | (1,735 | ) | $ | 0 |
Charge Offs: All Other | $ | 0 | $ | 49 | $ | 0 | $ | 4,069 | $ | 0 | |||
(Recoveries): All Other | $ | (55 | ) | $ | (282 | ) | $ | 0 | $ | (407 | ) | $ | 0 |
Allowance for Credit Losses to Loans % | 1.03 | % | 1.19 | % | 6.59 | % | |||||||
Non-accrual Loans | $ | 5,343 | $ | 5,589 | $ | 7,328 | |||||||
Nonperforming Assets to Total Assets% | 1.35 | % | 1.36 | % | 2.74 | % | |||||||
Additional Credit Disclosures
Loan Segmentation - The following tables present the Bank's total loans outstanding at amortized cost by portfolio segment and by internally assigned grades as of September 30, 2025 and June 30, 2025 (in thousands):
September 30, 2025 | Special | |||||||||||
Portfolio Segment | Pass | Mention | Substandard | Doubtful | Loss | Total | ||||||
Commercial real estate | $ | 149,889 | $ | 4,799 | $ | 11,929 | $ | 3,502 | $ | - | $ | 170,119 |
Residential real estate | 96,003 | 16,137 | 2,821 | - | - | 114,961 | ||||||
Commercial - equipment | - | - | 4,170 | - | - | 4,170 | ||||||
Commercial - all other | 6,617 | - | 183 | - | - | 6,800 | ||||||
Multifamily | 4,525 | - | - | - | - | 4,525 | ||||||
Construction and land | 652 | - | - | - | - | 652 | ||||||
Consumer and other | 37 | - | - | - | - | 37 | ||||||
$ | 257,723 | $ | 20,936 | $ | 19,103 | $ | 3,502 | $ | - | $ | 301,264 | |
June 30, 2025 | Special | |||||||||||
Portfolio Segment | Pass | Mention | Substandard | Doubtful | Loss | Total | ||||||
Commercial real estate | $ | 154,734 | $ | 3,117 | $ | 12,206 | $ | 3,502 | $ | - | $ | 173,559 |
Residential real estate | 111,145 | 12,857 | 2,835 | - | - | 126,837 | ||||||
Commercial - equipment | - | - | 4,275 | 196 | - | 4,471 | ||||||
Commercial - all other | 7,594 | - | 198 | - | - | 7,792 | ||||||
Multifamily | 4,746 | - | - | - | - | 4,746 | ||||||
Construction and land | 670 | - | - | - | - | 670 | ||||||
Consumer and other | 34 | - | - | - | - | 34 | ||||||
$ | 278,923 | $ | 15,974 | $ | 19,514 | $ | 3,698 | $ | - | $ | 318,109 | |
Descriptions of the various risk grades are as follows:
Special Mention: Assets having potential weaknesses that if left uncorrected, may result in decline in borrower's repayment ability. However, these assets are not adversely classified and do not expose the Bank to sufficient risk to warrant adverse classification.
Substandard: An asset is considered substandard if it is inadequately protected by the current net worth and pay capacity of the borrower or of any collateral pledged. Substandard assets include those characterized by the distinct possibility that the Bank will sustain some loss if the deficiencies are not corrected.
Doubtful: Assets classified as doubtful have all the weaknesses inherent in those classified substandard, with the added characteristic that the weaknesses present make collection or liquidation in full highly questionable and improbable on the basis of currently existing facts, conditions, and values.
Loss: Assets classified as loss are those considered uncollectible and of such little value that their continuance as assets without the establishment of a specific loss reserve is not warranted. Any loans downgraded to this category are generally charged off soon after.
Allowance for Credit Losses on Loans - The following tables present the allowance for credit losses under ASC 326, Financial Instruments - Credit Losses by portfolio segment and by internally assigned grades as of September 30, 2025 and June 30, 2025 (in thousands):
September 30, 2025 | Special | ||||||||||||
Portfolio Segment | Pass | Mention | Substandard | Doubtful | Loss | Total | |||||||
Commercial real estate | $ | 879 | $ | 289 | $ | 59 | $ | - | $ | - | $ | 1,227 | |
Residential real estate | 269 | 47 | 121 | - | (894 | ) | (457 | ) | |||||
Commercial - equipment | - | - | 2,085 | - | - | 2,085 | |||||||
Commercial - all other | 227 | - | - | - | - | 227 | |||||||
Multifamily | 6 | - | - | - | - | 6 | |||||||
Construction and land | 12 | - | - | - | - | 12 | |||||||
Consumer and other | 2 | - | - | - | - | 2 | |||||||
$ | 1,395 | $ | 336 | $ | 2,265 | $ | - | $ | (894 | ) | $ | 3,102 | |
June 30, 2025 | Special | ||||||||||||
Portfolio Segment | Pass | Mention | Substandard | Doubtful | Loss | Total | |||||||
Commercial real estate | $ | 1,110 | $ | 15 | $ | 73 | $ | - | $ | - | $ | 1,198 | |
Residential real estate | 754 | 82 | 131 | - | (980 | ) | (13 | ) | |||||
Commercial - equipment | - | - | 2,144 | 196 | - | 2,340 | |||||||
Commercial - all other | 249 | - | - | - | - | 249 | |||||||
Multifamily | 8 | - | - | - | - | 8 | |||||||
Construction and land | 14 | - | - | - | - | 14 | |||||||
Consumer and other | 2 | - | - | - | - | 2 | |||||||
$ | 2,137 | $ | 97 | $ | 2,348 | $ | 196 | $ | (980 | ) | $ | 3,798 | |
Past due loans -The following table presents past due loans at amortized cost by portfolio segment as of September 30, 2025 and June 30, 2025 (in thousands):
September 30, 2025 | 30 - 59 Days | 60 - 89 Days | 90 Days or | Total | Total | |||||||
Portfolio Segment | Past Due | Past Due | More | Past Due | Current | Loans | ||||||
Commercial real estate | $ | - | $ | 45 | $ | 3,682 | $ | 3,727 | $ | 166,392 | $ | 170,119 |
Residential real estate | - | - | - | - | 114,961 | 114,961 | ||||||
Commercial - equipment | 231 | - | - | 231 | 3,939 | 4,170 | ||||||
Commercial - all other | - | - | 183 | 183 | 6,617 | 6,800 | ||||||
Multifamily | - | - | - | - | 4,525 | 4,525 | ||||||
Construction and land | - | - | - | - | 652 | 652 | ||||||
Consumer and other | - | - | - | - | 37 | 37 | ||||||
$ | 231 | $ | 45 | $ | 3,865 | $ | 4,141 | $ | 297,123 | $ | 301,264 | |
June 30, 2025 | 30 - 59 Days | 60 - 89 Days | 90 Days or | Total | Total | |||||||
Portfolio Segment | Past Due | Past Due | More | Past Due | Current | Loans | ||||||
Commercial real estate | $ | - | $ | 64 | $ | 3,682 | $ | 3,746 | $ | 169,813 | $ | 173,559 |
Residential real estate | - | - | - | - | 126,837 | 126,837 | ||||||
Commercial - equipment | - | - | - | - | 4,471 | 4,471 | ||||||
Commercial - all other | - | - | 198 | 198 | 7,594 | 7,792 | ||||||
Multifamily | - | - | - | - | 4,746 | 4,746 | ||||||
Construction and land | - | - | - | - | 670 | 670 | ||||||
Consumer and other | - | - | - | - | 34 | 34 | ||||||
$ | - | $ | 64 | $ | 3,880 | $ | 3,944 | $ | 314,165 | $ | 318,109 | |
Non-accrual loans -Loans are placed on non-accrual once the loan is 90 days past due or sooner if, in management's opinion, the borrower may be unable to meet payment of obligations as they become due, as well as when required by regulatory provisions. The following table presents the nonaccrual loans at amortized cost by portfolio segment as of September 30, 2025 and June 30, 2025 (in thousands):
September 30, 2025 Portfolio Segment | Non-accrual with no Allowance for Credit Losses | Non-accrual with Allowance for Credit Losses | Total Non-accrual | Loans Past Due Over 89 Days Still Accruing | ||||
Commercial real estate | $ | 5,160 | $ | - | $ | 5,160 | $ | - |
Commercial - equipment | - | - | - | - | ||||
Commercial - all other | 183 | - | 183 | - | ||||
$ | 5,343 | $ | - | $ | 5,343 | $ | - | |
June 30, 2025 Portfolio Segment | Non-accrual with no Allowance for Credit Losses | Non-accrual with Allowance for Credit Losses | Total Non-accrual | Loans Past Due Over 89 Days Still Accruing | ||||
Commercial real estate | $ | 5,196 | $ | - | $ | 5,196 | $ | - |
Commercial - equipment | $ | - | $ | 196 | $ | 196 | $ | - |
Commercial - all other | 198 | - | 198 | - | ||||
$ | 5,393 | $ | 196 | $ | 5,589 | $ | - | |
U & I Financial Corp.
Investor Relations
[email protected]
SOURCE: U & I Financial Corp.
View the original press release on ACCESS Newswire
P.Costa--AMWN