Solera National Bancorp Announces Fourth Quarter 2025 Financial Results
 Korea's Severe Asthma Patients Blocked from Biologics by Restrictive Reimbursement Rules
 Shanghai Science and Technology Museum Signs Pacts With London and Ottawa Institutions at CIIE
 RBI Data Reveals Divergence in Credit Card Spending and Debit Card Cash Withdrawals
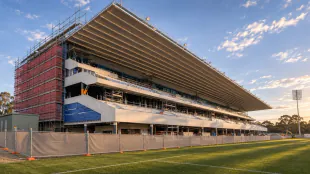 Panthers expected to begin 2027 NRL season away from new stadium
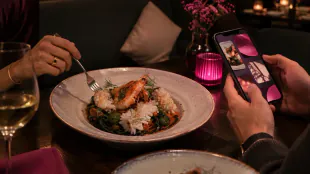 Sweet As app launches restaurant discovery platform
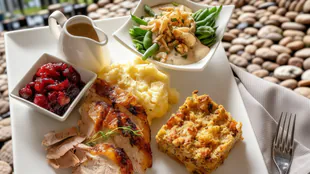 Phoenix Restaurants Offer Thanksgiving Dinner to Go for Pickup
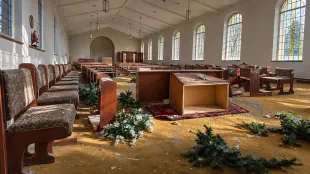 Mayo school appeals for information after convent and chapel vandalism
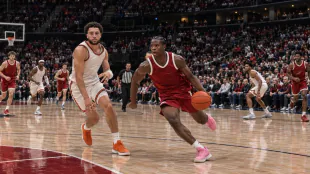 Virginia overwhelms Arkansas 91-72 behind balanced scoring
 Second major storm brings destructive winds and outages to British Columbia
 Godzilla Minus Zero leads North American box office with $31.6m
 Advocate calls for coordinated support for children facing trafficking
 Medicare Open Enrollment Ends Dec. 7: Review Your Coverage Options
 US Treasury order targets bank transfers linked to crypto exchange MEXC
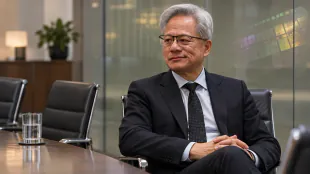
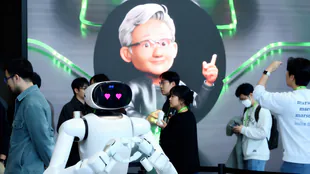 Nvidia CEO Controversy Sparks Fears of Tighter U.S. AI Chip Curbs for Samsung and SK hynix
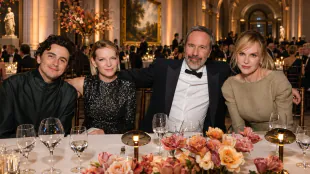 Villeneuve teases James Bond casting at Los Angeles museum gala
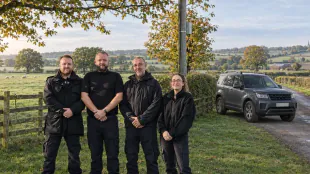 Nottinghamshire launches specialist rural crime policing team
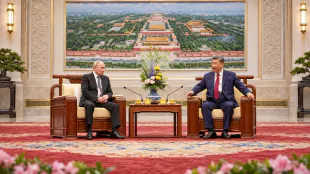 China confirms talks over possible Xi-Putin-Trump summit
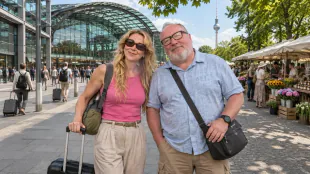 Rail journey offers a slower route to a Berlin city break
 Arsenal control title race as Manchester United fall into bottom three
 Suspected Krakow gunman dies after attack that killed six
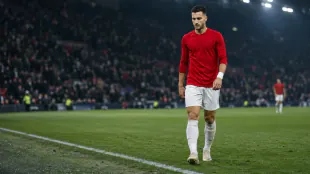 Carrick backs Dalot after hostile reception from Manchester United fans
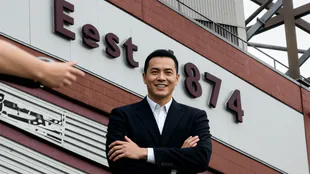 Aston Villa Defy History With Rare Victory at Old Trafford
Q4 2025 pre-tax and pre-provision income of $9.0 million, a NEW RECORD!
Net income of $5.9 million ($1.37 per share).
LAKEWOOD, CO / ACCESS Newswire / January 30, 2026 / Solera National Bancorp, Inc. (OTC:SLRK) ("Company"), the holding company for Solera National Bank ("Bank"), a business-focused bank located in the Denver metropolitan area, today reported financial results for the three months ended December 31, 2025. See highlights below.
4Q25 Financial Highlights
Pre-tax pre-provision income of $9.0 million, a $2.1 million or 31% increase from Q4 2024.
Non-interest income of $3.9 million, a $2.4 million increase, or a 172% increase from Q4 2024.
Tangible book value per share was $24.86/share, a $4.17 or 20% increase from Q4 2024.
Return on assets was 1.74%.
Return on equity was 22.28%.
Efficiency ratio was 50.56%.
Steve Snailum, COO, commented: "A record quarter to close out a record year. Solera continues to demonstrate strategic execution and agility through relentless evaluation of all internal and external opportunities. The ability of the staff to execute their roles with extreme efficiency and accuracy has enabled the bank to grow in a way that benefits shareholders, customers, and employees. I am so proud of the work that the team here has done and could not be more excited about the year ahead."
Jordan Wright, Board Member, commented: "The team at Solera has delivered an incredible quarter, yet again. We feel grateful for an excellent 2025, exceeding our own expectations for the year due to some unique opportunities that came our way. Our success with earnings over the last few years has been nothing short of astounding. While the results from 2025 will be difficult to beat, we have positioned ourselves for strong performance in 2026 and are very optimistic about the future of this bank."
Joey Warmenhoven, Board Member, commented: "SLRK has again posted an excellent quarter. Our consistent performance is a true testament to the hard work of our team. We are in the top percentile of community banks for earnings. Our team continues to find a way to generate strong ROA and ROE numbers despite challenging banking environments."
About Solera National Bancorp, Inc.
Solera National Bancorp, Inc. was incorporated in 2006 to organize and serve as the holding company for Solera National Bank, which opened for business in September 2007. Solera National Bank is a community bank serving the needs of emerging businesses and real estate investors. At the core of Solera National Bank is welcoming, attentive, and respectful customer service, a focus on supporting a growing and diverse economy, and a passion to serve our community through service, education, and volunteerism. For more information, please visit http://www.SoleraBank.com.
This press release contains statements that may constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. The statements contained in this release, which are not historical facts and that relate to future plans or projected results of Solera National Bancorp, Inc. and its wholly-owned subsidiary, Solera National Bank, are forward-looking statements. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from those projected, anticipated, or implied. We undertake no obligation to update or revise any forward-looking statement. Readers of this release are cautioned not to put undue reliance on forward-looking statements.
Contacts: Jay Hansen, CFO (303) 209-8600
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED BALANCE SHEET
(unaudited)
($000s) | 12/31/2025 | 9/30/2025 | 6/30/2025 | 3/31/2025 | 12/31/2024 | |||||
ASSETS | ||||||||||
Cash and due from banks | $ | 2,280 | $ | 1,378 | $ | 1,969 | $ | 2,401 | $ | 1,576 |
Federal funds sold | - | 23,900 | - | - | 800 | |||||
Interest-bearing deposits with banks | 1,706 | 1,872 | 2,963 | 1,033 | 148 | |||||
Investment securities, available-for-sale | 650,464 | 324,376 | 422,112 | 290,397 | 322,375 | |||||
FHLB and Federal Reserve Bank stocks, at cost | 16,144 | 3,171 | 5,004 | 5,525 | 7,457 | |||||
Paycheck Protection Program (PPP) loans, gross | - | - | - | 5 | 20 | |||||
Net PPP loans | - | - | - | 5 | 20 | |||||
Traditional loans, gross | 829,057 | 764,433 | 754,518 | 766,687 | 792,753 | |||||
Allowance for loan and lease losses | (12,225 | ) | (11,218 | ) | (11,219 | ) | (10,914 | ) | (10,913 | ) |
Net traditional loans | 816,832 | 753,215 | 743,299 | 755,773 | 781,840 | |||||
Premises and equipment, net | 36,469 | 36,911 | 35,128 | 33,236 | 33,476 | |||||
Accrued interest receivable | 12,609 | 8,148 | 10,244 | 7,153 | 7,750 | |||||
Bank-owned life insurance | 5,256 | 5,223 | 5,190 | 5,159 | 5,127 | |||||
Other assets | 11,094 | 11,032 | 13,433 | 11,103 | 8,820 | |||||
TOTAL ASSETS | $ | 1,552,854 | $ | 1,169,226 | $ | 1,239,342 | $ | 1,111,785 | $ | 1,169,389 |
LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||||
Noninterest-bearing demand deposits | $ | 471,977 | $ | 452,965 | $ | 463,861 | $ | 466,455 | $ | 484,604 |
Interest-bearing demand deposits | 97,338 | 88,048 | 65,761 | 60,507 | 54,734 | |||||
Savings and money market deposits | 134,847 | 121,868 | 138,964 | 104,560 | 100,987 | |||||
Time deposits | 421,479 | 358,976 | 436,547 | 287,378 | 294,338 | |||||
Total deposits | 1,125,641 | 1,021,857 | 1,105,133 | 918,900 | 934,663 | |||||
Accrued interest payable | 1,531 | 1,587 | 2,528 | 1,808 | 2,587 | |||||
Short-term borrowings | 278,525 | - | - | 60,191 | 104,607 | |||||
Long-term FHLB borrowings | 34,000 | 34,000 | 34,000 | 34,000 | 34,000 | |||||
Accounts payable and other liabilities | 6,267 | 6,392 | 5,336 | 6,087 | 4,576 | |||||
TOTAL LIABILITIES | 1,445,964 | 1,063,836 | 1,146,997 | 1,020,987 | 1,080,434 | |||||
Common stock | 43 | 43 | 43 | 43 | 43 | |||||
Additional paid-in capital | 38,748 | 38,793 | 38,778 | 38,763 | 38,748 | |||||
Retained earnings | 95,461 | 89,549 | 83,008 | 77,076 | 72,455 | |||||
Accumulated other comprehensive (loss) gain | (27,362 | ) | (22,995 | ) | (29,484 | ) | (25,084 | ) | (22,291 | ) |
TOTAL STOCKHOLDERS' EQUITY | 106,890 | 105,390 | 92,345 | 90,798 | 88,955 | |||||
TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $ | 1,552,854 | $ | 1,169,226 | $ | 1,239,342 | $ | 1,111,785 | $ | 1,169,389 |
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS (unaudited)
Three Months Ended
($000s, except per share data) | 12/31/2025 | 9/30/2025 | 6/30/2025 | 3/31/2025 | 12/31/2024 | |||||
Interest and dividend income | ||||||||||
Interest and fees on traditional loans | $ | 13,632 | $ | 12,802 | $ | 12,791 | $ | 13,101 | $ | 13,615 |
Investment securities | 5,515 | 4,275 | 4,831 | 3,490 | 3,297 | |||||
Dividends on bank stocks | 194 | 91 | 180 | 175 | 131 | |||||
Other | 28 | 26 | 21 | 49 | 13 | |||||
Total interest income | $ | 19,369 | $ | 17,194 | $ | 17,823 | $ | 16,815 | $ | 17,056 |
Interest expense | ||||||||||
Deposits | 6,867 | 6,463 | 6,235 | 4,959 | 5,564 | |||||
FHLB & Fed borrowings | 1,588 | 550 | 1,410 | 1,550 | 1,223 | |||||
Total interest expense | 8,455 | 7,013 | 7,645 | 6,509 | 6,787 | |||||
Net interest income | 10,914 | 10,181 | 10,178 | 10,306 | 10,269 | |||||
Provision for loan and lease losses | 1,010 | 6 | 310 | 7 | 6 | |||||
Net interest income after provision for loan and lease losses | 9,904 | 10,175 | 9,868 | 10,299 | 10,263 | |||||
Noninterest income | ||||||||||
Customer service and other fees | 262 | 284 | 291 | 300 | 470 | |||||
Other income | 310 | 711 | 677 | 807 | 954 | |||||
Gain on sale of securities | 3,297 | 2,986 | 2,709 | - | - | |||||
Total noninterest income | 3,869 | 3,981 | 3,677 | 1,107 | 1,424 | |||||
Noninterest expense | ||||||||||
Employee compensation and benefits | 2,560 | 2,838 | 2,827 | 2,656 | 2,611 | |||||
Occupancy | 550 | 538 | 553 | 448 | 492 | |||||
Professional fees | 1,137 | 677 | 330 | 259 | 309 | |||||
Other general and administrative | 1,560 | 1,629 | 1,593 | 1,694 | 1,437 | |||||
Total noninterest expense | 5,807 | 5,682 | 5,303 | 5,057 | 4,849 | |||||
Net Income Before Taxes | $ | 7,966 | $ | 8,474 | $ | 8,242 | $ | 6,349 | $ | 6,838 |
Income Tax Expense | 2,054 | 1,934 | 2,309 | 1,711 | 1,526 | |||||
Net Income | $ | 5,912 | $ | 6,540 | $ | 5,933 | $ | 4,638 | $ | 5,312 |
Income Per Share | $ | 1.37 | $ | 1.52 | $ | 1.38 | $ | 1.08 | $ | 1.24 |
Tangible Book Value Per Share | $ | 24.86 | $ | 24.51 | $ | 21.48 | $ | 21.12 | $ | 20.69 |
WA Shares outstanding | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | |||||
Pre-Tax Pre-Provision Income | $ | 8,976 | $ | 8,480 | $ | 8,552 | $ | 6,356 | $ | 6,844 |
Net Interest Margin | 3.55 | % | 3.70 | % | 3.56 | % | 3.93 | % | 3.81 | % |
Cost of Funds | 2.72 | % | 2.54 | % | 2.66 | % | 2.49 | % | 2.51 | % |
Efficiency Ratio | 50.56 | % | 50.84 | % | 47.58 | % | 44.31 | % | 41.47 | % |
Return on Average Assets | 1.74 | % | 2.17 | % | 2.02 | % | 1.63 | % | 1.82 | % |
Return on Average Equity | 22.28 | % | 26.46 | % | 25.92 | % | 20.64 | % | 23.86 | % |
Leverage Ratio | 8.6 | % | 11.0 | % | 9.8 | % | 10.4 | % | 9.5 | % |
Asset Quality: | ||||||||||
Non-performing loans to gross loans | 0.55 | % | 0.59 | % | 0.60 | % | 0.42 | % | 0.52 | % |
Non-performing assets to total assets | 0.29 | % | 0.39 | % | 0.37 | % | 0.29 | % | 0.35 | % |
Allowance for loan losses to gross traditional loans | 1.47 | % | 1.47 | % | 1.49 | % | 1.42 | % | 1.38 | % |
* Not meaningful due to the insignificant amount of non-performing loans. | ||||||||||
Criticized loans/assets: | ||||||||||
Special mention | $ | 18,986 | $ | 19,306 | $ | 2,842 | $ | 11,103 | $ | 10,730 |
Substandard: Accruing | 44,873 | 35,447 | 39,971 | 19,641 | 14,911 | |||||
Substandard: Nonaccrual | 4,757 | 8,281 | 4,526 | 3,251 | 4,142 | |||||
Doubtful | - | - | - | - | - | |||||
Total criticized loans | $ | 68,616 | $ | 63,034 | $ | 47,339 | $ | 33,995 | $ | 29,782 |
Other real estate owned | - | - | - | - | - | |||||
Investment securities | - | - | - | - | - | |||||
Total criticized assets | $ | 68,616 | $ | 63,034 | $ | 47,339 | $ | 33,995 | $ | 29,782 |
Criticized assets to total assets | 4.42 | % | 5.39 | % | 3.82 | % | 3.06 | % | 2.55 | % |
SOURCE: Solera National Bancorp, Inc.
View the original press release on ACCESS Newswire
O.Karlsson--AMWN